

The Chemours Company CC reported a net income of $196 million or $1.29 per share for the third quarter of 2026. This compares favorably with the year-ago quarter’s net income of $46 million or 31 cents per share.
Barring one-time items, earnings were 21 cents per share, which missed the Zacks Consensus Estimate of 26 cents by 19.2%.
Net sales rose 3% year over year to $1,540 million but missed the consensus estimate of $1,541.6 million by 0.1%. Higher titanium dioxide pricing and strength in Performance Solutions supported sales, while lower refrigerant volumes weighed on results.
Adjusted EBITDA increased 6% year over year to $200 million from $189 million. The improvement was driven by stronger Titanium Technologies (TT) pricing and growth in Advanced Performance Materials (APM) Performance Solutions, partially offset by lower Thermal & Specialized Solutions (TSS) volumes and higher costs across the businesses.
The Chemours Company Price, Consensus and EPS Surprise
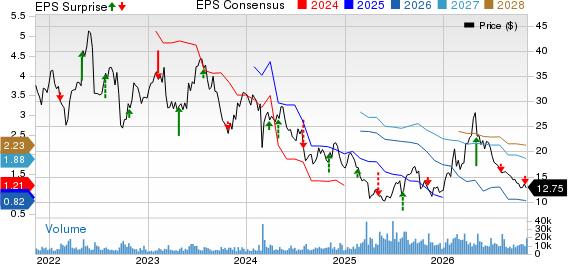
The Chemours Company price-consensus-eps-surprise-chart | The Chemours Company Quote
Chemours' Segment Highlights
The TSS segment recorded revenues of $510 million in the third quarter, declining 9% year over year. The figure beat our estimate of $502.6 million. The decrease was primarily attributable to a 9% decline in volumes, reflecting weaker North American stationary air-conditioning aftermarket sales of Opteon blends against elevated demand in the prior-year quarter.
TSS adjusted EBITDA declined 30% year over year to $136 million. Adjusted EBITDA margin contracted eight percentage points to 27%, reflecting lower Opteon stationary aftermarket sales and higher costs.
The TT division generated revenues of $680 million, increasing 11% from the prior-year quarter. The figure missed our estimate of $694.9 million. The improvement was driven by a 10% increase in global pricing and a 1% rise in volumes, partly offset by a slight currency headwind. Pricing improved across all regions following recent price announcements. Volume growth in North America, Latin America and Asia-Pacific excluding China more than offset weakness in Europe, the Middle East and Africa, and China.
TT adjusted EBITDA surged 240% year over year to $85 million. Adjusted EBITDA margin expanded nine percentage points to 13%, supported by higher pricing and volumes, partially offset by modest cost inflation.
The APM segment recorded revenues of $337 million, up 8% year over year. The figure fell behind our estimate of $347.5 million. The increase reflected a 6% improvement in pricing and a 2% rise in volumes, partially offset by a slight currency headwind.
APM adjusted EBITDA increased 71% year over year to $24 million. Adjusted EBITDA margin improved two percentage points to 7%, aided by a favorable product mix, partially offset by higher operating costs.
CC's Cash Flow and Liquidity Position
Operating cash flow in the third quarter was $149 million compared with $146 million in the year-ago quarter. The figure included $150 million in PFAS insurance proceeds, partially offset by approximately $100 million in settlement payments and $25 million in taxes related to the Kuan Yin property sale.
Capital expenditures increased to $51 million from $41 million a year earlier. Free cash flow declined to $98 million from $105 million.
As of Sept. 30, 2026, Chemours had consolidated gross debt of $3.9 billion. Debt, net of $698 million in unrestricted cash and cash equivalents, was $3.2 billion. Total liquidity was $1.7 billion, with a net leverage ratio of approximately 4.3.
Chemours' Outlook for Q4 and FY26
For the fourth quarter, Chemours expects consolidated net sales to decline 5-10% sequentially, primarily due to seasonal weakness in TSS and TT. Adjusted EBITDA is projected at $160-$185 million, with corporate expenses of $40-$45 million.
TSS adjusted EBITDA is expected at $105-$115 million, while TT adjusted EBITDA is projected at $60-$65 million. APM adjusted EBITDA is anticipated at $40-$45 million, supported by continued Performance Solutions demand.
For 2026, Chemours expects net sales to grow approximately 2% year over year, with adjusted EBITDA of $775-$800 million. Capital expenditures are projected at $220-$230 million, with free cash flow conversion above 15%. The company now expects its net leverage ratio to fall below 4.2 by year-end.
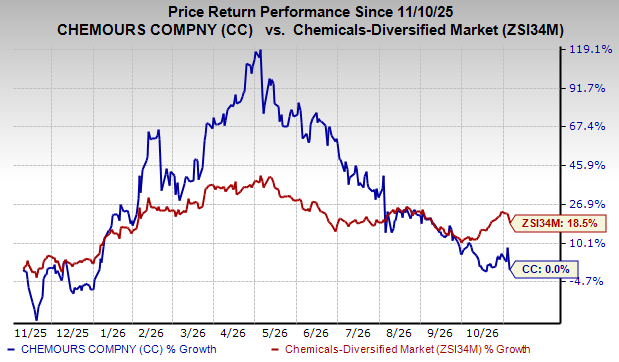
CC's shares have remained flat over the past year compared with the industry’s 18.5% growth.
Image Source: Zacks Investment Research
CC’s Zacks Rank & Key Picks
CC currently carries a Zacks Rank #5 (Strong Sell).
Some better-ranked stocks in the Basic Materials space are Reliance, Inc. RS, Element Solutions Inc. ESI and Avino Silver & Gold Mines Ltd. ASM.
RS and ESI currently sport a Zacks Rank #1 (Strong Buy) each, while ASM carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank stocks here
The Zacks Consensus Estimate for RS’ 2026 earnings is pegged at $23.70 per share, indicating a 66.2% year-over-year surge. RSshares have gained 53.3% over the past year.
The Zacks Consensus Estimate for ESI’s 2026 earnings is pegged at $1.85 per share, indicating a year-over-year rise of 24.2%. Its earnings beat the Zacks Consensus Estimate in each of the trailing four quarters, with the average surprise being 6%.
The Zacks Consensus Estimate for ASM’s current fiscal-year earnings is pinned at 28 cents per share. Its earnings beat the Zacks Consensus Estimate in each of the trailing four quarters, with the average surprise being 75%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
The Chemours Company (CC): Free Stock Analysis Report
Element Solutions Inc. (ESI): Free Stock Analysis Report
Reliance, Inc. (RS): Free Stock Analysis Report
Avino Silver (ASM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).