

Walmart Inc. WMT continues to see encouraging transaction growth at its Sam’s Club U.S. business, supported by expanding membership and digital convenience. The warehouse club format is benefiting from higher shopping volumes across key merchandise categories, while growing adoption of digital services is providing additional support. These trends highlight the importance of member engagement in sustaining sales momentum.
In second-quarter fiscal 2027, Sam’s Club U.S. transactions increased 7% compared with 3.9% growth in the year-ago quarter. Comparable sales, excluding fuel, rose 4.4%, driven by higher transactions and unit volumes, with strength across grocery and general merchandise. However, average ticket declined 2.5% against 2% growth a year earlier.
Membership trends remained favorable. Membership fee revenues increased 6%, reflecting steady growth in member counts and higher Plus membership penetration. Gen Z and millennials accounted for more than half of new member sign-ups, with Plus penetration exceeding 50% among this group.
Digital capabilities are also contributing to the business's momentum. Sam’s Club U.S. eCommerce sales grew 26%, representing approximately 20% of net sales, excluding fuel. Club-fulfilled delivery recorded triple-digit growth following the April launch of one-hour delivery. Meanwhile, Scan & Go adoption improved approximately 110 basis points.
Looking ahead, the key consideration is whether stronger transaction volumes can continue supporting comparable sales amid declining average ticket values. While membership growth and digital adoption remain encouraging, comparable-sales growth moderated from 5.9% a year earlier. Sustained transaction growth, alongside improved basket values, would provide a stronger foundation for Sam’s Club’s sales momentum.
What Do the Latest Metrics Say About Walmart?
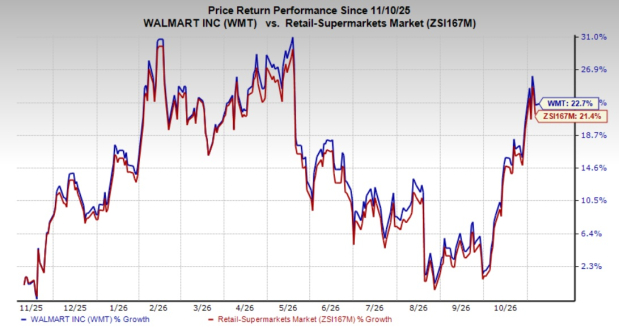
Walmart, which competes with Costco Wholesale Corporation COST and Target Corporation TGT, has seen its shares gain 22.7% over the past year compared with the industry’s growth of 21.4%. Costco shares have climbed 16.5%, while Target has surged 82.9% in the aforementioned period.
Image Source: Zacks Investment Research
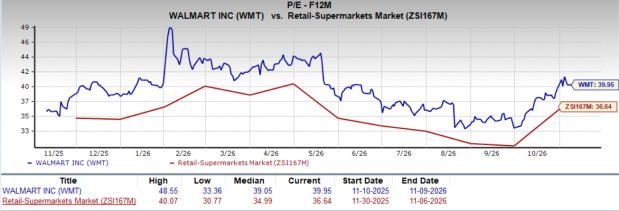
From a valuation standpoint, Walmart's forward 12-month price-to-earnings ratio stands at 39.95, higher than the industry’s 36.64. The company is trading at a premium to Target (with a forward 12-month P/E ratio of 17.10) while trading at a discount to Costco (46.08).
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for Walmart’s current fiscal-year sales and earnings per share implies year-over-year growth of 6.9% and 9.1%, respectively.
Walmart currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Walmart Inc. (WMT): Free Stock Analysis Report
Target Corporation (TGT): Free Stock Analysis Report
Costco Wholesale Corporation (COST): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).