

T1 Energy Inc TE is scheduled to release third-quarter 2026 results on Nov. 12, before market open. The company delivered a negative earnings surprise of 7.7% in the last reported quarter.
Let’s discuss the factors that are likely to be reflected in the upcoming quarterly results.
Factors Likely to Have Impacted TE’s Q3 Performance
In July 2026, T1 Energy acquired solar patents and other intellectual property and other assets from Singapore-based Evervolt Green Energy Holding Pte Ltd. for a total consideration of $135 million. This is expected to have improved its cost structure, strengthened its technology portfolio and enhanced its competitive position in the U.S. solar market. The acquisition also gives the company greater control over an advanced, high-efficiency solar technology, which could help differentiate its products and make them more competitive against imported solar modules.
T1 Energy expects stronger operating results in the third quarter, with production and delivery run rates exceeding the second-quarter levels. The company produced 935 MW of solar modules in the previous quarter, its second-highest quarterly production at G1_Dallas, with volumes increasing sequentially throughout the quarter.
T1's commercial pipeline is gaining momentum, supported by its 641 MW strategic offtake agreement with Clearway Energy Group, announced in August 2026. This agreement adds to the existing 900 MW Treaty Oak contract and strengthens demand visibility for T1's solar modules incorporating domestically manufactured cells from G2_Austin.
Management expects adjusted EBITDA to improve during the second half of 2026, with third-and fourth-quarter production and delivery run rates expected to exceed the previous quarter’s levels.
TE’s quarterly results are expected to be affected by higher selling, general and administrative expenses, led by higher legal, financing and advisory costs, ongoing litigation and workforce expansion for G2_Austin. Continued spending in these areas could have pressured operating profitability in the third quarter, although some event-related expenses are expected to normalize over time.
Q3 Expectations for TE
The Zacks Consensus Estimate for earnings is pegged at a loss of 12 cents per share, indicating a year-over-year improvement of 85.9%.
The consensus estimate for revenues is pinned at $274.83 million, implying a 30.6% increase year over year.
What Our Quantitative Model Predicts
Our proven model does not predict an earnings beat for T1 Energy this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is not the case here, as you will see below.
T1 Energy Inc Price and EPS Surprise
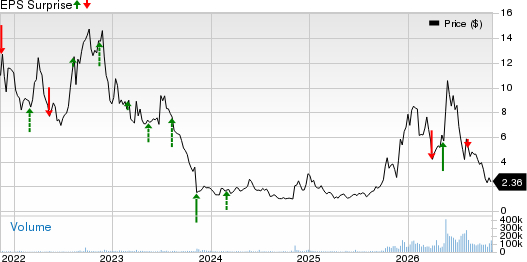
T1 Energy Inc price-eps-surprise | T1 Energy Inc Quote
Earnings ESP: The company’s Earnings ESP is +33.33%. You can uncover the best stocks before they’re reported with our Earnings ESP Filter.
Zacks Rank: Currently, First Solar carries a Zacks Rank of 4 (Sell). You can see the complete list of today's Zacks #1 Rank stocks here.
Recent Solar Release
Enphase Energy, Inc. ENPH reported third-quarter 2026 adjusted earnings of 41 cents per share, which missed the Zacks Consensus Estimate of 47 cents by 12.8%. The bottom line declined 54.4% from 90 cents in the year-ago quarter.
Enphase Energy's third-quarter revenues of $293.3 million lagged the Zacks Consensus Estimate of $304 million by 3.4%. The top line also dropped 28.5% from the prior-year quarter's reported figure of $410.4 million.
First Solar FSLR reported third-quarter 2026 earnings of $5.30 per share, which beat the Zacks Consensus Estimate of $4.64 by 14.2%. The bottom line increased 25% from $4.24 in the year-ago quarter.
FSLR’s net sales of $1.23 billion missed the consensus estimate of $1.313 billion by 6.2% and declined 23% year over year.
SolarEdge Technologies, Inc. SEDG reported third-quarter 2026 adjusted earnings of 29 cents per share, which surpassed the Zacks Consensus Estimate of 2 cents. The company had incurred an adjusted loss of 31 cents per share in the year-ago quarter.
SEDG’s revenues totaled $326.1 million, down 4.1% year over year, and missed the Zacks Consensus Estimate of $329 million by 0.9%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
T1 Energy Inc (TE): Free Stock Analysis Report
First Solar, Inc. (FSLR): Free Stock Analysis Report
Enphase Energy, Inc. (ENPH): Free Stock Analysis Report
SolarEdge Technologies, Inc. (SEDG): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).