

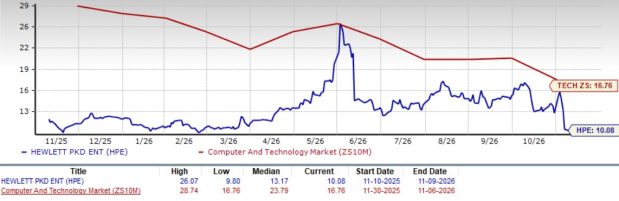
Hewlett Packard Enterprise HPE trades at a forward price-to-earnings (P/E) multiple of 10.08X, below the Zacks Computer and Technology sector’s P/E of 16.76X. The discounted valuation of HPE stock is further substantiated by the Zacks Value Score of A.
HPE Forward 12-Month (P/S) Valuation Chart
Image Source: Zacks Investment Research
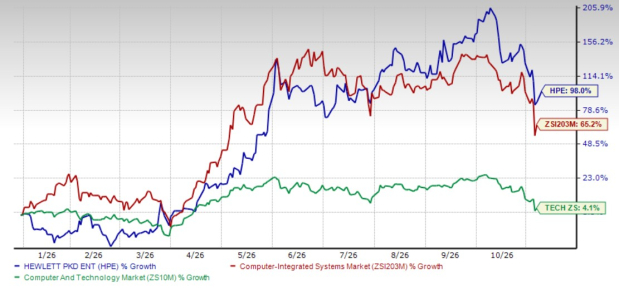
The discounted valuation remains despite HPE stock climbing 98% year to date, outperforming the broader sector and the Zacks Computer - Integrated Systems industry’s return of 65.2% and 4.1%, respectively.
HPE YTD Performance Chart
Image Source: Zacks Investment Research
HPE Experiences Growth Across Cloud and Networking
Hewlett Packard Enterprise operates across three primary business segments, namely Cloud & AI, Networking, and Corporate Investments and Other, serving enterprise customers with infrastructure, software, services and flexible consumption solutions. Cloud & AI combines HPE’s server, storage and financial services businesses.
HPE’s server portfolio includes general-purpose and workload-optimized systems, high-performance computing, supercomputing, AI infrastructure, data analytics and transaction processing. Its storage offerings include HPE Alletra, unstructured data solutions, data protection, GreenLake Flex and related software. The segment is benefiting from growing demand for AI-ready servers and enterprise infrastructure. In the third quarter of fiscal 2026, Cloud & AI generated $9.04 billion in revenues, up 25.4% year over year.
HPE’s networking develops and sells network and security products and services across campus, branch, data center, routing and security markets. Its portfolio includes wireless access points, switches, routers, gateways, network-management software, support and professional services. The acquisition of Juniper Networks has expanded HPE’s networking capabilities and exposure to AI data center infrastructure. HPE’s networking revenues reached $2.89 billion in the third quarter of fiscal 2026, rising 10% on a normalized basis.
Corporate Investments and Other includes Advisory and Professional Services, Telco, Instant On and Hewlett Packard Labs. These activities complement HPE’s broader technology portfolio through consulting, specialized connectivity offerings and research. Across these businesses, HPE is also expanding GreenLake, its consumption-based hybrid cloud platform, connecting infrastructure, software and services. Together, its three segments position HPE to address demand for AI infrastructure, modern networking and hybrid cloud environments.
HPE Wins Against Competitors With Diverse Portfolio
HPE competes with Super Micro Computer SMCI, Dell Technologies DELL and Cisco CSCO in the AI infrastructure market. However, HPE’s ability to package compute, storage, networking and services into pre-configured solutions can reduce deployment complexity for enterprises and sovereign customers while giving it an edge over its competitors. Super Micro Computer is on track to scale rack production capacity to more than 6,000 AI racks per month by the end of fiscal 2026, including 3,000 direct liquid cooling racks monthly.
Super Micro Computer is already shipping 150kW AI racks in volume and preparing 250kW and 500kW rack solutions to support future high-density AI training and inference workloads. Dell Technologies is a major supplier of servers and storage systems, with a broad customer base across enterprises and cloud providers. Its scale, established distribution and service offerings give it an edge in winning large contracts.
Cisco has also taken $5.3 billion of hyperscaler AI infrastructure orders in fiscal 2026 and raised its full-year order outlook to $9 billion from $5 billion. However, HPE’s ability to package compute, storage, networking and services into pre-configured solutions can reduce deployment complexity for enterprises and sovereign customers. This gives HPE an edge over its competitors.
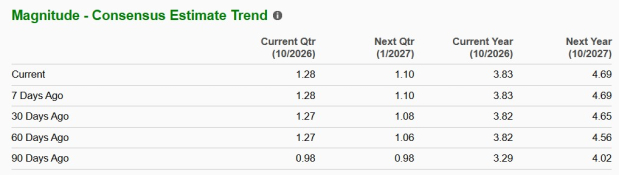
HPE is also able to keep its margin stable. The Zacks Consensus Estimate for HPE’s fiscal 2026 margin reflects year-over-year growth of 97%. Estimates have been revised upward over the past 30 days.
Image Source: Zacks Investment Research
Conclusion: Buy HPE Stock Now
Hewlett Packard Enterprise’s strong AI infrastructure momentum, expanding AI backlog, growing GreenLake adoption and integrated portfolio support its growth outlook. Despite a sharp share price rally, HPE’s valuation remains attractive relative to industry peers. Given these factors, it’s prudent to accumulate this Zacks Rank #2 (Buy) stock at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Hewlett Packard Enterprise Company (HPE): Free Stock Analysis Report
Cisco Systems, Inc. (CSCO): Free Stock Analysis Report
Dell Technologies Inc. (DELL): Free Stock Analysis Report
Super Micro Computer, Inc. (SMCI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).