

Copa Holdings, S.A. CPA is scheduled to release third-quarter 2026 results on Nov. 19, before the market opens.
The airline exits the September-end quarter amid elevated fuel costs, higher operating expenses and margin pressure from its expanding capacity base. Although demand across its network remains healthy, fuel-price volatility and rising costs associated with airport handling, maintenance and flight operations are likely to have weighed on profitability.
The Zacks Consensus Estimate for the third-quarter 2026 earnings has been revised upward by 0.5% over the past 60 days to $4 per share. The consensus mark indicates a decline of 4.76% increase from the third-quarter 2025 actuals. The Zacks Consensus Estimate for third-quarter 2026 revenues is pegged at $1.18 billion, indicating a 28.87% increase from third-quarter 2025 actuals.
Copa Holdings, S.A. Price and EPS Surprise
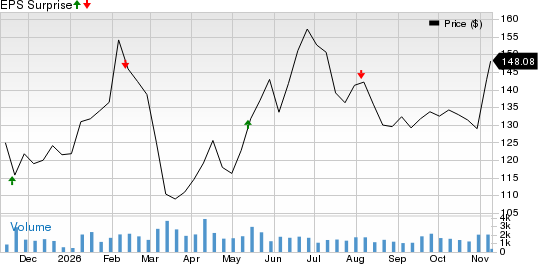
Copa Holdings, S.A. price-eps-surprise | Copa Holdings, S.A. Quote
CPA has an encouraging earnings surprise history. The company’s earnings have outpaced the Zacks Consensus Estimate in two of the trailing four quarters (missing in the remaining two), delivering an average beat of 0.92%.
Factors Likely to Have Influenced CPA’s Q3 Performance
Elevated Fuel Costs: Fuel prices are likely to have remained the biggest headwind. Copa’s 2026 outlook assumed an all-in fuel price of $3.60 per gallon, while management has continued to characterize fuel prices as elevated and volatile. Higher fuel expenses could have limited the benefit of strong demand and pricing.
Higher Operating Expenses: Capacity growth is also likely to have increased several operating cost items. Copa has been incurring higher expenses related to passenger servicing, airport facilities, maintenance, depreciation and flight operations as its network and fleet expand.
Margin Pressure: Despite healthy revenue trends, the company’s operating margin has remained sensitive to cost inflation. Management expects a 17-19% operating margin for 2026, below the 22.6% level recorded in 2025, reflecting the impact of the higher fuel environment.
Capacity-Related Execution Risk: Copa raised its 2026 capacity growth outlook to 14-15%, supported by faster aircraft deliveries and higher utilization. While this expands revenue opportunities, adding capacity can also increase fixed and variable costs and raises the importance of maintaining strong yields and load factors.
What Our Model Says About CPA
Our proven model does not conclusively predict an earnings beat for Copa Holdings this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. But that is not the case here.
CPA has an Earnings ESP of -1.96% and a Zacks Rank #4 (Sell) at present. You can uncover the best stocks to buy or sell before they're reported with our Earnings ESP Filter. You can see the complete list of today’s Zacks #1 Rank stocks here.
CPA Q2 Highlights
Copa reported second-quarter 2026 earnings of $1.67 per share, down 53.9% year over year. The figure missed the Zacks Consensus Estimate of $1.88 by 11.2%, mainly due to a sharp increase in jet fuel costs.
Quarterly revenues rose 25.7% year over year to $1.06 billion but missed the consensus mark of $1.07 billion by 0.6%. Passenger yields increased 8.7%, while revenue per available seat mile rose 7.9% year over year.
Q3 Performance of Other Transportation Companies
Alaska Air Group, Inc. ALK reported third-quarter 2026 adjusted earnings of 36 cents per share, excluding certain tax impacts, beating the Zacks Consensus Estimate of 35 cents by 2.9%. The company reported adjusted earnings of $1.05 per share a year earlier. Higher fuel expenses weighed on profitability despite strong revenue momentum.
Operating revenues increased 14.4% year over year to $4.30 billion but marginally missed the consensus mark of $4.31 billion by 0.1%.
Wabtec Corporation WAB reported mixed third-quarter 2026 results, wherein earnings surpassed the Zacks Consensus Estimate while revenues missed the same.
Quarterly earnings (excluding 41 cents from non-recurring items) of $2.83 per share beat the Zacks Consensus Estimate of $2.72 by 4.04% and increased 22% year over year. Revenues climbed 8.1% year over year to $3.12 billion but missed the consensus mark of $3.18 billion by 2%. The trailing 12-month backlog increased 8.8% to $8.99 billion.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Copa Holdings, S.A. (CPA): Free Stock Analysis Report
Alaska Air Group, Inc. (ALK): Free Stock Analysis Report
Wabtec (WAB): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).