

Cerebras Systems CBRS is set to release its third-quarter 2026 results on Nov. 12.
For the third quarter of 2026, Cerebras expects core revenues to be in the range of $214-$216 million.
The Zacks Consensus Estimate for revenues is pegged at $215.82 million. Cerebras reported revenues of $209.87 million in the second quarter of 2026.
The consensus mark for loss has been steady at 13 cents per share over the past 30 days. Cerebras reported a loss of 4 cents per share in the second quarter of 2026, narrower than the Zacks Consensus Estimate, delivering an 80.95% earnings surprise.
Cerebras Systems Inc. Price and EPS Surprise
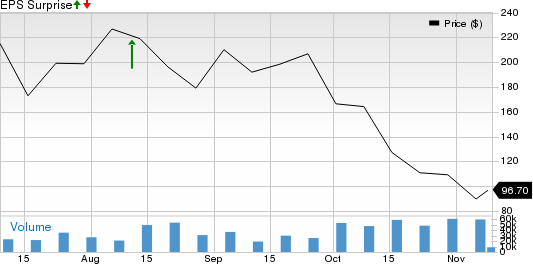
Cerebras Systems Inc. price-eps-surprise | Cerebras Systems Inc. Quote
Let’s see how things are shaping up prior to this announcement.
Key Factors to Note for Cerebras’ Q3 Earnings
Cerebras Systems’ third-quarter 2026 performance is expected to have benefited from robust demand for high-speed AI inference, expanding cloud deployments and growing adoption of its wafer-scale computing technology. Increasing demand for faster token generation across AI coding, agentic workflows and enterprise applications is likely to have supported revenue growth.
The continued ramp-up of Cerebras Systems deployment with OpenAI is expected to be a major growth driver in the to-be-reported quarter. The company’s ability to serve advanced frontier models, including GPT-5.6 Sol, at significantly higher inference speeds strengthens its competitive positioning. Growing usage among existing cloud customers is also likely to have boosted cloud and services revenues. In the second quarter of 2026, core cloud and other services revenues surged 287% year over year to $127.7 million, reflecting strong demand for its inference offerings.
Expanding enterprise adoption is another positive factor. Cerebras Systems secured agreements with Figma, Cognition and Lovable in AI coding, while Block, AlphaSense and GSK adopted its technology for agentic applications. Its engagement with CrowdStrike also highlights emerging opportunities in AI-powered cybersecurity. These customer additions are expected to have supported cloud utilization and broaden the company’s revenue base in the to-be-reported quarter.
However, the company is expected to have suffered from rising infrastructure investments and near-term margin pressure associated with its aggressive capacity expansion. In the second quarter of 2026, core gross margin declined 590 basis points (bps) sequentially to 40.6% as Cerebras Systems temporarily rented systems back from customers to satisfy strong inference demand.
The company expects the third quarter of 2026 to represent the trough, with core gross margin guided to 38-40%, while core operating margin is expected to deteriorate to negative 25-23% from negative 16% in the second quarter of 2026. Continued investments in manufacturing, data centers, research and development and organizational infrastructure are also likely to have weighed on operating profitability. Management projects a core operating margin between negative 25% and negative 23% in the third quarter of 2026 compared with negative 16% in the second quarter.
CBRS Shares Underperform Sector
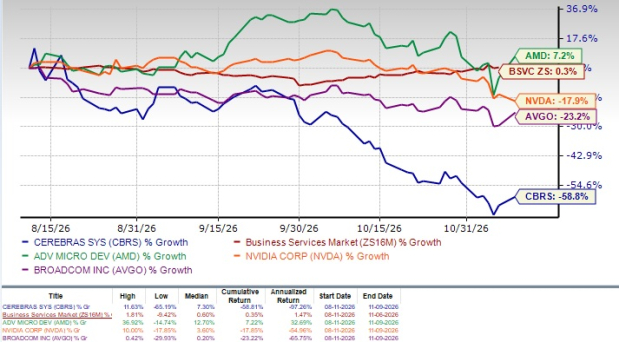
Cerebras shares have plunged 58.8% in the past three months, underperforming the Zacks Business Services sector’s return of 0.3%.
CBRS shares have underperformed its peers, which include NVIDIA NVDA, Advanced Micro Devices AMD and Broadcom AVGO. All three companies are expanding their footprint in the AI space. While Advanced Micro Devices shares have risen 7.2%, NVIDIA and Broadcom shares have plunged 17.9% and 23.2%.
CBRS Stock Performance
Image Source: Zacks Investment Research
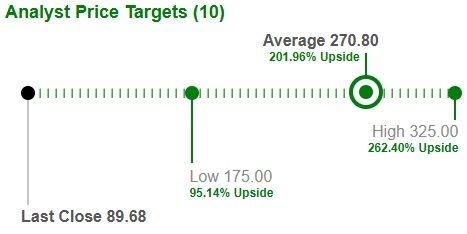
Moreover, Wall Street’s consensus price target implies roughly 201.96% upside from current levels.
Image Source: Zacks Investment Research
However, the Value Score of D suggests a stretched valuation for Cerebras Systems at this moment.
CBRS Rides on Strong AI Demand and Partnerships
Cerebras Systems has strong long-term growth prospects, driven by accelerating demand for high-speed artificial intelligence (AI) inference, expanding cloud infrastructure and strategic partnerships with leading technology companies. The growing adoption of agentic AI, AI-powered coding and real-time enterprise applications is expected to have increased demand for the company's wafer-scale computing solutions in the quarter to be reported.
Strategic collaborations with OpenAI, Amazon Web Services (AWS) and other hyperscalers further strengthen Cerebras Systems’ growth prospects. Its partnership with OpenAI is supporting strong demand for high-speed AI inference, while AWS integration through Amazon Bedrock, expected to become generally available in the first quarter of 2027, should expand enterprise adoption. Growing customer engagements across AI coding, agentic workflows and cybersecurity provide additional opportunities to diversify its revenue streams.
The company is aggressively expanding its data center footprint to capitalize on increasing AI infrastructure investments. The company secured more than 600 megawatts of data center capacity, either operational or under contract for delivery by the end of 2027. Its manufacturing expansion initiatives, supported by partnerships with Flex, Sanmina and TSMC, are expected to increase manufacturing capacity by more than tenfold in 2026. These investments position Cerebras Systems to address growing customer demand and accelerate revenue growth.
Technological advancements, including the planned CS5 launch in the second half of 2027, are expected to have strengthened its competitive positioning. Management anticipates more than tripling core revenues in 2027, with further substantial growth in subsequent years.
Conclusion
Cerebras Systems third-quarter 2026 earnings are likely to reflect strong growth momentum, backed by robust AI inference demand, the ongoing OpenAI deployment ramp, increasing cloud customer usage and strategic collaborations with AWS. The company’s wafer-scale architecture, expanding cloud infrastructure and emerging opportunities in disaggregated inference also bode well for its long-term growth prospects.
However, near-term margin compression, persistent losses, elevated spending, customer concentration and intense competition from companies like Advanced Micro Devices, NVIDIA, and Broadcom remain key concerns.
Cerebras currently has a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Cerebras Systems Inc. (CBRS): Free Stock Analysis Report
Advanced Micro Devices, Inc. (AMD): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Broadcom Inc. (AVGO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).