

CVS Health CVS is entering a more constructive earnings phase as Aetna margins recover, pharmacy execution improves and cash generation strengthens. Those gains give investors a clearer recovery case after a difficult stretch.
The offset is persistent pressure in pharmacy benefit management, medical membership and reimbursement. CVS looks inexpensive against peers, but the investment case still depends on execution through 2027.
CVS Valuation Leaves Room for a Recovery Case
CVS trades at 10.40X forward 12-month earnings, below 16.33X for the Zacks sub-industry and 18.65X for the S&P 500. That discount leaves room for upside if earnings recovery remains on track.
Image Source: Zacks Investment Research
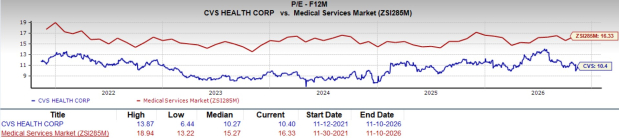
The stock is not unusually cheap versus its own history. Its five-year median is 10.27X, with a range of 6.44X to 13.87X, suggesting current valuation is close to a normal CVS multiple.
Aetna Recovery Strengthens CVS Earnings Momentum
Health Care Benefits adjusted operating income reached $912 million in the third quarter of 2026, up from $314 million a year earlier. The medical benefit ratio improved to 91.3% from 92.8%, driven mainly by better Government business performance.
Management raised the segment's 2026 adjusted operating income outlook to at least $5.4 billion. It also expects further margin improvement in 2027, supported by Medicare Advantage pricing actions and disciplined underwriting.
CVS Pharmacy Execution Adds a Second Profit Driver
Pharmacy & Consumer Wellness adjusted operating income increased 10.6% year over year to $1.64 billion even as revenues declined 2% to $35.50 billion. Core pharmacy strength and Rite Aid asset contributions supported the improvement.
Prescription volume also moved higher, while pharmacy economics improved. Those gains are helping counter regulatory-related drug-price reductions, generic introductions and continued reimbursement pressure, which remain constraints on revenue growth.
PBM Reform Keeps CVS Risk Elevated Into 2027
Health Services remains the main source of uncertainty. CVS expects 2027 adjusted operating income of at least $7 billion, below its 2026 outlook of at least $7.25 billion, reflecting 340B weakness, a less favorable selling season and health plan client membership attrition.
The Cigna Group CI operates Evernorth Health Services, which includes pharmacy benefits, home delivery and specialty pharmacy capabilities. UnitedHealth Group UNH said Optum Rx is moving to a transparent, fee-based pharmacy care model offered to all PBM customers. For CVS, specialty strength and Health Care Delivery improvement must help offset the Caremark reset.
CVS Cash Flow Supports Debt Reduction and Buybacks
Operating cash flow reached $15.32 billion in the first nine months of 2026, while long-term debt fell to $57.22 billion from $60.50 billion at 2025-end. CVS repaid $4.06 billion of long-term debt during the period.
The company also paid $2.58 billion in dividends and achieved its leverage goal ahead of schedule. Management plans to resume share repurchases in the fourth quarter, giving CVS more flexibility as earnings recover.
CVS Signals Still Favor Selective Optimism
CVS offers a credible recovery setup, but the case is not one-sided. Aetna's improving margins, pharmacy profit growth and stronger cash generation support a constructive view, while PBM pressure, reimbursement headwinds and membership declines keep execution risk elevated.
The stock currently carries a Zacks Rank #2 (Buy), along with a VGM Score of A, Value Score of A, Growth Score of A and Momentum Score of B. That combination points to favorable near-term characteristics across value, growth and momentum, while the operating risks argue for selective rather than unconditional optimism.
You can see the complete list of today's Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
CVS Health Corporation (CVS): Free Stock Analysis Report
UnitedHealth Group Incorporated (UNH): Free Stock Analysis Report
Cigna Group (CI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).