

Palomar Holdings, Inc. PLMR appears well positioned to sustain strong premium growth across its specialty insurance businesses, supported by expanding distribution partnerships, new business generation, strong policy retention and a diversified product portfolio. Its focus on specialty markets, where underwriting expertise and tailored risk solutions provide competitive advantages, should continue to create opportunities for profitable expansion.
In the third quarter of 2026, PLMR reported a 28.4% year-over-year increase in gross written premiums to a record $767 million. Growth was primarily driven by higher policy volumes across most business lines, particularly Crop and Surety & Credit. New business generated through existing partners, strong retention of existing policies, an expanded distribution footprint and new partnerships also supported premium expansion. The acquisition of PCSC contributed $26.7 million to quarterly gross written premiums.
The growth trend was broad-based. For the first nine months of 2026, gross written premiums increased 32%, with Crop and Casualty leading expansion. Gross written premiums in the PSIC and PESIC subsidiaries rose 33.1% and 24.2%, respectively. Net written premiums benefited from higher gross premiums and a lower proportion of premiums ceded to reinsurers.
PLMR's diversified specialty portfolio, including Earthquake, Inland Marine and Property, Casualty, Surety & Credit and Crop insurance, provides multiple avenues for expansion. Its ability to leverage existing distribution relationships, establish new partnerships and expand its market presence should support further policy growth. The acquisition of PCSC also adds to its Surety & Credit business and broadens its growth opportunities. Moreover, the third-quarter combined ratio of 80.8% indicates that strong premium expansion was accompanied by favorable underwriting profitability.
PLMR appears well positioned to sustain strong premium growth across its specialty insurance businesses, supported by distribution expansion, diversified offerings and strong policy retention.
What About Other Insurers?
W. R. Berkley Corporation WRB provides a good example of how an insurer can balance premium growth with underwriting discipline amid moderating pricing conditions. Despite easing rate momentum, WRB continues to prioritize rate adequacy, selective risk appetite and favorable policy terms rather than pursuing volume at the expense of profitability. Its diversified portfolio of 60 specialty insurance businesses also provides flexibility to capitalize on attractive opportunities across different product lines and markets. Going forward, WRB's ability to sustain premium growth will depend on disciplined risk selection, adequate pricing and its capacity to identify attractive specialty-market opportunities. Its focus on profitable business expansion rather than premium volume alone should help support underwriting resilience as competition intensifies.
Cincinnati Financial Corporation CINF offers a relevant example of balancing premium growth with underwriting discipline amid moderating pricing conditions. Premium expansion reflects renewal price increases, premium growth initiatives and higher insured exposures. Average renewal price increases across most business lines were lower than in the second quarter, although management considered pricing levels healthy. Commercial and Excess and Surplus Lines recorded low-single-digit rate increases, while Personal Lines benefited from high-single-digit increases in homeowners insurance and mid-single-digit increases in personal auto. Underwriting discipline remained central to the company's strategy, with management emphasizing policy-level risk segmentation rather than pursuing new business at the expense of profitability.
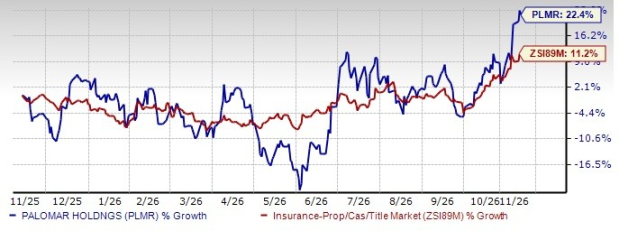
PLMR’s Price Performance
Shares of PLMR have gained 22.4% in the past year, outperforming the industry.
Image Source: Zacks Investment Research
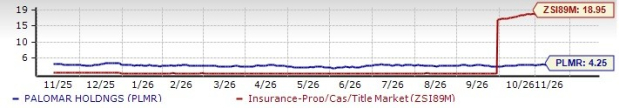
PLMR’s Undervaluation
The stock is undervalued compared with its industry. Its forward price-to-book value of 4.25X is lower than the industry average of 18.95X.
Image Source: Zacks Investment Research
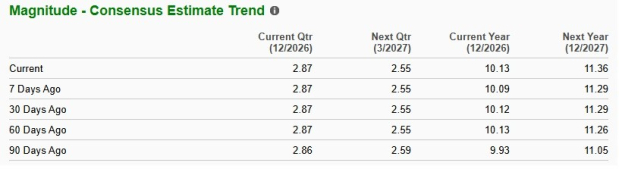
Estimate Movement for PLMR
The Zacks Consensus Estimate for full-year 2026 and 2027 EPS has moved up 0.09% and 0.6%, respectively, in the past 30 days.
The consensus estimate for PLMR’s 2026 and 2027 EPS and revenues indicates a year-over-year increase.
Image Source: Zacks Investment Research
PLMR stock currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Palomar Holdings, Inc. (PLMR): Free Stock Analysis Report
W.R. Berkley Corporation (WRB): Free Stock Analysis Report
Cincinnati Financial Corporation (CINF): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).