

Shares of NIKE Inc. NKE have endured a steep sell-off year to date, reflecting investor concerns surrounding sluggish demand, competitive pressures and the pace of the company’s ongoing business turnaround. The steep correction has significantly reset expectations for the sportswear giant and brought its valuation into focus. While near-term headwinds continue to cloud the outlook, NIKE’s strong brand equity, strategic initiatives and efforts to reignite product innovation could support a recovery over time.
Shares of NIKE have declined 39.8% in the year-to-date period, underperforming the Shoes and Retail Apparel industry’s 33.8% fall, the broader sector’s 6.9% loss and the S&P 500 index’s 8.8% growth.
NIKE has also lagged its competitor adidas AG ADDYY, which has dropped 0.2% in the year-to-date period. NKE’s performance is notably weaker than Wolverine World Wide WWW and Steven Madden SHOO, which posted gains of 20.9% and 2.6%, respectively, in the same period.
NIKE’s YTD Price Performance
Image Source: Zacks Investment Research
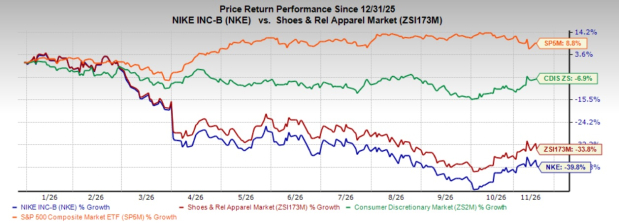
At the current share price of $38.32, NKE trades 19.9% above its 52-week low mark of $31.9. Meanwhile, NKE stock’s price stands 45% below its 52-week high of $69.14.
What's Keeping NIKE’s Shares Under Pressure?
NIKE's recovery remains uneven as weakness in its Sportswear business continues to overshadow gains in performance categories. Sportswear, which accounted for just under half of first-quarter fiscal 2027 revenues, declined in the low double digits. The planned reduction in Dunk revenues by nearly 50% created an approximately $200 million headwind, while disappointing sell-through of older footwear styles affected future wholesale orders. Persistent weakness in lifestyle demand remains a concern for revenue recovery.
Jordan Brand is another source of pressure, with fiscal first-quarter revenues declining in the mid-teens. Management acknowledged that the excessive supply of iconic retro footwear has weakened product scarcity and marketplace positioning. Consequently, NIKE plans to reduce the volume and frequency of selected Jordan Retro launches, particularly affecting North America. Although these actions aim to restore brand exclusivity and improve full-price sales over time, they could further constrain near-term revenues.
Greater China continues to face significant challenges, with fiscal first-quarter revenues declining 26%. NIKE is restructuring its digital distribution network, exiting unprofitable and heavily discounted channels, and improving physical retail experiences. However, these initiatives are expected to weigh on both revenues and profitability. Management indicated that China's revenue performance could deteriorate further during the remainder of fiscal 2027, while the marketplace reset is expected to take multiple seasons.
NIKE's cautious financial outlook further underscores the challenges ahead. Management expects fiscal 2027 revenues to decline in the high-single-digit range, with EBIT falling faster than sales due to margin pressure, higher input costs and fixed-cost deleverage. Adjusted earnings per share are projected between $1.15 and $1.35, excluding approximately 15 cents of Pace-related costs. The company also expects restructuring actions to pressure revenues into fiscal 2028, suggesting that a meaningful recovery may take longer than anticipated.
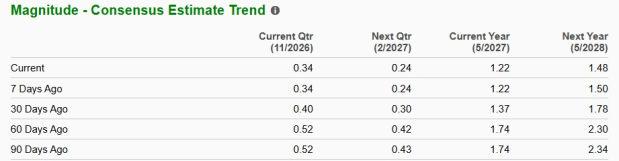
NKE’s Estimate Revision Trend
The Zacks Consensus Estimate for NIKE’s fiscal 2027 earnings per share has shown a downtrend, declining 10.9% in the past 30 days. The consensus mark for fiscal 2028 also moved down 20.3% in the last 30 days.
For fiscal 2027, the Zacks Consensus Estimate for NKE’s EPS implies 22.8% year-over-year growth, while the estimate for sales indicates an 8% decline. The consensus mark for fiscal 2028 sales implies a 0.11% decline, whereas the same for earnings indicates 21.4% year-over-year growth.
Image Source: Zacks Investment Research
NIKE’s Valuation Picture
While NIKE continues to benefit from its strong brand equity and strategic efforts to restore sustainable, profitable growth, its current valuation calls for caution. The stock trades at a forward 12-month price-to-earnings (P/E) multiple of 28.56X, higher than the Zacks Shoes and Retail Apparel industry average of 23.05X and the S&P 500’s 18.57X. This premium suggests that the market is already factoring in a substantial recovery in the company’s operating performance.
Image Source: Zacks Investment Research
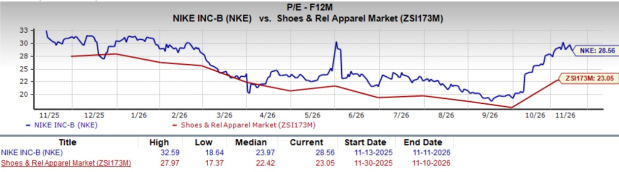
NIKE also trades at a significant premium to its industry peers. adidas, Steven Madden and Wolverine World currently command forward 12-month P/E multiples of 15.24X, 16.29X and 12.04X, respectively, considerably below NKE’s valuation. Such a valuation gap appears difficult to justify amid the stock’s sharp decline and the continued challenges surrounding its business turnaround.
The premium valuation underscores investor confidence in NIKE’s brand strength, innovation pipeline and long-term earnings recovery prospects. Nevertheless, prolonged operational headwinds or persistent weakness in discretionary consumer spending could limit the stock’s upside potential. Against this backdrop, sustained improvements in sales trends, profitability and operational execution will be essential for NIKE to justify its elevated valuation relative to the industry and peers.
Should Investors Buy NKE Stock Now?
NIKE's steep year-to-date decline may attract investors seeking exposure to a globally recognized sportswear brand at a substantially lower share price. The company's growing Performance portfolio, expanding Running business, product innovation and operational restructuring initiatives offer potential catalysts for long-term recovery.
However, persistent weakness in Sportswear and Jordan Brand, deteriorating conditions in Greater China and management's expectations for declining fiscal 2027 revenues indicate that substantial challenges remain. The anticipated continuation of revenue pressure into fiscal 2028 further limits visibility into the timing of a sustainable turnaround.
Moreover, downward earnings estimate revisions and a premium valuation relative to industry peers suggest that the stock may not yet offer a compelling risk-reward proposition. While NIKE's strategic initiatives could gradually strengthen its competitive positioning and profitability, investors may prefer to avoid this Zacks Rank #5 (Strong Sell) stock until clearer evidence of improving demand, healthier margins and consistent revenue growth emerges.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
NIKE, Inc. (NKE): Free Stock Analysis Report
Wolverine World Wide, Inc. (WWW): Free Stock Analysis Report
Adidas AG (ADDYY): Free Stock Analysis Report
Steven Madden, Ltd. (SHOO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).