

Corteva, Inc. CTVA reported third-quarter 2026 results, wherein both the top and bottom lines missed the Zacks Consensus Estimate. Earnings and revenues declined year over year, reflecting weaker market conditions in Brazil, competitive pricing pressure and lower volumes. Strong demand for differentiated products and productivity initiatives partly offset these headwinds.
CTVA reported adjusted earnings of 6 cents per share, missing the Zacks Consensus Estimate of 9 cents and declining 57.1% from 14 cents in the year-ago quarter.
Revenues of $1,591 million decreased 9% year over year and missed the Zacks Consensus Estimate of $1,769 million.
Corteva, Inc. Price, Consensus and EPS Surprise
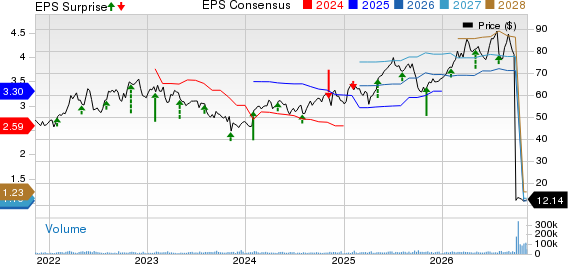
Corteva, Inc. price-consensus-eps-surprise-chart | Corteva, Inc. Quote
Decoding CTVA's Q3 Sales Performance
In the third quarter of 2026, organic sales declined 9%, reflecting a 7% decrease in pricing and a 2% drop in volumes. Competitive pricing pressure on mature crop protection molecules in Brazil and acetochlor in the United States weighed on performance. Volume growth across most regions was offset by challenging market conditions in Brazil.
North America reported net sales up 7% year over year to $574 million, beating the Zacks Consensus Estimate of $501 million. Organic sales increased 7%, supported by 19% volume growth from new products and early demand, partly offset by a 12% pricing decline. EMEA sales rose 12% to $239 million, with organic growth of 14%, driven by strong demand for differentiated products.
Latin America sales declined 28% to $570 million, missing the Zacks Consensus Estimate of $848 million, while organic sales fell 31%. Volumes decreased 24% amid elevated channel inventories, farmer liquidity constraints and high interest rates. Pricing declined 7% due to competitive pressure on mature molecules. Asia Pacific sales increased 3% to $208 million, supported by 7% volume growth.
Corteva Faces Pressure Across Product Lines
Herbicide sales decreased 10% year over year to $731 million, missing the Zacks Consensus Estimate of $854 million, reflecting a 10% pricing decline and a 1% volume reduction. Partly offset by favorable currency. Organic sales fell 11%, primarily due to lower pricing.
Insecticide revenues declined 3% to $396 million, missing the Zacks Consensus Estimate of $ 454 million, primarily due to weaker pricing. Fungicide sales dropped 23% to $171 million, missing the Zacks Consensus Estimate of $231 million. The decline was due to a 16% volume decline and a 9% reduction in pricing, partly offset by favorable currency movements.
Biologicals sales decreased 22% to $115 million, reflecting a 23% volume decline and a 1% pricing reduction, partly offset by favorable currency movements. However, revenues from other products increased 18% to $178 million, supported by an 18% improvement in volumes. The metric missed the Zacks Consensus Estimate of $158 million.
CTVA's Adjusted Profitability and Margin Trends
Adjusted pro forma operating EBITDA declined 17% to $222 million from $268 million in the year-ago quarter. The corresponding adjusted margin contracted 140 basis points to 14%, reflecting lower sales and persistent pricing pressure, particularly in Latin America.
Adjusted pro forma operating earnings decreased to $38 million from $94 million in the prior-year quarter. The decline reflected weaker operating performance despite continued productivity initiatives.
For the first nine months of 2026, adjusted pro forma operating EBITDA increased slightly to $943 million from $937 million. The adjusted EBITDA margin expanded 30 basis points to 17.6%, while adjusted operating earnings increased 49% to 76 cents per share from 51 cents.
Financial Updates for Corteva
Corteva ended September 2026 with pro forma cash and cash equivalents of $1.80 billion, short-term borrowings of $60 million and long-term debt of $944 million. Pro forma equity attributable to New Corteva shareholders stood at $11.88 billion.
Management continued to emphasize productivity improvements and disciplined execution amid challenging Crop Protection market conditions. The company's restructuring initiatives are aimed at optimizing its Crop Protection manufacturing network and external partnerships, with substantial completion expected in 2028.
CTVA Updates 2026 Outlook Amid Brazil Headwinds
Corteva updated its full-year 2026 outlook, reflecting weaker-than-anticipated Crop Protection market conditions, particularly in Brazil. Elevated financing costs, constrained farmer liquidity, delayed purchasing and intensifying pricing competition have created additional challenges.
The company now expects adjusted pro forma operating EBITDA in the range of $1.1-$1.125 billion and adjusted pro forma operating earnings of 76-80 cents per share for 2026.
Management continues to emphasize differentiated innovation, productivity improvements and disciplined execution. Demand for new products remains strong, while resilient performance outside Latin America provides some support amid persistent market challenges.
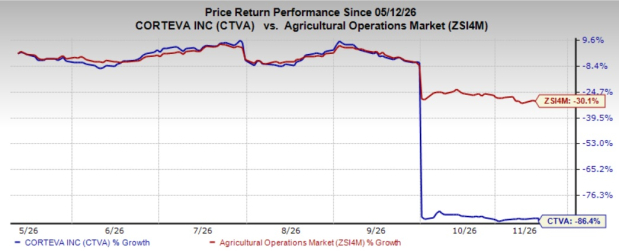
In the past six months, this Zacks Rank #5 (Strong Sell) company’s shares have plunged 86.4% compared with the industry’s 30.1% decline.
Image Source: Zacks Investment Research
Stocks to Consider
Some better-ranked stocks have been discussed below:
BJ's Wholesale Club Holdings, Inc. BJ, together with its subsidiaries, operates membership warehouse clubs on the eastern half of the United States. At present, BJ carries a Zacks Rank of 2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The Zacks Consensus Estimate for BJ’s current fiscal-year sales and earnings suggests growth of 11.7% and 6.8%, respectively, from the year-ago reported figures. BJ reported a trailing four-quarter average earnings surprise of 4.8%.
Ryohin Keikaku Co., Ltd. RYKKY engages in the retail of household goods and food items in Japan and internationally. RYKKY currently carries a Zacks Rank #2.
The Zacks Consensus Estimate for RYKKY's current fiscal-year sales implies growth of 3.9%, and the same for earnings implies a decline of 2.1% from the year-ago actuals.
Mission Produce, Inc. AVO engages in the sourcing, farming, packaging, marketing, and distribution of avocados, mangoes, and blueberries to food retailers, wholesalers, and foodservice customers in the United States and internationally. AVO currently carries a Zacks Rank #2.
The Zacks Consensus Estimate for Mission Produce's current fiscal-year sales implies growth of 3.6%, and the same for earnings implies a decline of 17.7% from the year-ago actuals. AVO delivered a trailing four-quarter earnings surprise of 17.6%, on average.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Corteva, Inc. (CTVA): Free Stock Analysis Report
BJ's Wholesale Club Holdings, Inc. (BJ): Free Stock Analysis Report
Mission Produce, Inc. (AVO): Free Stock Analysis Report
Ryohin Keikaku Co. Ltd. (RYKKY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).