

Nebius Group N.V. NBIS delivered impressive third-quarter 2026 results, with revenues surging 571% year over year to $980.8 million, up 68% sequentially. The growth was primarily driven by capacity additions over the past 12 months and strong demand for AI infrastructure. Nebius AI Cloud revenues jumped 643% to $973.8 million, accounting for approximately 99% of total revenues. However, sustaining this momentum will depend on the company's ability to expand capacity and execute its ambitious growth plans.
The company's expanding customer base and favorable contract terms support its growth prospects. Since the beginning of the third quarter, customers have committed more than $12 billion in contract value, including multibillion-dollar agreements. Nebius also secured multiyear agreements with enterprise AI leaders, including Databricks, Datadog and Snowflake. Notably, pricing for third-quarter agreements exceeded $25 million per megawatt compared with $20 million-$25 million in the preceding quarter, reflecting robust demand.
Improving profitability further strengthens its growth outlook. Group adjusted EBITDA reached $465.8 million against a loss of $5.2 million a year earlier. Adjusted EBITDA margin expanded to 47.5% from 40.6% sequentially. Customer prepayments now cover more than 100% of capital expenditures associated with newly contracted capacity, improving the company's funding flexibility.
Nebius expects 2026 revenues of $3 billion-$3.2 billion, narrowing its previous guidance of $3 billion-$3.4 billion due to delays at certain third-party data center sites. Capital expenditures are projected to be approximately $27 billion, while adjusted EBITDA margin guidance remains around 40%.
For 2027, management anticipates revenues of $12 billion-$13 billion, representing approximately fourfold growth, supported by additional computing capacity. Capital expenditures are expected to reach $40 billion-$45 billion, with pretax breakeven targeted for the fourth quarter.
Despite strong demand, infrastructure deployment delays and substantial capital requirements remain key challenges. Nevertheless, expanding capacity, higher contract pricing and growing customer commitments position Nebius for continued growth, provided execution remains on track.
Taking a Look at NBIS’ Competitors
CoreWeave CRWV reported impressive third-quarter 2026 revenue growth of 168% year over year to $3.66 billion, surpassing the Zacks Consensus Estimate by 4.84%. Strong AI infrastructure demand, favorable pricing and accelerated capacity deployments drove growth. Revenue backlog surged 138% year over year to $132.5 billion, providing significant revenue visibility. Demand remained robust, with qualified demand exceeding available capacity by 10 times through 2027. The company expanded its customer base and increased infrastructure capacity to support future growth. Encouraged by strong demand trends, CoreWeave raised its full-year 2026 revenue guidance to $13 billion-$13.3 billion and year-end annualized revenue run-rate outlook to $20 billion-$21 billion.
Microsoft MSFT is benefiting from accelerating cloud demand and expanding AI monetization. First-quarter fiscal 2027 revenues increased 19% year over year to $92.3 billion, driven by 48% Azure revenue growth to $33.2 billion. Microsoft Cloud revenues surged 30% to $63.9 billion, while Foundry revenues more than tripled. Commercial remaining performance obligations jumped 73% to $677 billion, providing strong revenue visibility. For the second quarter, Microsoft expects revenues of $96-$97.1 billion, representing 18-19% growth, with Azure projected to grow 49-50% in constant currency. However, weakness in Windows OEM and devices and capacity constraints remain concerns.
NBIS Price Performance, Valuation and Estimates
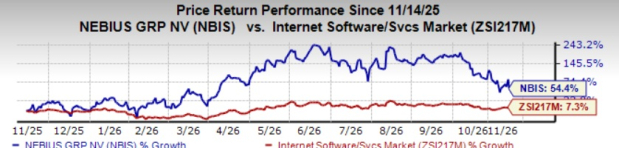
Shares of Nebius have gained 54.4% in the past year compared with the Internet – Software and Services industry’s growth of 7.3%.
Image Source: Zacks Investment Research
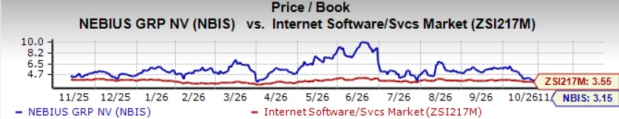
In terms of price/book, NBIS’ shares are trading at 3.15X, below the Internet Software Services industry’s 3.55X.
Image Source: Zacks Investment Research
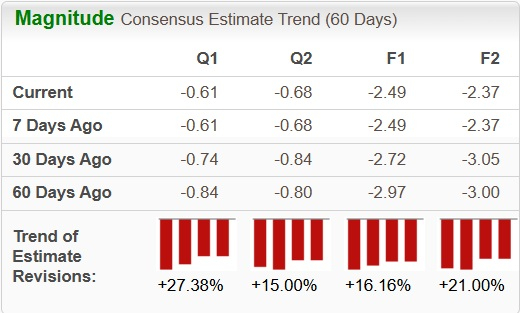
The Zacks Consensus Estimate for NBIS’ earnings for 2026 has been revised significantly upward over the past 60 days.
Image Source: Zacks Investment Research
NBIS currently carries a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Nebius Group N.V. (NBIS): Free Stock Analysis Report
Microsoft Corporation (MSFT): Free Stock Analysis Report
CoreWeave Inc. (CRWV): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).