

Coeur Mining CDE shares have fallen 37.2% in the past three months, slightly worse than the 35.8% decline for its Zacks sub-industry. The slide has put the enlarged miner’s execution challenges under greater scrutiny.
The portfolio now has more production capacity and cash-flow sources, but slower Canadian ramp-ups, delayed silver recoveries at Rochester and weaker earnings-estimate momentum keep the near-term setup difficult.
Coeur Mining, Inc. Price and Consensus
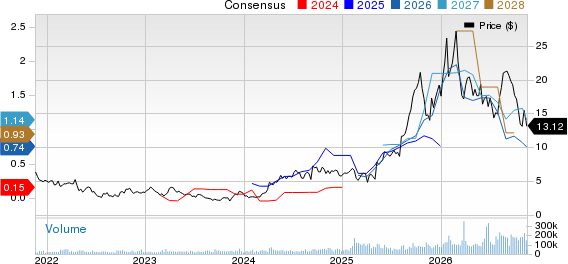
Coeur Mining, Inc. price-consensus-chart | Coeur Mining, Inc. Quote
Coeur’s Canadian Ramp-Ups Remain a Key Risk
The New Gold acquisition added New Afton and Rainy River, but Coeur reduced 2026 gold guidance for both mines after slower assumed underground ramp-ups. New Afton’s nine-month target fell to 50,000-60,000 ounces from 60,000-80,000, while Rainy River’s was cut to 190,000-230,000 ounces from 230,000-275,000.
Third-quarter conveyor downtime interrupted ore delivery at New Afton. Heavy rainfall at Rainy River increased reliance on lower-grade stockpiles, while the mine still needs additional mining horizons to sustain its targeted underground rate into 2027.
CDE Faces Recovery Delays at Rochester
Rochester’s expansion has materially increased ore placement, with 30.3 million tons placed in 2025 compared with 10.3 million in 2023. Third-quarter 2026 crushing reached a record 6.8 million tons.
The bottleneck is recovery. Silver production fell to about 1.23 million ounces from 1.64 million a year earlier as recovery from newly placed ore remained slower than expected. Coeur produced 3.85 million silver ounces through September against full-year guidance of 6.4-7.8 million ounces, leaving a sizable fourth-quarter requirement.
Coeur’s Costs and Grades Add Margin Pressure
Lower grades are adding pressure at legacy operations. Palmarejo’s third-quarter gold grade fell to 1.22 grams per ton from 1.85 a year earlier, while adjusted silver costs applicable to sales rose to $28.71 per ounce from $16.44.
Kensington also processed lower-grade ore than a year earlier. Management expects full-year unit costs near the upper end of guidance and continues to cite labor, consumables and contractor inflation, limiting the margin benefit from higher processing rates.
CDE Still Has Cash Flow and Production Upside
The balance sheet provides an important offset. By September, cash exceeded total debt by $471.1 million. Las Chispas generated $72.6 million of third-quarter free cash flow, while management expects 2026 free cash flow to exceed $1.3 billion at current metal prices.
Industry peers show that operating execution remains the key differentiator. Agnico Eagle Mines Limited AEM said its third-quarter performance kept it on track to achieve 2026 production and cost guidance. Pan American Silver Corp. PAAS generated $377 million of attributable free cash flow in the third quarter, although it also revised its 2026 gold-production outlook lower.
Coeur’s Signals Still Favor Caution
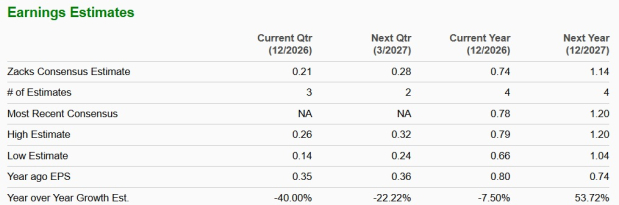
The stock’s decline does not, by itself, make the risk-reward profile favorable. Coeur’s current-year EPS estimate has fallen 15.6% over the past four weeks, while the company still needs better Canadian mining rates, improved legacy-mine grades and faster Rochester recoveries to support expected production gains.
The Zacks Consensus Estimate for 2026 earnings is currently pegged at 74 cents and indicates a year-over-year decline of 7.5%.
Image Source: Zacks Investment Research
CDE currently carries a Zacks Rank #4 (Sell), along with a VGM Score of C, Growth Score of B, Value Score of C and Momentum Score of F. The Growth Score points to relatively favorable growth characteristics, but Style Scores complement the Zacks Rank rather than override it. The weak Momentum Score and unfavorable Zacks Rank support a cautious near-term view.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Coeur Mining, Inc. (CDE): Free Stock Analysis Report
Agnico Eagle Mines Limited (AEM): Free Stock Analysis Report
Pan American Silver Corp. (PAAS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).