

Booking Holdings BKNG is scheduled to report its third-quarter 2026 results after market close on Nov. 4.
For the third quarter of 2026, the company expects total revenues to grow 4% to 6% and constant-currency revenues to grow 5% to 7% year over year.
The Zacks Consensus Estimate for revenues is pegged at $9.56 billion, suggesting growth of 6.17% from the year-ago quarter’s reported figure.
The consensus mark for earnings is pegged at $4.48 per share, indicating 12.56% growth from the year-ago quarter’s reported figure. The estimate has remained unchanged over the past 30 days but increased by 3 cents over the past 60 days.
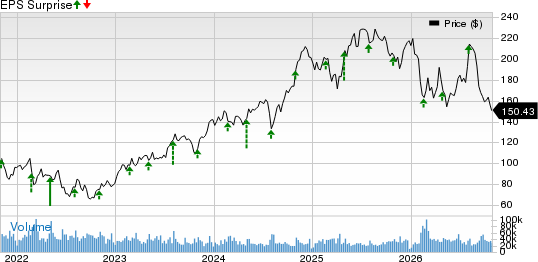
Booking Holdings Inc. Price and EPS Surprise
Booking Holdings Inc. price-eps-surprise | Booking Holdings Inc. Quote
BKNG’s earnings beat estimates in each of the trailing four quarters, with an average beat of 3.02%.
Let’s see how things have shaped up for the upcoming announcement.
Factors Likely to Shape BKNG’s Q3 Results
Booking Holdings is likely to have faced headwinds from the Middle East conflict in the to-be-reported quarter. Elevated airfares, reduced airline capacity on certain routes and softer long-haul international travel demand are expected to have affected travel bookings. In the second quarter, international room nights increased only slightly, compared with high-single-digit domestic growth. With these disruptions expected to persist through the third quarter, BKNG’s room-night growth and flight-related bookings are likely to have suffered, despite resilient domestic travel demand.
Adverse foreign currency movements are expected to have weighed on BKNG’s third-quarter performance. Based on management's exchange-rate assumptions, currency fluctuations were projected to reduce year-over-year reported growth in gross bookings, revenues and adjusted EBITDA by approximately one percentage point. Consequently, anticipated constant-currency growth of 5-7% in gross bookings and revenues translates into reported growth guidance of 4-6%. This currency headwind is likely to have constrained reported revenue and adjusted EBITDA growth in the quarter under review, despite relatively stable underlying travel demand.
Higher customer acquisition costs are likely to have pressured Booking Holdings’ profitability in the third quarter. The company anticipates declining organic search traffic in the short to medium term, potentially increasing its dependence on paid marketing channels. In the second quarter, marketing expenses increased 11% year over year, outpacing gross bookings growth of 9%. Marketing expenses represented 4.7% of gross bookings, compared with 4.6% a year earlier. Continued investments in paid marketing, changing traffic mix and competitive promotional activities are likely to have constrained marketing efficiency and margin expansion in the to-be-reported quarter.
However, expanding adoption of Booking.com's Connected Trip strategy and growing engagement among Genius loyalty members are likely to have strengthened BKNG's performance in the quarter under review. Connected Trip transactions increased in the low double digits in the second quarter, more than twice Booking.com's overall transaction growth. Meanwhile, Level 2 and Level 3 Genius members accounted for a high-50% share of room nights and more than 30% of its active customer base. Stronger repeat bookings, cross-selling opportunities and higher direct-booking engagement are expected to have supported transaction growth and customer retention.
What Our Model Says for BKNG Stock
Our proven model does not conclusively predict an earnings beat for Booking Holdings this time. Per the Zacks model, the combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. However, this is not the case here, as you can see below.
Booking Holdings currently has an Earnings ESP of +0.88% and a Zacks Rank #4 (Sell). You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Stocks to Consider
Here are some companies worth considering, as our model shows that these have the right combination of elements to beat earnings in their upcoming releases:
FIGS, Inc. FIGS currently has an Earnings ESP of +5.00% and carries a Zacks Rank #2. FIGS’ shares have surged 90.8% year to date. FIGS is set to report its third-quarter 2026 results on Nov. 5. You can see the complete list of today’s Zacks #1 Rank stocks here.
Sweetgreen SG presently has an Earnings ESP of +4.26% and a Zacks Rank #2. SG’s shares have jumped 68.6% year to date. SG is set to report its third-quarter 2026 results on Nov. 5.
Marriott International MAR presently has an Earnings ESP of +1.56% and a Zacks Rank #2. MAR’s shares have gained 28.7% year to date. MAR is set to report its third-quarter 2026 results on Nov. 2.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Booking Holdings Inc. (BKNG): Free Stock Analysis Report
Marriott International, Inc. (MAR): Free Stock Analysis Report
Sweetgreen, Inc. (SG): Free Stock Analysis Report
FIGS, Inc. (FIGS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).