

Apple (AAPL) is giving investors another reason to reassess its artificial intelligence (AI) strategy as the company reportedly explores building its own enterprise AI servers. According to The Information, Apple is developing a server designed around its future M8 Ultra chips, with NVIDIA's (NVDA) NVLink Fusion technology potentially used to connect the processors. The project could mark Apple’s return to the enterprise server market after discontinuing its Xserve line in 2011.
The reported move would represent a significant expansion of Apple’s in-house silicon strategy beyond iPhones, Macs, and other consumer devices. Unlike AI systems focused primarily on training large models, the proposed servers are reportedly intended for AI inference workloads, potentially supporting developers, businesses, and government customers. However, the project remains in the development stage, is not expected to reach the market until 2029, and could still be changed or canceled.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The development comes as Apple continues to build out its AI capabilities while relying on a mix of proprietary technology and external infrastructure. If everything goes right, the reported AI-server initiative could add another dimension to the stock’s long-term growth story.
About Apple Stock
Apple, based in California, stands as a forward-looking company and a worldwide leader in hardware, software, and services. Its portfolio spans iconic devices like the iPhone, iPad, Mac, and Apple Watch, alongside widely used platforms such as the App Store, iCloud, Apple Music, and Apple TV+. The company currently boasts a market cap of $4.9 trillion and a Magnificent Seven status.
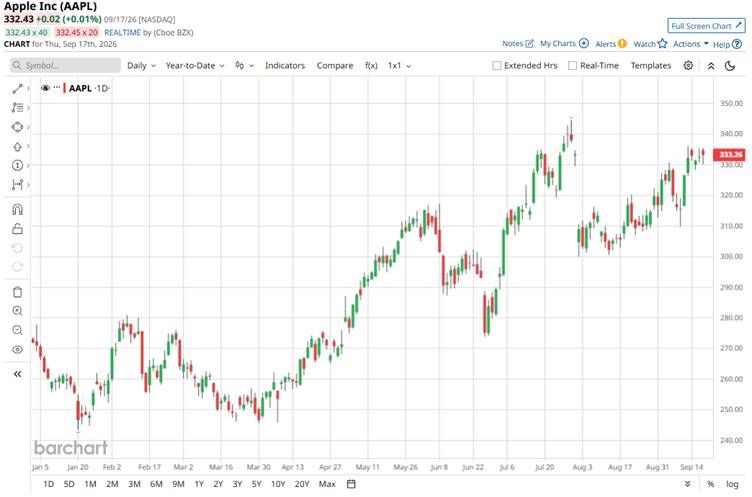
Apple stock has maintained strong momentum in 2026, with shares up about 21.7% year-to-date (YTD) and 38.5% over the past 52 weeks, significantly outperforming the broader market. AAPL closed at $332.41 on Sept. 16, just about 4% below its 52-week high of $344.57 reached in late July.
The stock’s recent strength has been supported by several catalysts, including investor optimism surrounding Apple’s latest product cycle and its growing artificial intelligence ambitions. Investors responded positively to the company’s new hardware lineup, including the iPhone Duo and iPhone 18 Pro models.
More recently, Apple has received another potential catalyst from reports that it is developing an AI server using its own M8 Ultra chips, potentially incorporating NVIDIA’s NVLink Fusion technology. While the reported server project is still in development, it signals Apple’s broader push to expand its proprietary silicon and AI capabilities beyond consumer devices.
With AAPL trading close to its 52-week high, it will be worth watching whether the company’s new product cycle, AI initiatives, and expanding infrastructure ambitions can provide additional catalysts for the stock after its strong run this year.
The stock trades at a premium at 38.09 times forward earnings, compared to the sector median and its historical average.
 www.barchart.com
Taking a Closer Look at Recent Financials
Apple reported fiscal third-quarter 2026 (ended June 27) results on July 30, delivering another quarter that exceeded Wall Street’s expectations. Revenue climbed 16.4% year-over-year (YOY) to $109.4 billion, while earnings per share (EPS) increased 29% to $2.02 from $1.57 a year earlier. Net income rose 27.1% to $29.8 billion, and gross margin expanded to 50.1%, benefiting partly from U.S. tariff refunds.
The iPhone remained the primary growth engine, with revenue surging 21.7% YOY to $54.3 billion, marking Apple’s strongest-ever June-quarter iPhone sales. Mac revenue jumped 28.7% to $10.4 billion, fueled by strong demand for the MacBook Neo and MacBook Pro, while iPad revenue declined 5.9% to $6.2 billion.
Apple’s Services business remained a focus in fiscal Q3 2026, with revenue rising 12.1% YOY to $30.7 billion, which fell short of expectations, disappointing investors. Management attributed the miss primarily to weaker mobile gaming spending, which pressured App Store revenue, as well as changes to the App Store business model in certain countries. It was also the segment’s first sequential decline since 2022.
CFO Kevan Parekh also highlighted the ongoing impact of the U.S. court ruling in the Epic Games case, which allows developers to direct users to external payment options, reducing Apple’s App Store commissions. In Europe, regulatory changes requiring Apple to support alternative app stores created additional headwinds. While the Services segment continued to grow, its slower pace raised concerns that Apple’s highest-margin business could face increasing regulatory and competitive pressure.
Additionally, revenue from Greater China rose 22.4% YOY to $18.8 billion, reflecting continued strength in the region despite narrowly missing consensus estimates. Furthermore, Apple forecast September-quarter revenue growth of 9% to 11%, and mid-teens iPhone revenue growth.
In addition, the consensus estimate of $8.74 for fiscal 2026 indicates an increase of 17.2% YOY, before improving by around 9% annually to $9.53 in fiscal 2027.
What Do Analysts Expect for Apple Stock?
This month, Morgan Stanley analyst Erik Woodring reiterated an “Overweight” rating and a $360 price target, citing Apple’s latest product event as a sign of stronger innovation and above-trend growth into fiscal year 2027.
Also, BofA Securities reiterated its “Buy” rating on Apple on Sept. 10, but lowered its price target to $370 from $380 following the company’s latest product event. Some analysts, though, are taking a more cautious stance. UBS maintained its “Neutral” rating and $296 price target on Apple on Sept. 10.
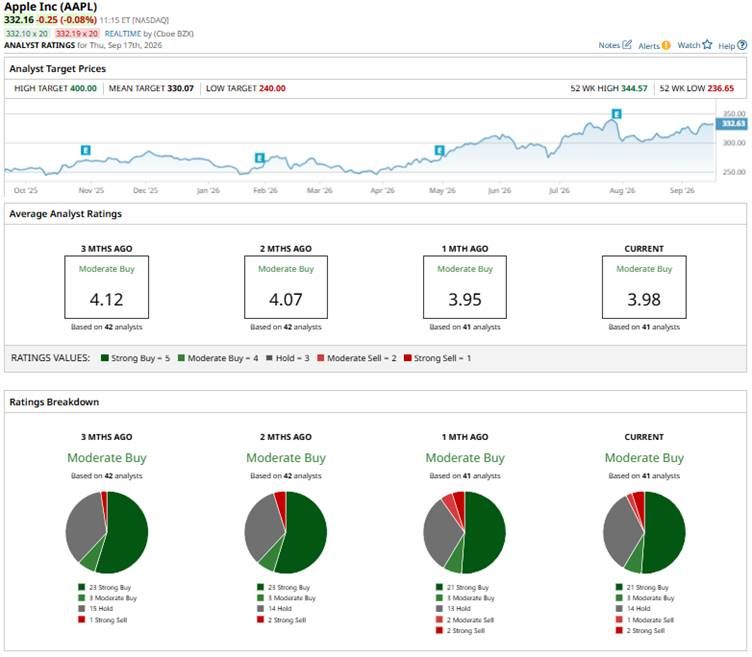
Overall, Apple stock has a consensus “Moderate Buy” rating. Out of 41 analysts covering the tech giant, 21 recommend a “Strong Buy,” three give a “Moderate Buy,” 14 analysts stay cautious with a “Hold” rating, one offers a “Moderate Sell,” and two advise a “Strong Sell.”
While the stock is trading above the average analyst price target of $330.07, the Street-high target price of $400 suggests the stock can still surge by 20.3%.
 www.barchart.com
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
How to Play AAPL Stock Amid Reports Apple Is Building Its Own AI Server Meta’s New AI Agent Could Be the Missing Piece for META Stock Dear Meta Platforms Stock Fans, Mark Your Calendars for Sept. 23 Here’s Another Little-Known Firm Jensen Huang’s Nvidia Is Quietly Backing