

CoreWeave (CRWV) once again caught the spotlight amid tech’s AI infrastructure race. This time, it is planting a flag in one of the world's fastest-growing AI markets. The company just announced a 240-megawatt data center project in Navi Mumbai, India, with AdaniConneX. This is a big deal. India's data center capacity is expected to explode from 2.2 gigawatts in 2025 to 12 gigawatts by 2030. CoreWeave wants a piece of that action.
The shift expands its operations outside of North America and Europe. It's also providing the company a first-mover advantage in a part of the world that is thirsty for compute power for AI applications.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Still, there are some risks. The project will not be operational until 2028. Requires massive investments of capital. And CoreWeave is already heavily indebted. Is this growth a good long-term investment or a fresh costly gamble? Let's try to find out the answer to this question in this article.
CoreWeave Is Riding a $104 Billion AI Backlog
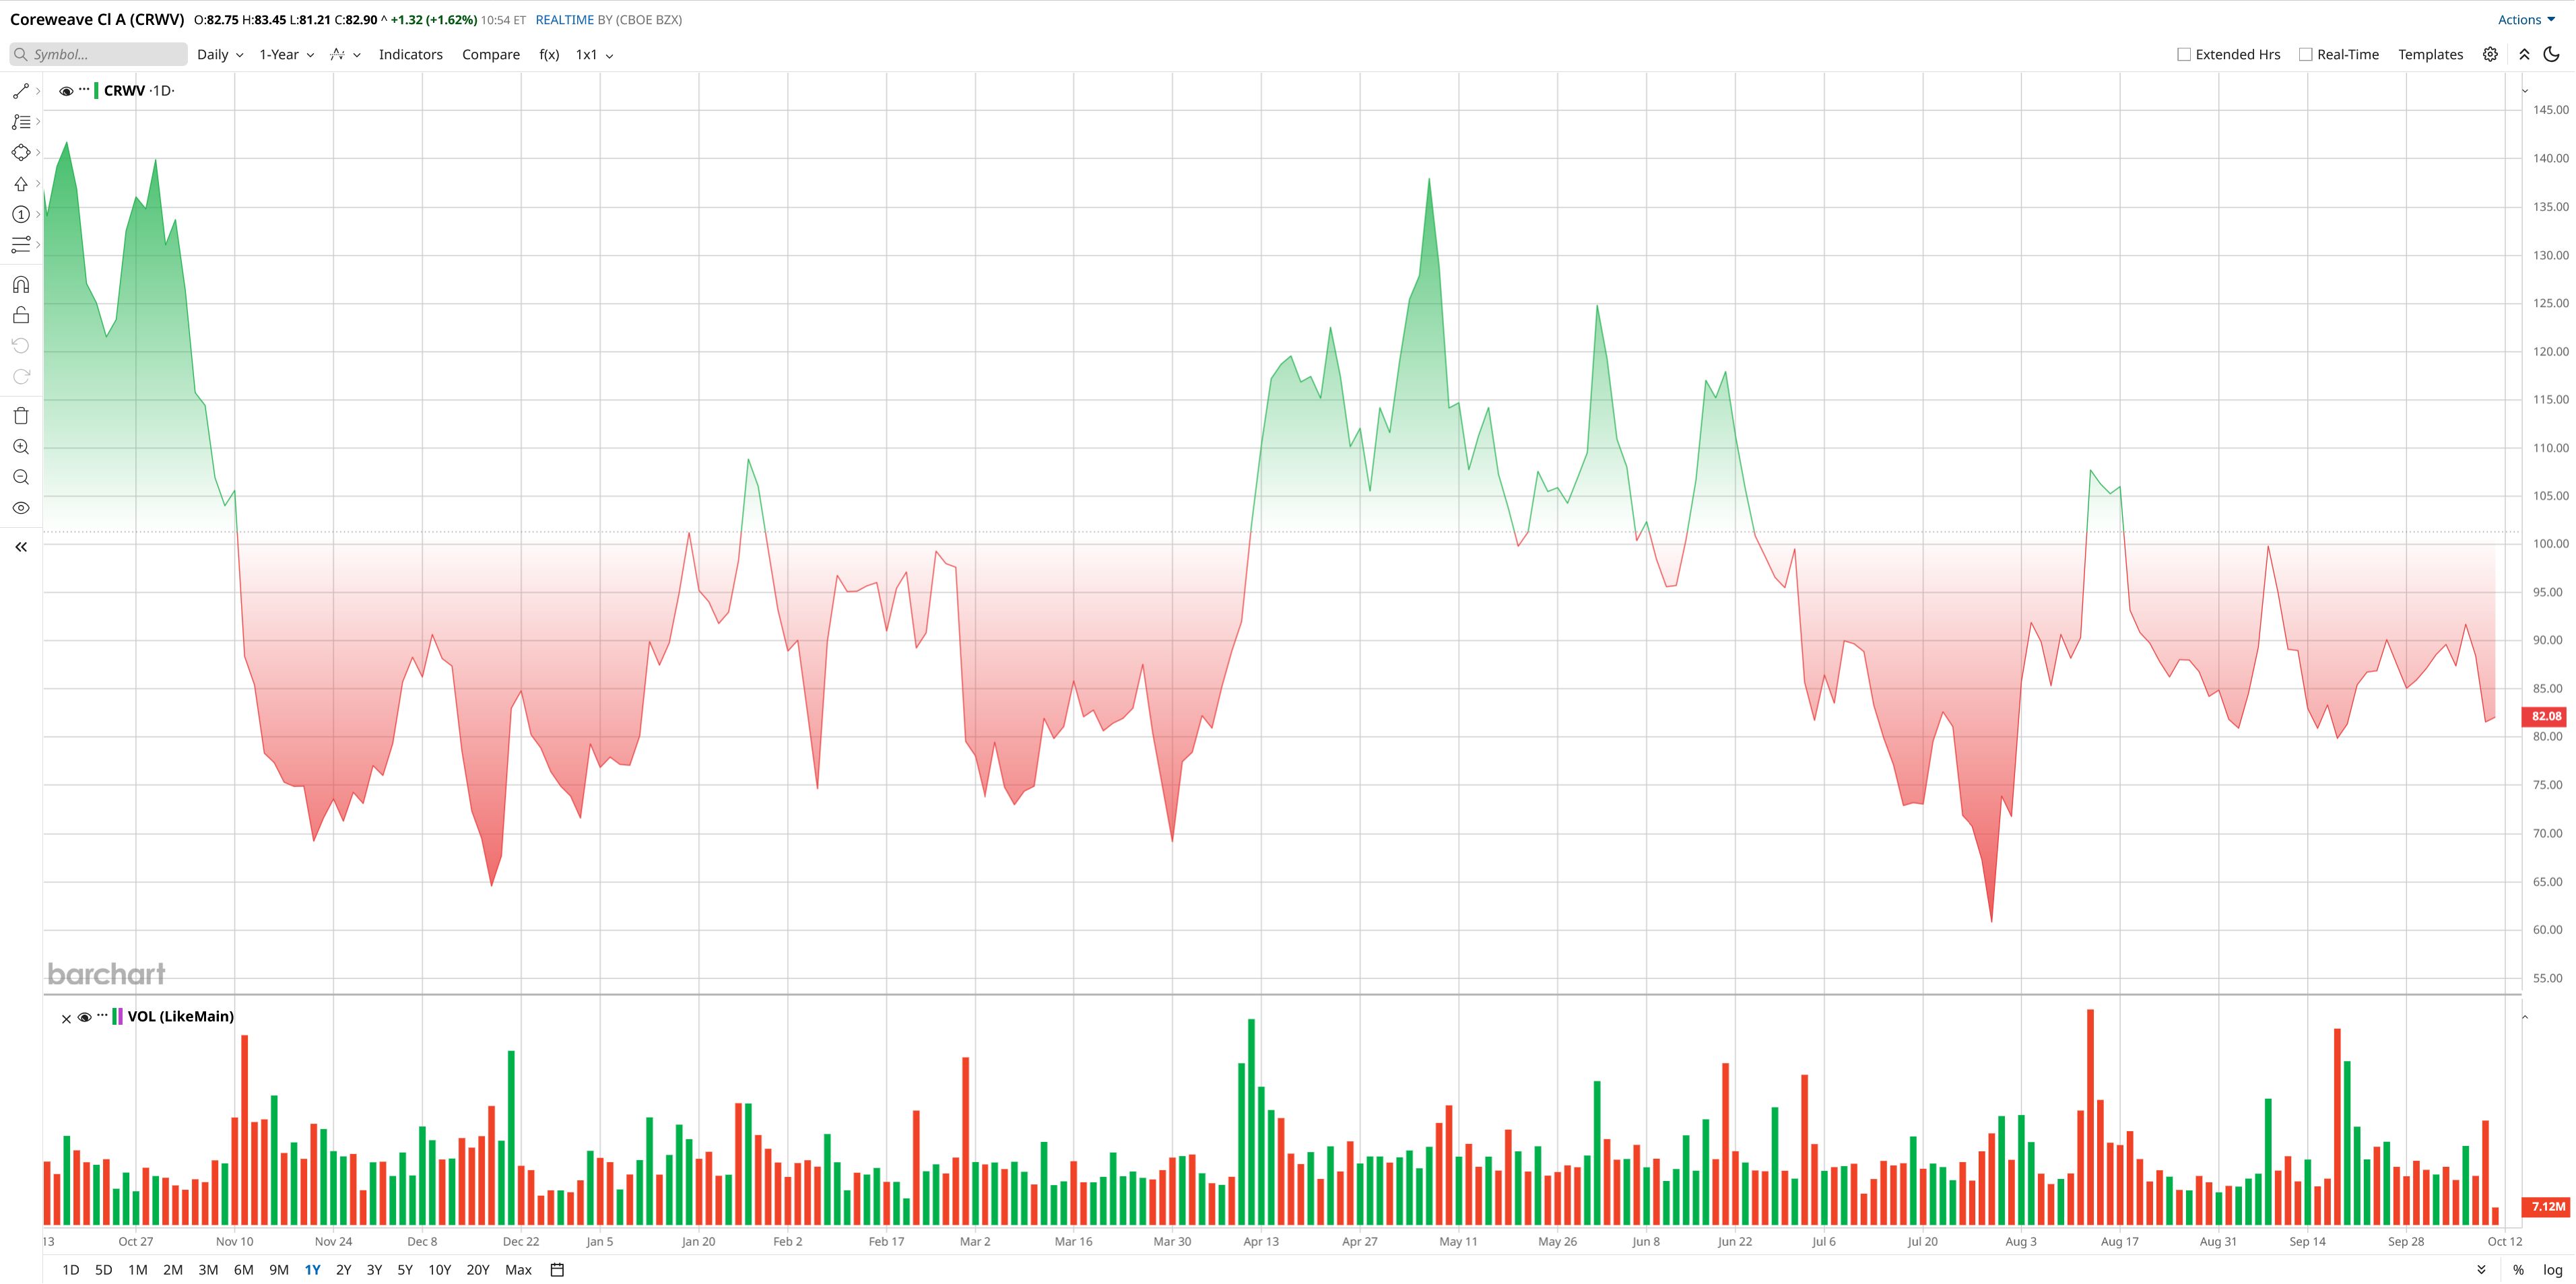
CoreWeave's stock has been all over the place. Over the past year, shares are down about 43%. But year-to-date (YTD) in 2026, the stock has gained roughly 14%. The 52-week range tells the story. That is wild volatility.
On the positive side, AI demand is red hot. CoreWeave raised GPU prices by 25% in July. Then it raised them another 10% in just two months. Pricing power like that gets investors excited. The company also landed massive deals with OpenAI, Microsoft (MSFT), Meta (META), and Anthropic. Its revenue backlog sits at $104 billion.
On the negative side, debt is the big worry. CoreWeave had roughly $35 billion in debt at the end of June. Interest expense hit $640 million last quarter. That is almost as much as the company generated from operations. Rising rates make that debt more expensive. Fears of an AI spending slowdown also spook investors.
 www.barchart.com
Why India Matters for CoreWeave
India is a massive opportunity. The country has talent, developers, and ambition. The government has supported data center growth for a decade. Wood Mackenzie expects India's data center capacity to hit 12 gigawatts by 2030. That would make it the second-largest market in Asia after China.
According to the report, CoreWeave is partnering with AdaniConneX. Together they will build three 80-megawatt buildings at the Taloja campus in Navi Mumbai. The first phase should be ready by mid-2028. CoreWeave has the option to double the capacity if demand warrants it. The company is also opening a regional office in India and hiring locally.
This is a solid stock catalyst. It creates a new income opportunity. It decreases dependence on the North American/European markets. At the same time, it enhances CoreWeave's partnership with Nvidia (NVDA). Nvidia's Vera Rubin platform will be used for the project. This helps ensure CoreWeave stays on top of AI hardware technology.
CoreWeave Is Also Raising Prices
CoreWeave is not just expanding geographically. It is also raising prices. In September 2026, the company disclosed that it raised per-hour GPU pricing by 25% in July. Then it raised prices another 10% in the following months. UBS analyst Karl Keirstead called the per-hour price of hosted Nvidia GPUs “inflationary.” He said revenue per gigawatt is moving higher. This is a key pillar of the bull case for neoclouds.
Higher prices mean better margins. CoreWeave says contracts signed in Q2 carried contribution margins 5 to 10 percentage points above recent quarters. If that trend continues, profitability could improve faster than expected.
The Latest Quarterly Results Were Strong
CoreWeave reported second-quarter 2026 results on Aug. 11, which beat analyst estimates on both the top and bottom lines. Revenue hit $2.575 billion. That is up 112% from a year earlier. It also rose 24% sequentially. Demand continues to outpace available capacity.
The company operates as a single segment. Its core business is renting out GPU compute power. Managed inference and software products are growing fast. Booked annual recurring revenue for managed inference jumped from $1 million to more than $100 million.
Net loss was around $626 million. That compares to a $290 million loss in the same quarter last year. The wider loss came from higher interest expense and stock-based compensation.
On the balance sheet, Free cash flow was still shown as negative $5.7 billion. CoreWeave ended the quarter with $6.9 billion in cash and equivalents. It also raised about $18 billion in debt and equity during the quarter.
CEO Michael Intrator said on the earnings call, “CoreWeave reached an important inflection point this quarter as our scale began to translate into expanding operating leverage. Customer demand is accelerating, as enterprise adoption broadens and we continue to deepen our technology platform.”
CFO Nitin Agrawal raised full-year revenue guidance to between $12.4 billion and $13.2 billion. Adjusted operating income guidance moved up to between $960 million and $1.15 billion. For the third quarter, the company expects revenue of $3.45 billion to $3.6 billion. Adjusted operating income should land between $200 million and $260 million.
Analysts expect full-year 2026 revenue of about $12.87 billion. They project an adjusted loss per share of $5.19.
What Wall Street Is Saying About CRWV Stock?
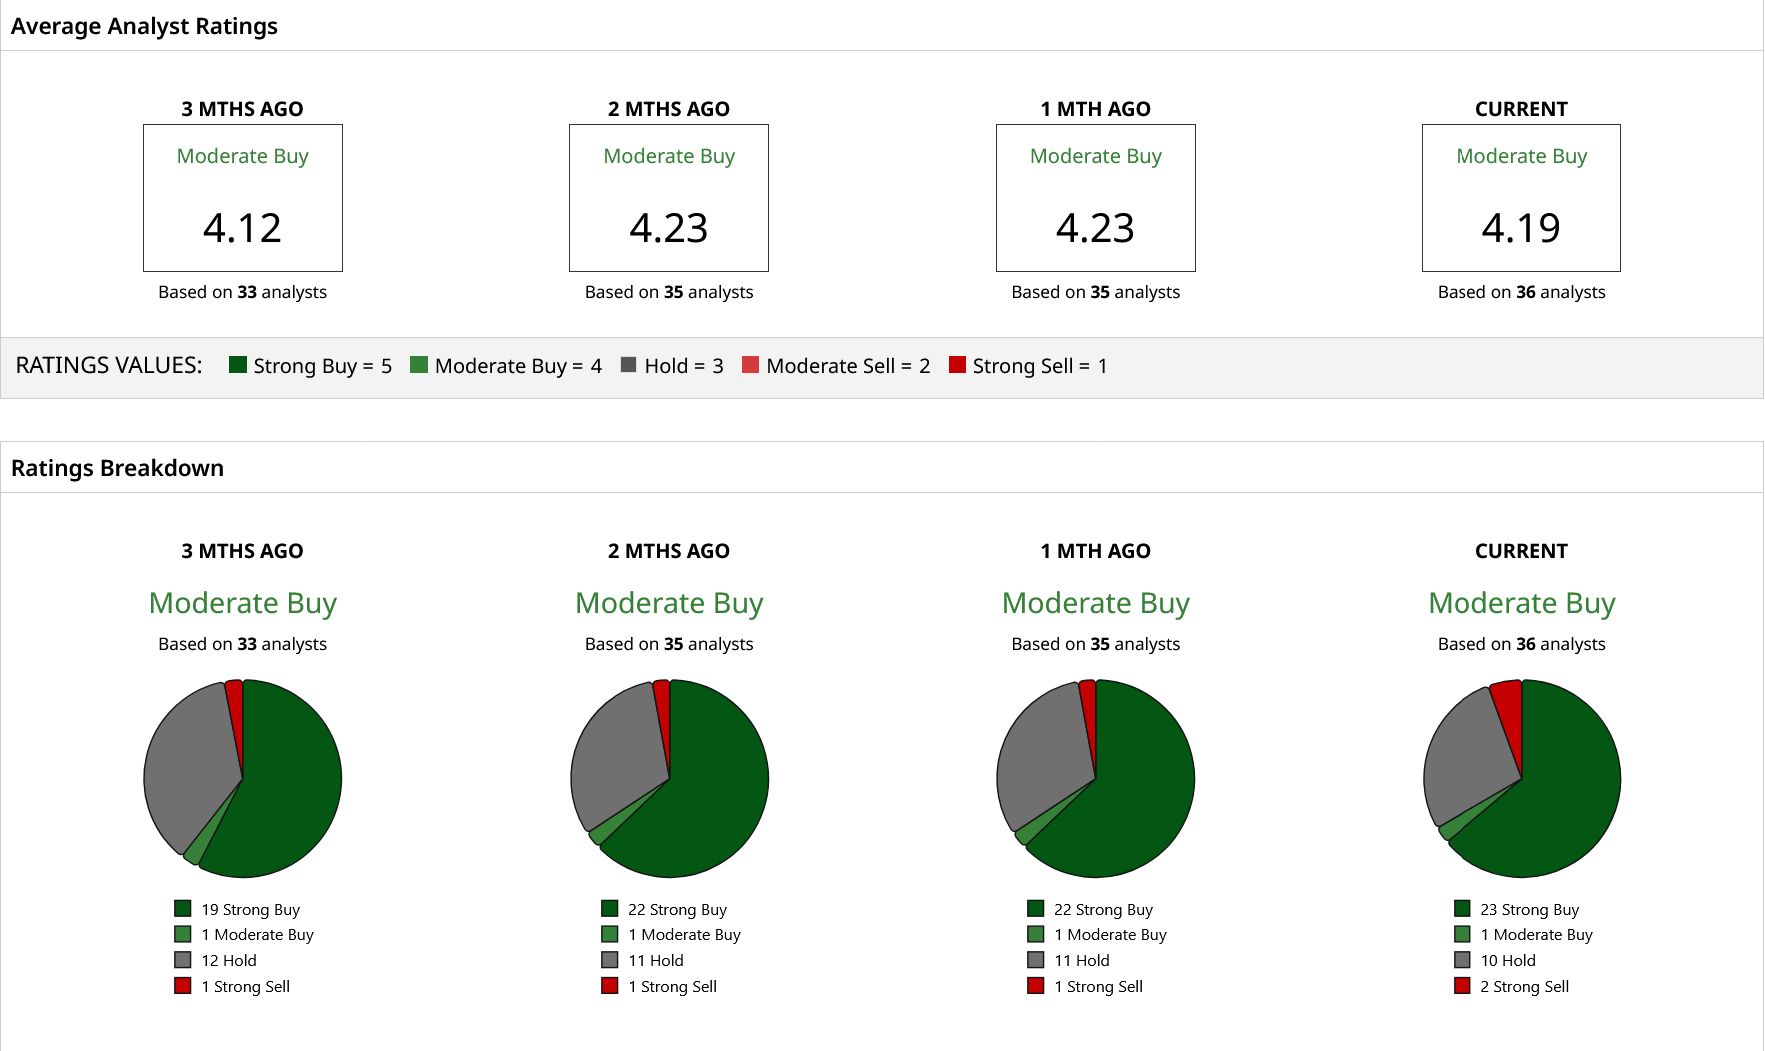
Analysts are split, but the majority lean bullish on CRWV stock. The consensus rating is “Moderate Buy.” The average price target sits at $137. That still suggests a significant upside of roughly 67% from the current price of about $82.
Individually, Northland just raised its price target to $200 from $165. The firm named CoreWeave as a Top Pick. It praised the company's Forge software suite. Northland said Forge “displays the culture of open innovation on a software level.”
Earlier, Truist analyst Arvind Ramnani maintained a “Buy” rating and raised his price target to $165. He emphasised the pricing power of CoreWeave. He added that 70% of all deals that were signed in Q2 incorporated prepayments. That is beneficial for cash flow.
JPMorgan upgraded CRWV stock to an “Overweight” rating and set a $125 target. Samik Chatterjee of the analyst group said the recent correction is “unjustified.” He cited declining compute supply and price increases as factors.
Conversely, Bernstein is on the bearish side. It labeled CoreWeave as “Underperform” with significant downside exposure, citing a $67 target. The company is concerned about limitations of capacity sales and a slowdown of AI spend.
All told, in my opinion, the India project is not going to provide any significant revenues until 2028. It's a long-term play, then. Capacity delivery, price movement, and debts are areas of interest for investors. But if CoreWeave is successful in executing its plan, the stock may pay off for patient investors. The risk if it slips up is high.
CRWV stock is still a high-risk/high-reward pick at this time anyway. Betting on India's side is a risky one. We'll just have to wait and see.
 www.barchart.com
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.