

Morgan Stanley has named Amazon (AMZN) its Top Pick and reiterated its “Overweight” rating. The bank cited the long-term growth potential of Prime, e-commerce, cloud computing, and advertising. But Brian Nowak, Morgan Stanley’s analyst, argues that AI may be the most overlooked driver of future growth. He believes it could drive AWS revenue to $1 trillion and eventually double Amazon’s share price.
Reaching that outcome would require rapid growth. After accounting for higher Nvidia (NVDA) GPU shipments, Nowak expects AWS revenue to grow 47% in 2027 and 42% in 2028. If the business also maintains strong margins, it could qualify as a “Rule of 90” business, with its growth rate and margin totaling 90%. Under this scenario, the company’s 2028 earnings per share would rise to about $16.50.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
AI is not the only potential growth driver. Nowak considers Bedrock an underappreciated opportunity and expects Amazon to form a Meta (META) partnership over time, potentially using its delivery network and Prime customer base. Robotics could offer another source of cost savings. For every 10% of global units processed through robotics-enabled fulfillment centers, Amazon could save $2 billion to $4 billion annually. Nowak raised his price target to $350, roughly 33% above Monday’s closing price of $262.45.
However, the possibility of Amazon’s stock doubling is a longer-term scenario, not what the analyst’s price target suggests. The $350 price target points to 40% upside, while a doubling would depend on GPU availability and AWS maintaining growth above 40% despite its already massive scale. The expected Meta tie-up has not been presented as an immediate development, and the potential robotics savings remain estimates, not achieved outcomes.
For the bullish thesis to play out, AI must help AWS grow faster and generate higher profits, while robotics continue to reduce operating expenses. Nowak’s $350 price target already reflects much of that potential. The $1 trillion revenue scenario requires further progress, so AWS growth remains the most important figure to watch.
About Amazon Stock
Amazon has come a long way from its beginnings as an online bookstore. Today, it sits at the center of U.S. e-commerce and the broader digital economy, with a market capitalization of roughly $2.65 trillion. Its reach extends well beyond retail, spanning cloud computing, digital advertising, streaming, smart devices, healthcare, and artificial intelligence. At the same time, Amazon is pushing deeper into the technology stack by developing its own chips for cloud and AI workloads, giving the company a larger role in the infrastructure behind the next wave of computing. Founded in 1994, the company is headquartered in Seattle, Washington.
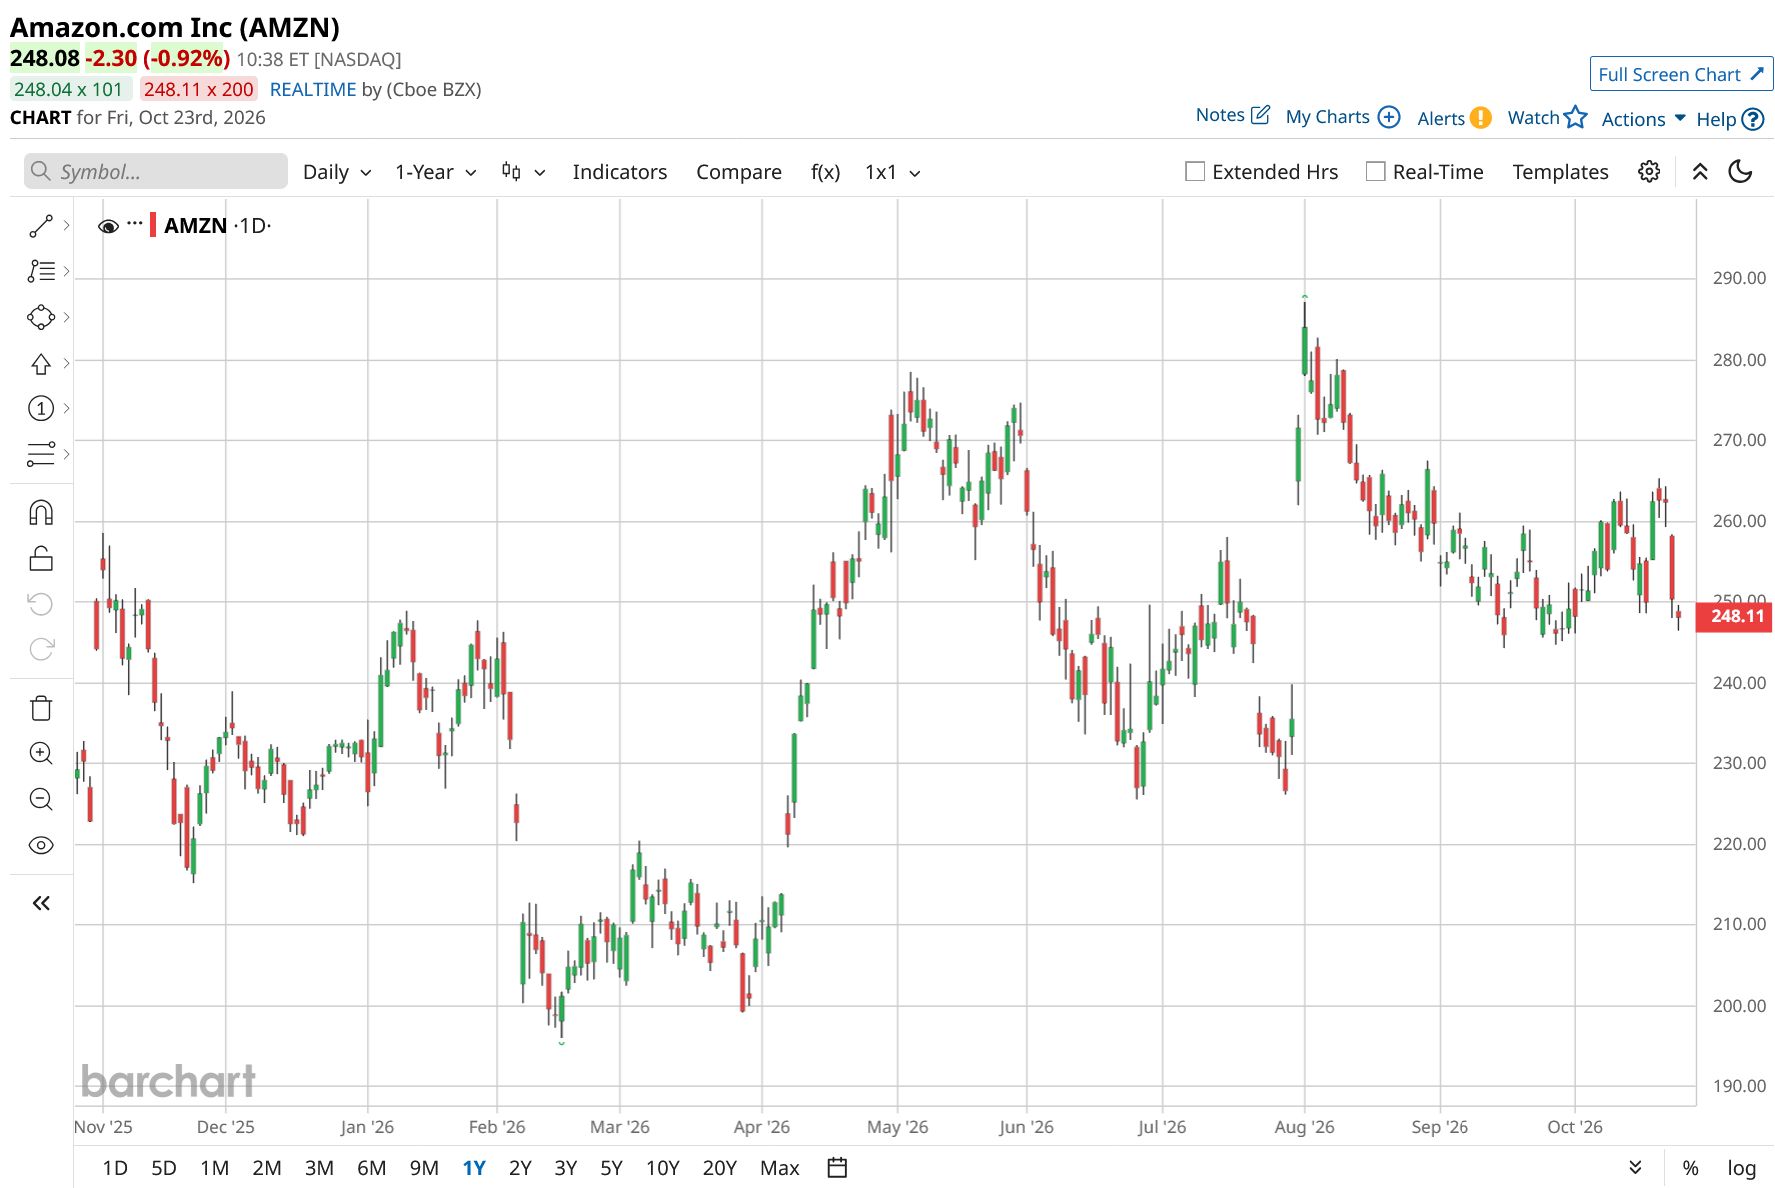
If we zoom out on Amazon’s chart, it is hard to miss just how much ground the stock has covered. Over the past 20 years, AMZN has delivered a staggering 13,047% return, turning a long-term investment into a very different story from the day-to-day swings investors often focus on. Even over the past five years, the stock has gained roughly 48%. More recently, AMZN shares have continued to build on that record, climbing 12% over the past year as Amazon expanded across e-commerce, cloud computing, advertising, and artificial intelligence.
 www.barchart.com
AWS Growth Accelerates as AI Demand Surges
Amazon reported its second-quarter fiscal 2026 earnings on July 31. The company’s worldwide revenue was $200.6 billion, a 20% increase year-over-year (YoY). This excluded the impact of foreign exchange. CFO Brian Olsavsky said the North America segment's second-quarter revenue was $116.2 billion, while the International segment revenue was $42.2 billion. The company’s chip business had an annual revenue run rate of over $25 billion. Cash capex for the quarter was $53.1 billion in Q2, primarily relating to AWS and generative AI.
Looking forward, AMZN is set to report its Q3 earnings soon. Third-quarter sales are expected to be between $197 billion and $202 billion. Operating income is expected to be between $22.5 billion and $26.5 billion. Earlier this year, the company planned to invest approximately $200 billion in cash capex in 2026; however, it now believes it will spend approximately $220 billion due to the higher cost of memory. Moreover, currency movements are expected to be a small headwind for the company’s Q3.
What Do Analysts Expect for AMZN Stock?
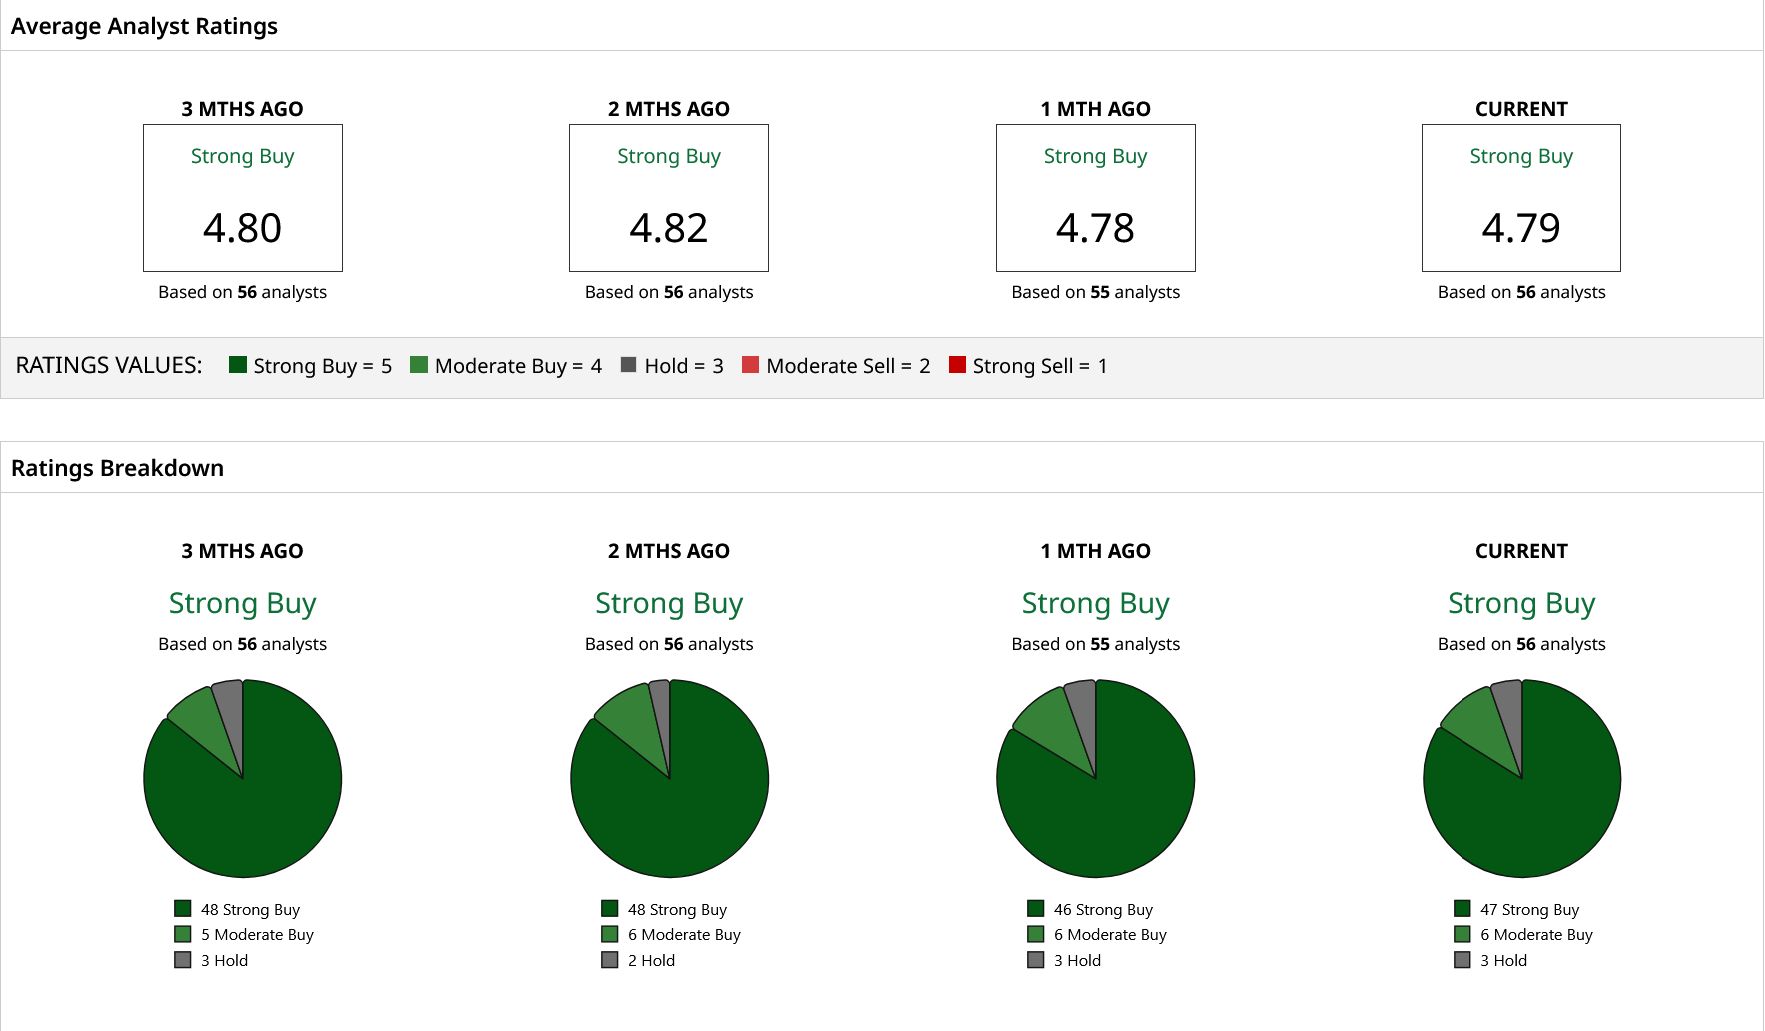
Wall Street remains highly optimistic about AMZN stock, with it earning an overall consensus of a “Strong Buy” rating. Out of 56 analysts, 47 have a “Strong Buy” rating, six have a “Moderate Buy” rating, and three are cautious with a “Hold” rating. The mean price target of $329.47 reflects a 33% upside potential from here. Meanwhile, the Street-high price target of $405 implies an additional 63% upside from the current share price.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Morgan Stanley Sees Amazon Stock Surging 100% with AWS Hitting $1 Trillion in Revenue Sooner Than People Think Big Tech Earnings, Fed Decision and Other Key Things to Watch this Week How to Play RKLB Stock as Rocket Lab Pushes Its Neutron Launch to Next Year Dell, Lenovo, Cisco, HPE, Supermicro: Why AMD’s New AI Blueprint Has Everyone Signing On