

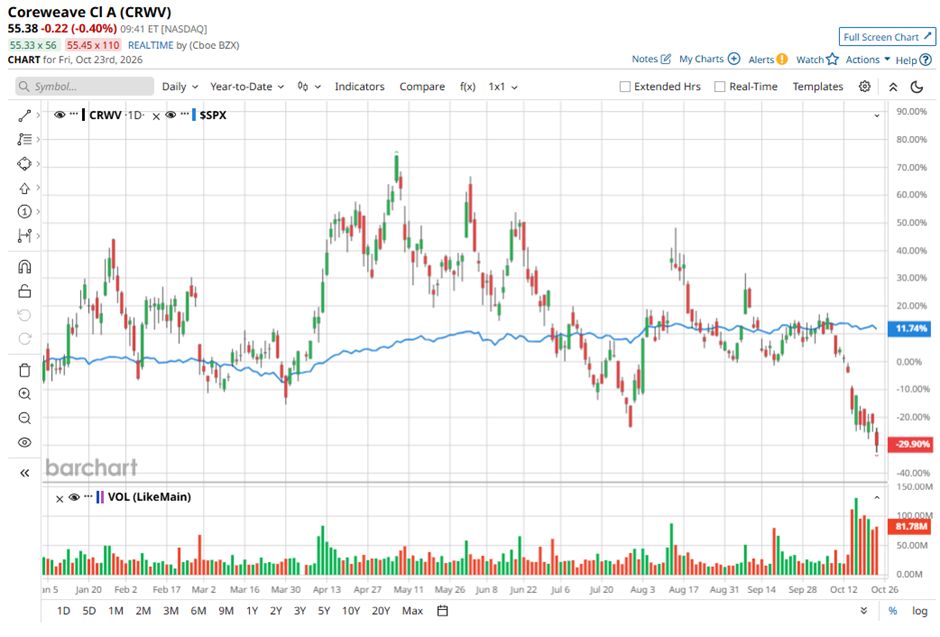
Once a high-flying artificial intelligence (AI) cloud infrastructure player, CoreWeave (CRWV) is now facing a growing crisis of confidence on Wall Street. Shares tumbled to a 52-week low of $53.50 on Oct. 22 as rising interest rates and mounting concerns over the cost of the AI infrastructure boom rattled both stock and bond investors. Debt-heavy neocloud providers like CoreWeave are increasingly under scrutiny, with investors questioning whether the company can finance its massive AI expansion without taking on excessive financial risk.
The pressure is showing up in the bond market, too, with yields on some CoreWeave bonds climbing to roughly 15%. Adding to the gloom, Bernstein recently cut its price target on CRWV stock to $51 from $74 while maintaining an “Underperform” rating. Still, Bernstein analyst Madison Rezaei does not expect CoreWeave to go to zero, citing its backlog and the possibility that Nvidia (NVDA) — which owns about 9% of the company — could step in.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
While the backlog may help keep the business afloat, CoreWeave still needs outside capital to fuel its growth, and that money is getting increasingly expensive. With shares sliding and financing risks mounting, let's take a closer look.
About CoreWeave Stock
Founded in 2017, CoreWeave is a specialized cloud computing provider built to meet the demanding infrastructure needs of AI. The company offers a platform combining high-performance computing (HPC) infrastructure, software tools, and technical expertise to help AI innovators develop, train, and scale their models. Serving leading AI research labs, startups, and global enterprises, CoreWeave focuses on delivering the computing power and infrastructure required to support increasingly complex AI workloads.
CoreWeave went public on the Nasdaq in March 2025, positioning itself among the specialized cloud providers catering to the rapidly expanding AI industry. With a market capitalization of approximately $25 billion, CoreWeave is facing mounting pressure on Wall Street as investors grow increasingly uneasy about its debt-fueled AI infrastructure expansion and a selloff in its bonds. The selloff has taken a heavy toll on CRWV stock, with shares plunging 55% over the past year and 24% in 2026 alone.
The downturn has intensified in recent days, with the stock tumbling 12% over the past five sessions. By comparison, the broader S&P 500 Index ($SPX) has climbed 13% over the past year and gained 11% so far in 2026, highlighting CoreWeave’s steep underperformance. Although shares have rebounded slightly since hitting a 52-week low, the modest recovery offers little relief amid persistent concerns over financing risks and the company's ambitious expansion plans.
 www.barchart.com
CoreWeave’s Q2 Earnings Snapshot
CoreWeave’s fiscal 2026 second-quarter results highlighted the extraordinary growth opportunity in AI infrastructure, with surging enterprise demand driving triple-digit revenue growth. CoreWeave reported revenue of $2.58 billion, up 112% year-over-year (YOY) and coming in ahead of Wall Street’s estimate of $2.54 billion. However, beneath that impressive top-line performance, the company’s capital-intensive expansion continued to weigh on profitability, underscoring the financial trade-offs involved in scaling its AI infrastructure business.
CoreWeave reported a GAAP loss of $1.14 per share, wider than the $0.60 loss per share in the comparable period. On the brighter side, adjusted EBITDA reached $1.51 billion, translating to a robust 59% margin. Adjusted operating income came in at $128 million, above the company’s guided range and offering an encouraging sign that operating leverage is beginning to emerge across its capital-intensive data-center network.
Nevertheless, rising financing costs remained a significant drag, with quarterly interest expenses climbing to $640 million and contributing to a GAAP net loss of $626 million. Meanwhile, CoreWeave’s commercial pipeline continued to expand rapidly. Total revenue backlog surged 246% YOY to $104 billion, while customers committed an additional $25 billion shortly after the quarter ended.
Although these commitments point to substantial future demand, converting them into revenue will require significant investment in computing capacity and infrastructure. That investment was already evident in Q2, with capital expenditures reaching $9.4 billion. As of June 30, CoreWeave held more than $6.9 billion in cash, cash equivalents, restricted cash, and marketable securities.
To support its aggressive expansion, CoreWeave made progress in strengthening its balance sheet and broadening its access to capital, raising approximately $18 billion during Q2 through a combination of debt, convertible securities, and equity. While this financing provides resources to accelerate infrastructure deployment, it also highlights the enormous capital requirements associated with the company’s growth strategy.
Looking ahead, CoreWeave raised its year-end capacity expectations following continued execution, now anticipating more than 1.85 gigawatts of active power by the end of 2026, up from its previous guidance of 1.7 GW. For Q3, management expects revenue between $3.45 billion and $3.6 billion alongside adjusted operating income of $200 million to $260 million. Operating margins are expected to expand sequentially, reaching the low teens by Q4. However, the expansion will come at a considerable cost.
CoreWeave projects Q3 interest expenses of $860 million to $940 million, reflecting a larger debt balance used to finance accelerating infrastructure deployments. Capital expenditures are also expected to rise sharply to between $11.5 billion and $13.5 billion as the company delivers substantial new capacity to customers.
How Do Analysts View CoreWeave Stock?
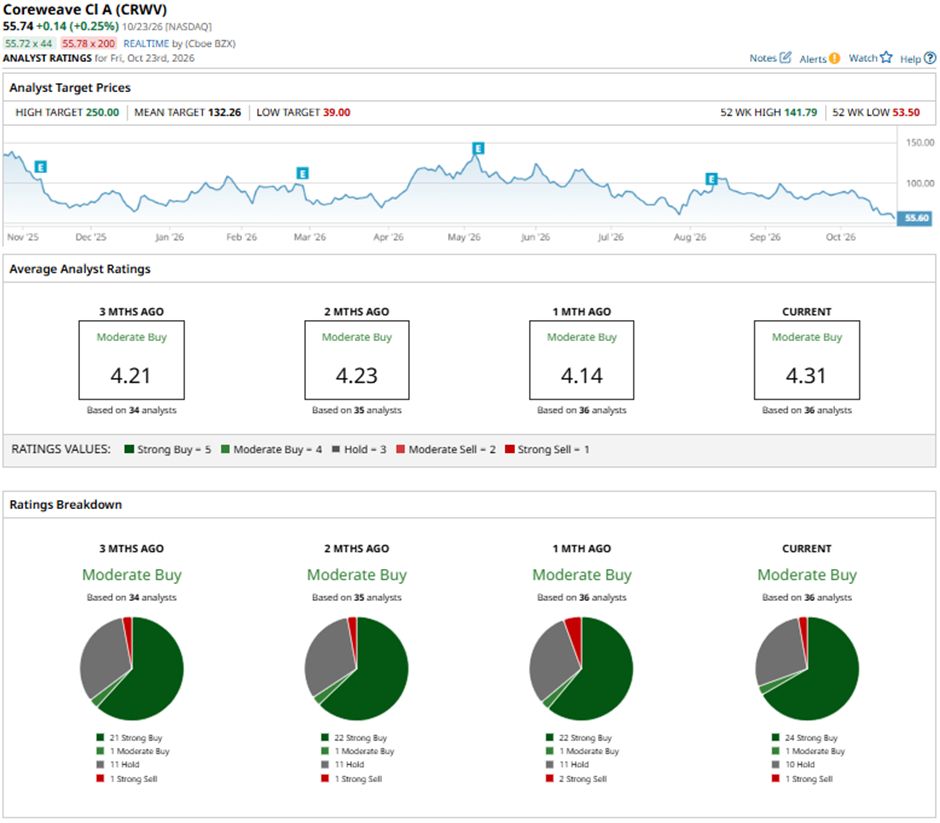
Despite CoreWeave’s steep selloff and Bernstein’s bearish outlook, Wall Street remains broadly bullish, with CRWV stock carrying a consensus “Moderate Buy” rating. Of the 36 analysts covering the stock, 24 recommend a “Strong Buy” rating, one has a “Moderate Buy,” 10 have a “Hold" rating, and one analyst has a “Strong Sell.”
The average price target of $131.83 implies potential upside of approximately 143% from current levels, while the Street-high price target of $250 points to a staggering potential rally of 361% from here. That highlights the sharp divide between the stock’s recent struggles and analysts’ recovery expectations.
 www.barchart.com
On the date of publication, Anushka Mukherji did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
CRWV Stock Warning: Why Bernstein Says CoreWeave Shares Haven’t Bottomed Out Yet How to Play the Brutal Selloff in CoreWeave Stock Tesla Is Betting on a Flying Car to Combat Its Stock Slump Wedbush Gives a Thumbs Up to Super Micro’s Preliminary Q1 Results. Troubles for SMCI Stock Could Finally Be in the Rear-View.