

The Wendy’s Company WEN is working to restore profitability as persistent traffic weakness and pressure on restaurant economics weigh on performance. During the second quarter of 2026, global systemwide sales declined 6.5% in constant currency, while U.S. same-restaurant sales fell 7% due to a 12.5% drop in traffic that was partially offset by a 5.6% increase in average check.
The profitability challenge is reflected in WEN’s second-quarter results. Adjusted EBITDA declined $22.5 million year over year to $124.1 million, while adjusted revenues fell 1.4% to $443.2 million. U.S. company-operated restaurant margin was 13.8%, with higher commodity and labor costs weighing on restaurant economics, partly offset by higher average check and labor efficiencies.
The second-half outlook provides an important checkpoint for the EBITDA recovery. WEN expects traffic trends to remain challenging, with July traffic consistent with second-quarter levels. The company does not expect to return to year-over-year systemwide sales growth in the third or fourth quarters and anticipates continued pressure on company-operated margins and adjusted EBITDA from sales deleverage, 5%-6% full-year commodity inflation and higher G&A tied to turnaround investments. WEN has also withdrawn its 2026 financial outlook.
The turnaround remains focused on addressing the underlying factors weighing on traffic and restaurant economics. WEN is prioritizing food quality and value, stronger branding and marketing, operational excellence, a better digital experience and healthier restaurant-level economics. Management identified quality degradation, challenges around value offerings, inconsistent operations and ineffective marketing as key areas requiring improvement.
WEN’s ability to generate EBITDA progress will likely depend on whether its turnaround can rebuild traffic through stronger value and quality, improve restaurant-level execution and strengthen the customer experience. These initiatives can support sales leverage and restaurant economics, while disciplined investment in the turnaround will be central to improving margins and restoring EBITDA growth.
Wendy’s Competitor Landscape
McDonald’s Corporation MCD provides a relevant benchmark for WEN because it is also addressing traffic weakness through improvements in value, digital engagement and restaurant execution. In the second quarter of 2026, McDonald’s U.S. comparable sales increased 0.8% despite traffic pressure linked to value execution and a pullback in digital offers. The company is responding with more national digital flash offers, personalized promotions and a greater focus on proven value initiatives to re-engage customers and improve baseline traffic.
Starbucks Corporation SBUX offers another benchmark, with traffic recovery supported by loyalty engagement, product innovation and improvements in the customer experience. In the third quarter of fiscal 2026, global comparable sales increased 7.9%, driven by a 4% jump in transactions, while U.S. comparable sales rose 7.9% with transactions up 4.2%. Starbucks also reported 35.8 million 90-day active Rewards members in the United States, while initiatives such as targeted loyalty benefits and menu innovation are helping encourage repeat purchases and engagement.
Against this backdrop, WEN’s positioning depends on whether its turnaround can translate investments in value, food quality, marketing and operational execution into stronger traffic and restaurant-level economics. McDonald’s is emphasizing value, marketing and execution to strengthen its U.S. business, while Starbucks is demonstrating stronger transaction growth alongside loyalty and customer-experience initiatives. WEN’s differentiation will depend on how effectively it addresses the quality, value and operational issues weighing on traffic while improving restaurant economics and managing the cost pressures weighing on EBITDA.
WEN’s Price Performance, Valuation & Estimates
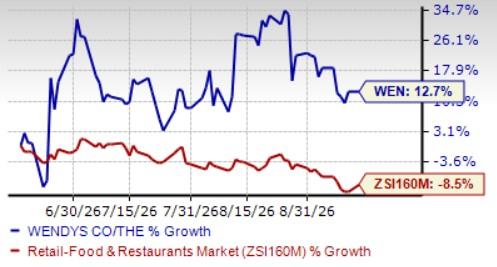
Shares of Wendy’s have gained 12.7% over the past three months against the industry’s 8.5% drop.
WEN Three-Month Price Performance
Image Source: Zacks Investment Research
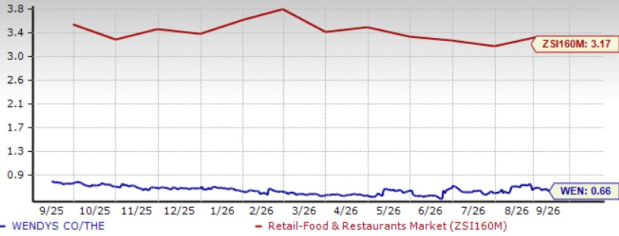
From a valuation standpoint, WEN trades at a forward price-to-sales (P/S) multiple of 0.66, below the industry’s average of 3.17.
WEN’s P/S Ratio (Forward 12-Month) vs. Industry
Image Source: Zacks Investment Research
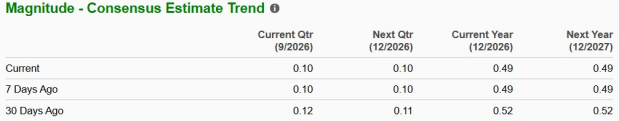
The Zacks Consensus Estimate for WEN’s 2026 earnings per share (EPS) implies a year-over-year decline of 44.3%. The EPS estimates for 2026 have declined in the past 30 days.
EPS Trend of WEN Stock
Image Source: Zacks Investment Research
WEN’s Zacks Rank
WEN stock currently has a Zacks Rank #4 (Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
The Wendy's Company (WEN): Free Stock Analysis Report
Starbucks Corporation (SBUX): Free Stock Analysis Report
McDonald's Corporation (MCD): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).