

Docusign, Inc. DOCU shares have gained 13.4% in the past month as customer expansion improved and Intelligent Agreement Management (IAM) became a larger part of annual recurring revenue.
The rally has operational support, but its durability depends on continued IAM adoption, execution against raised fiscal 2027 targets and disciplined pricing as competition broadens.
Why DOCU's One-Month Rally Has Fundamental Support
Docusign ended the July quarter with more than 1.9 million customers, up nearly 10% year over year. Direct-customer dollar net retention improved to 103%, with expansion contributing more to the gain.
Larger accounts are also expanding. Customers spending more than $300,000 in annual contract value rose 14% to nearly 1,300 for a second consecutive quarter of double-digit growth, giving the recent share-price move a firmer operating backdrop.
Docusign's IAM Mix Keeps Expanding
IAM represented 15.1% of total annual recurring revenue (ARR) in the second quarter of fiscal 2027, up from 12.6% in the first quarter and 10.8% at fiscal 2026 year-end. Management expects the mix to reach 18%-19% exiting the fourth quarter.
Most IAM ARR is coming from the installed base, while eSignature-to-IAM upgrades are creating expansion opportunities. Salesforce, Inc. CRM is relevant on the ecosystem side because its platform strategy emphasizes AI agents and Slack-based workflows. Docusign's Salesforce and Slack integrations extend IAM into tools customers already use.
DOCU's Raised Outlook Adds Earnings Support
Docusign raised fiscal 2027 revenue guidance to $3.499-$3.507 billion, implying about 9% growth at the midpoint. ARR growth is expected at 8.5%-9%, versus 8% in fiscal 2026.
Full-year non-GAAP operating margin guidance of 31%-31.5% also points to continued operating leverage. In the latest quarter, adjusted earnings of $1.16 per share rose 26.1% and topped the Zacks Consensus Estimate of $1.08, providing recent execution support for the higher outlook.
Docusign's Cash Flow Backs Aggressive Buybacks
Free cash flow climbed 35.9% to $295.8 million in the latest quarter, while free cash flow margin improved to 34% from 27%. Docusign repurchased $306.5 million of stock during the period.
The company still had $2.1 billion authorized for future repurchases, and diluted shares outstanding declined 8% year over year to 193 million. A lower share count can support per-share results, although buybacks do not replace operating growth.
DOCU's Valuation and Risks Test the Rally
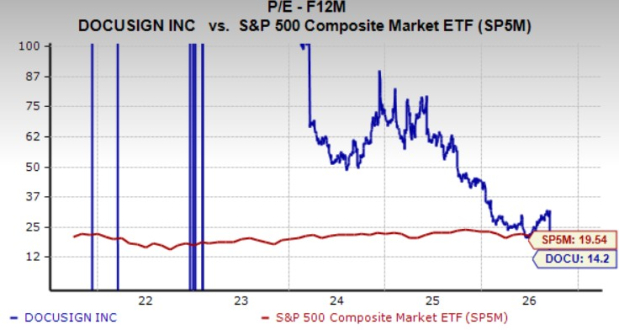
DOCU trades at 14.2X forward 12-month consensus EPS estimate, below 29.4X for its Zacks sub-industry, 20.4X for the Zacks Computer and Technology sector and 19.5X for the S&P 500. Adobe Inc. ADBE, through Acrobat and Acrobat Sign, remains a direct e-signature competitor.
Image Source: Zacks Investment Research
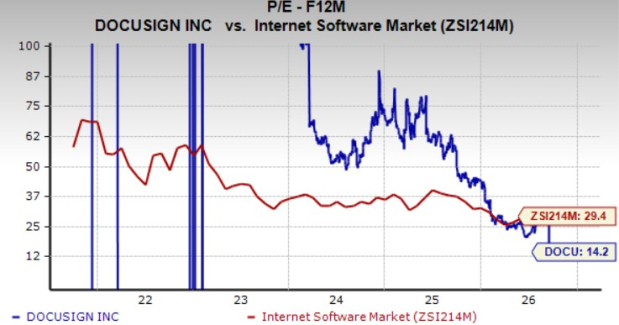
Image Source: Zacks Investment Research
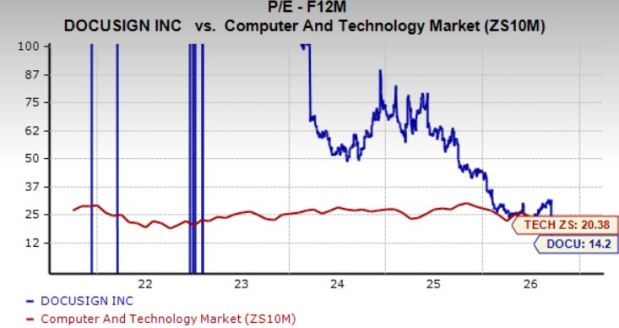
Image Source: Zacks Investment Research
Discounting is a key test as IAM expands. Docusign says larger enterprises may seek sizable price concessions, while lower-priced bundles and generic AI tools could intensify competition. Current assets also remained below current liabilities as of July 31, despite $973.1 million in cash, cash equivalents and investments and no debt.
DOCU's Growth Signals Offset a Mixed Value Profile
The recent advance aligns with improving customer expansion and a larger IAM contribution, while raised guidance and cash generation add support. Pricing competition and execution around the platform transition remain the main checks on further momentum.
The stock currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
DOCU also has a Growth Score of A, Momentum Score of B, Value Score of C and a VGM Score of A. The Style Scores indicate favorable growth and momentum characteristics, while the Value Score is less favorable. Because Style Scores complement rather than replace the Zacks Rank, the #3 rank keeps the near-term signal measured.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Docusign Inc. (DOCU): Free Stock Analysis Report
Salesforce, Inc. (CRM): Free Stock Analysis Report
Adobe Inc. (ADBE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).