

Netflix NFLX and Disney DIS sit atop the global streaming industry, together commanding hundreds of millions of subscribers and pouring billions into original content every single year. Both built that leadership from very different starting points, one a technology-first streaming pioneer, the other a century-old entertainment conglomerate now anchored around direct-to-consumer distribution.
With both stocks trading at rich valuations, and each issuing quarterly results and content announcements recently, investors are weighing which streaming giant offers the sturdier fundamental setup right now.
Let's delve deep and closely compare the fundamentals of the two stocks to determine which one is a better investment now.
The Case for NFLX Stock
The case for NFLX rests on consistent execution. Netflix's second-quarter 2026 shareholder letter showed revenues climbing 13% year over year to $12.6 billion, with a 33% operating margin, and management narrowed full-year revenue guidance to $51-$51.4 billion while reaffirming a 31.5% margin target for the year. The company continues scaling advertising, aiming to roughly double ad revenues in 2026 and is expanding live programming, gaming and vertical-clip video formats to widen engagement beyond traditional viewing hours.
Netflix's content pipeline remains fairly deep for the rest of 2026, with The Gentlemen Season 2, the true-crime anthology Monster: The Lizzie Borden Story , the comedy Best of the Best , and the biopic Unabomber all arriving this fall, ahead of Wednesday Season 3 and Narnia: The Magician's Nephew slated for 2027. However, challenges linger. Netflix pointed to softer engagement trends and a recognition that quality and variety, not just volume, must keep improving together.
Free cash flow declined meaningfully year over year in the second quarter, partly reflecting one-time tax costs, and content amortization is expected to stay elevated through the back half of 2026. Competitive pressure from rivals investing in franchises, gaming and live sports also continues to test Netflix's pricing power over time. Overall, Netflix presents a financially disciplined, still-growing business, but one navigating engagement questions, moderating cash generation, and rising content costs that together keep its near-term setup more balanced than clearly favorable for investors weighing an entry point today.
The Zacks Consensus Estimate for NFLX’s 2026 earnings is pegged at $3.59 per share, unchanged over the past 30 days.
Netflix, Inc. Price and Consensus
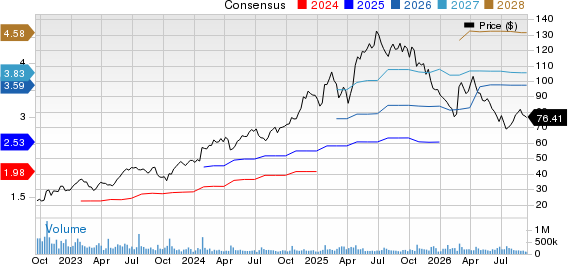
Netflix, Inc. price-consensus-chart | Netflix, Inc. Quote
The Case for DIS Stock
The case for DIS looks increasingly compelling right now. Disney's fiscal third-quarter 2026 results, covering the period ended June 27, showed revenues rising 7% year over year to $25.2 billion and total segment operating income up 21% to $5.6 billion, with adjusted earnings per share climbing to $2.06 from $1.61 a year earlier. Streaming profitability stood out, as combined Disney+ and Hulu operating income more than doubled to $712 million, while the Experiences segment sustained a nearly 30% operating margin through the first nine months of the fiscal year. Management is backing this momentum with a multiyear capital plan exceeding $60 billion for parks and cruises and accelerating share repurchases to at least $9 billion for shareholders.
Disney's content pipeline through early 2027 looks unusually rich: Zootopia 2 and Avengers: Doomsday arrive in the coming months, Star Wars: The Mandalorian and Grogu and an upcoming Ahsoka Season 2 extend the Lucasfilm slate, and Toy Story 5 keeps generating box-office and consumer-products momentum after crossing $1 billion globally.
ESPN's continued expansion within the Disney+ app, including deeper college football, NBA coverage and live-event programming such as the September "Max vs 100" special, strengthens the bundle's everyday utility for subscribers. With a One Disney strategy unifying data across studios, streaming and parks, disciplined capital allocation and a broadening, high-value content slate, Disney's fundamentals appear to be strengthening across nearly every reporting segment heading into fiscal 2027, giving the House of Mouse genuine momentum across its business on multiple fronts simultaneously and consistently.
The Zacks Consensus Estimate for Disney’s earnings for fiscal 2026 is pegged at $6.91, revised upwards by 0.4% over the past 30 days.
The Walt Disney Company Price and Consensus
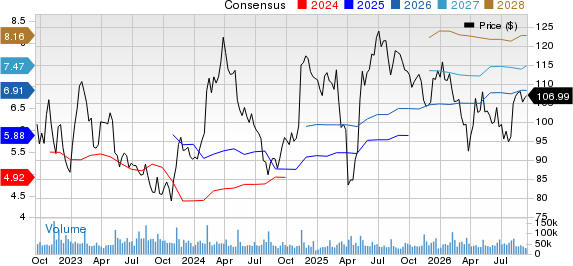
The Walt Disney Company price-consensus-chart | The Walt Disney Company Quote
Valuation and Price Performance Comparison
Both Disney and Netflix trade at premium valuations, but the extent of that premium differs significantly. Disney trades at a forward P/E of 14.36x, while Netflix commands a steeper 20.33x multiple.
NFLX vs. DIS P/E Ratio
Image Source: Zacks Investment Research
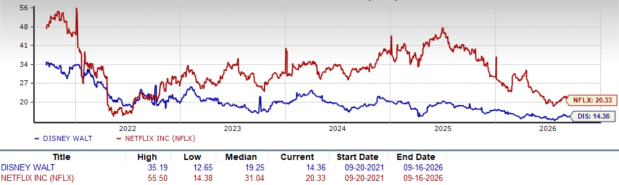
On price performance, shares of Disney have lost 6% over the year-to-date period, outperforming the Zacks Consumer Discretionary sector and Netflix, which have plunged 11.65 and 18.5%, respectively.
NFLX Underperforms DIS Year to date
Image Source: Zacks Investment Research
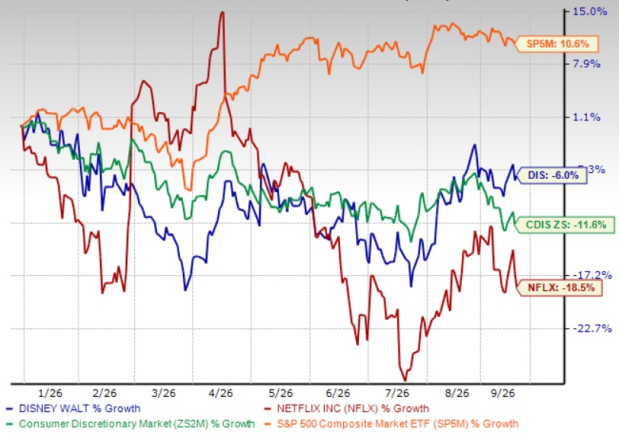
Disney's comparatively modest premium is easier to justify given its broader, diversified earnings growth engine, making it worth watching despite the multiple. Netflix's steeper premium, paired with a sharper year-to-date decline, suggests investors should stay away from the stock at present and patiently wait for a more attractive entry point before adding fresh positions.
Conclusion
Disney's edge over Netflix stems from diversified profit growth across streaming, parks and studios, record Disney+ and Hulu profitability, disciplined capital returns, and an unusually rich, high-visibility content pipeline running through early 2027. Netflix remains a solid, well-run business, but softer engagement commentary, elevated content costs, and a steeper valuation premium temper its near-term appeal. Given these fundamentals, Disney holds better upside potential from current levels. Investors should track and hold onto Disney stock for the long term, while staying away from Netflix stock entirely right now, or waiting patiently on the sidelines until a more favorable entry point emerges. While DIS carries a Zacks Rank #3 (Hold), NFLX has a Zacks Rank #4 (Sell) at present.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Netflix, Inc. (NFLX): Free Stock Analysis Report
The Walt Disney Company (DIS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).