

On Holding AG’s ONON momentum in Europe, the Middle East, and Africa (EMEA) underscores the durability of its premium brand strategy. By combining product innovation with disciplined distribution, selective wholesale expansion and elevated direct-to-consumer (DTC) experiences, the company is widening reach without diluting the brand. This approach protects full-price integrity, deepens engagement and supports profitable growth.
In the second quarter of 2026, EMEA net sales increased 15.4% year over year to CHF 228.2 million or 20.5% at constant currency. The region accounted for 26.8% of net sales, up from 26.4% a year earlier. Growth reflected distributor-network gains, continued strength in the United Kingdom and accelerating demand in France, Italy and Spain.
EMEA’s performance complements On Holding’s broader channel strategy. Global DTC net sales rose 26% to CHF 388.4 million or 34.3% at constant currency, increasing DTC’s share of quarterly sales to 45.7% from 41.1% a year earlier. The richer channel mix, operational efficiencies and full-price discipline helped lift gross margin 390 basis points to 65.4%.
Brand-building provides additional support. Management said the Champs-Elysees flagship was On Holding’s strongest-performing store globally in the quarter, while its Stockholm flagship performed at twice the expected level after two months. Cloudtilt models took three of Foot Locker Europe’s top five selling positions last quarter, signaling traction beyond performance running.
For 2026, On Holding expects constant-currency sales growth in the low-20% range, with DTC strongly outperforming wholesale in the second half. The company raised its gross-margin outlook to at least 65% and maintained its adjusted EBITDA margin target of 19.5-20%. Promotional conditions and foreign-exchange headwinds warrant monitoring, but EMEA’s momentum supports the premium-growth thesis.
DECK & WWW’s Global Momentum vs. ONON
Deckers Outdoor Corporation DECK maintained solid global momentum in first-quarter fiscal 2027, with revenues exceeding $1 billion. International sales rose 8.4% to $502.1 million, outperforming domestic growth of 3.2%. HOKA recorded robust international DTC growth across Europe, China and Japan. UGG’s international growth was led by Asia and effective mono-brand retail execution. Deckers achieved 13% companywide DTC growth, reflecting healthy full-price demand. This broad-based strength positions Deckers for faster growth in the second half.
Wolverine World Wide WWW delivered solid global momentum in second-quarter 2026, with revenues rising 6.8% to $506.4 million. International revenues increased 10.9% to $277.2 million, outpacing companywide growth and accounting for nearly 55% of sales. Merrell and Saucony recorded respective revenue growth of 11.1% and 9.9%, supported by international wholesale strength. Saucony gained traction across Europe, China and Japan, while Merrell advanced in Europe and key Asia-Pacific (APAC) markets. Wolverine achieved double-digit international partner growth for Sweaty Betty across Europe and APAC. This broad-based progress strengthens Wolverine’s global platform and supports its upgraded fiscal 2026 outlook.
ONON’s Price Performance, Valuation & Estimates
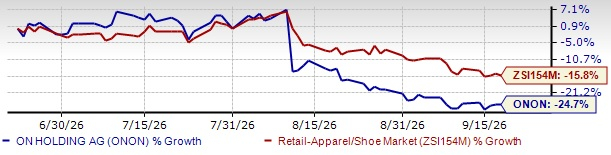
On Holding’s shares have lost 24.7% over the past three months compared with the industry’s 15.8% decline.
Image Source: Zacks Investment Research
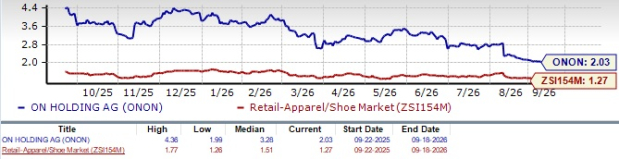
From a valuation standpoint, ONON trades at a trailing price-to-sales ratio of 2.03, above the industry’s average of 1.27. It has a Value Score of A.
Image Source: Zacks Investment Research
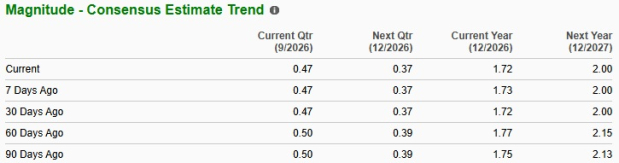
The Zacks Consensus Estimate for ONON’s fiscal 2026 earnings implies year-over-year growth of 77.3%, whereas the same for fiscal 2027 indicates an uptick of 16.1%. Estimates for fiscal 2026 have been revised downward by 5 cents, while those for fiscal 2027 have been revised downward by 15 cents over the past 60 days.
Image Source: Zacks Investment Research
On Holding currently carries a Zacks Rank #5 (Strong Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
On Holding AG (ONON): Free Stock Analysis Report
Deckers Outdoor Corporation (DECK): Free Stock Analysis Report
Wolverine World Wide, Inc. (WWW): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).