

CDW Corporation CDW has stepped up capital returns in 2026, with share repurchases gaining notable momentum even as free cash flow (FCF) conversion remained below its historical framework during the first half. In the second quarter, the company returned $344 million to shareholders through buybacks and another $80 million through dividends.
First-half repurchases totaled approximately $545 million, already approaching the $653 million deployed during all of 2025 and exceeding the $500 million repurchased in each of 2023 and 2024. Including dividends, CDW returned $706 million to shareholders during the first half of 2026. The company also added $1 billion to its share repurchase authorization during the quarter, leaving more than $1.1 billion of remaining capacity and providing considerable flexibility for further buybacks.
The sustainability of this faster capital-return pace will partly depend on a recovery in cash generation. Adjusted free cash flow was $278 million in the first half, representing 42% of non-GAAP net income and falling below management’s long-term rule of thumb of converting 80-90% of non-GAAP net income into cash.
On the last earnings call, management attributed the shortfall primarily to working-capital timing as CDW invested to support hardware-driven growth and customer demand amid elevated pricing. Inventory increased by roughly $400 million from year-end, but management expects to rationalize inventory as supply conditions become more normalized, making inventory reduction the biggest variable behind an anticipated improvement in second-half free cash flow.
CDW’s balance sheet also provides some support for continued shareholder distributions. Net leverage ended the quarter at 2.5X, comfortably within management’s 2X-3X target range, while liquidity was $2 billion. The company continues to target a dividend payout of roughly 25% of non-GAAP net income and remains active in evaluating acquisitions that broaden its capabilities and customer relevance.
Meanwhile, Geared for Growth initiatives are expected to improve expense efficiency and operating leverage during the second half and into 2027, potentially strengthening future investment and capital-deployment capacity.
Taking a Look at CDW’s Competitors
ServiceNow NOW generated $2.257 billion of operating cash flow in the first half of 2026 and continues to target a 35% FCF margin for 2026. The company also expects around $500 million in internal AI efficiency savings this year, supporting cash generation while keeping headcount flat despite acquisitions. TTM cash flow conversion is 317.8%, above its 276.5% median, while FCF conversion is 274.3%, also above its 242.4% median. Strong cash conversion supports reinvestment and acquisition funding. However, the company’s cash flow includes substantial stock-based compensation and acquisition spending, which should be monitored.
Accenture plc ACN continues to generate strong cash flow while returning capital to shareholders. In the fiscal third quarter of 2026, operating cash flow rose to $3.79 billion, while free cash flow increased to $3.60 billion. The company repurchased or redeemed 6 million shares for $1.2 billion and paid $1 billion in dividends, or $1.63 per share, reflecting a 10% increase. Accenture ended the quarter with $10.2 billion in cash, while $3.2 billion remained under its share repurchase authorization. For fiscal 2026, operating cash flow is expected at $11.5-$12.2 billion and FCF at $10.8-$11.5 billion.
CDW Price Performance, Valuation and Estimates
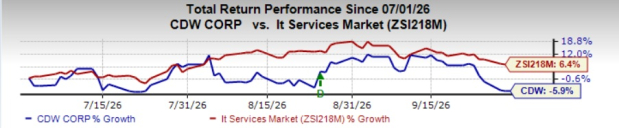
Shares of CDW have lost 5.9% in the past three months against the Computers - IT Services industry’s growth of 6.4%.
Image Source: Zacks Investment Research
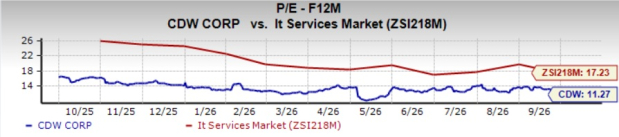
CDW trades at a forward 12-month price-to-earnings (P/E) ratio of 11.27, below the industry’s 17.23.
Image Source: Zacks Investment Research
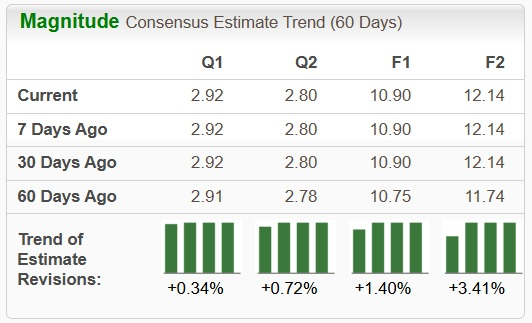
The Zacks Consensus Estimate for CDW’s earnings for 2026 has been revised marginally upward over the past 60 days.
Image Source: Zacks Investment Research
CDW currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
CDW Corporation (CDW): Free Stock Analysis Report
Accenture PLC (ACN): Free Stock Analysis Report
ServiceNow, Inc. (NOW): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).