

Texas Instruments Incorporated TXN is nearing the payoff phase of its long-term 300mm manufacturing investment, which could provide a structural lift to margins as factory utilization improves. The company claims 300mm production costs about 40% less per chip than production on 200mm wafers. This will give TXN a meaningful cost advantage as more output shifts to larger wafers. Texas Instruments’ six-year elevated capital expenditure cycle for its 300mm wafer fabs will conclude in 2026.
The strategy is already supporting financial performance. In the second quarter of 2026, Texas Instruments reported $5.46 billion in revenues, up 23% year over year, while gross profit increased 30% to $3.35 billion. Gross margin reached 61.4%, up 350 basis points from 57.9% in the year-ago quarter.
Management also credited the benefits of 300mm production as a factor supporting its strong cash generation. The company generated free cash flow of $2.74 billion in the second quarter, up from $1.33 billion in the year-ago quarter. Trailing 12-month free cash flow reached $6.53 billion in the second quarter of 2026, up 271% from $1.76 billion in the year-ago period.
Higher factory utilization could provide another margin boost. As much of TXN’s manufacturing cost is fixed, stronger production spreads those costs over more chips. Management expects to equip its existing clean-room capacity based on customer demand, allowing it to increase output without immediately taking on the full cost of building new facilities.
TXN is entering this phase with lower capital spending requirements. The company expects 2026 capital expenditures of $2-$3 billion, down from $4.55 billion in 2025.
As 300mm capacity ramps up and utilization rises, TXN could benefit from lower unit costs, better operating leverage and stronger free cash flow. However, the pace of margin expansion will depend on demand and how quickly the new facilities reach efficient utilization.
What TXN’s Rivals Are Doing to Improve Manufacturing Margins
Texas Instruments’ major competitors, Analog Devices, Inc. ADI and ON Semiconductor Corporation ON, have different strategies to improve manufacturing margins.
Analog Devices is enhancing its manufacturing margins by executing a multi-pronged strategy centered around a hybrid manufacturing model, strategic price increases and optimized asset utilization. With the hybrid manufacturing model, ADI can swiftly pivot production based on demand without incurring heavy capital expenditures. The strategy helps the company protect margins from the fixed-cost burdens of overbuilding factories and supports high free cash flow conversion.
In the third quarter of fiscal 2026, Analog Devices’ revenues increased 40% year-over-year to $4.02 billion, while non-GAAP gross profit jumped 46% to $2.92 billion. Non-GAAP gross margin reached 72.5%, up 330 basis points from 69.2% in the year-ago quarter. Its trailing 12-month free cash flow reached $4.94 billion in the third quarter, up 34% from $3.68 billion in the year-ago period.
ON Semiconductor is taking a more direct approach to manufacturing efficiency through its Fab Right strategy. The company is consolidating its manufacturing footprint and expanding 300mm capacity while exiting less efficient facilities. ON claims that its streamlined fabrication footprint could operate at about 17% lower cost at full utilization.
ON Semiconductor’s non-GAAP gross margin improved 80 basis points sequentially to 39.3% in second-quarter 2026, while manufacturing utilization rose to 83% from 77%. Management expects sequential gross margin expansion through 2026 and guided third-quarter non-GAAP gross margin to 40%-42% on revenues of $1.65-$1.75 billion. The planned Mountain Top and Philippines facility divestitures are expected to generate about $35 million of annualized savings, with benefits beginning in 2027 and fully realized in 2028. Management forecasts these actions represent roughly 50 basis points of the planned 200 basis points of gross margin improvement from Fab Right initiatives.
TXN’s Price Performance, Valuation and Estimates
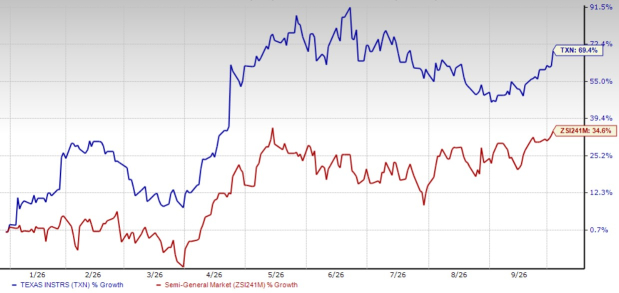
Shares of Texas Instruments have surged 69.4% year to date compared with the Zacks Semiconductor - General industry’s 34.6% growth.
Texas Instruments YTD Price Return Performance
Image Source: Zacks Investment Research
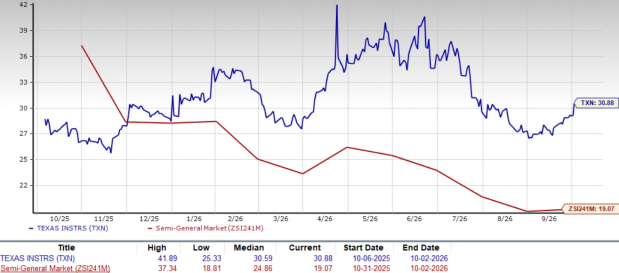
From a valuation standpoint, TXN trades at a forward price-to-earnings ratio of 30.88, significantly higher than the industry’s average of 19.07.
Texas Instruments Forward 12-Month P/E Ratio
Image Source: Zacks Investment Research
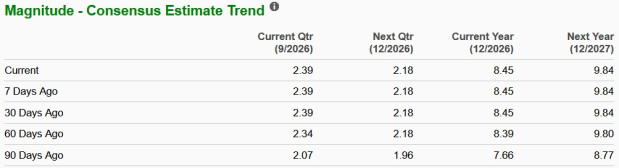
The Zacks Consensus Estimate for Texas Instruments’ 2026 and 2027 earnings implies a year-over-year increase of 55.1% and 16.5%, respectively. Estimates for 2026 and 2027 have been revised upward over the past 60 days.
Image Source: Zacks Investment Research
Texas Instruments currently carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Texas Instruments Incorporated (TXN): Free Stock Analysis Report
Analog Devices, Inc. (ADI): Free Stock Analysis Report
ON Semiconductor Corporation (ON): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).