

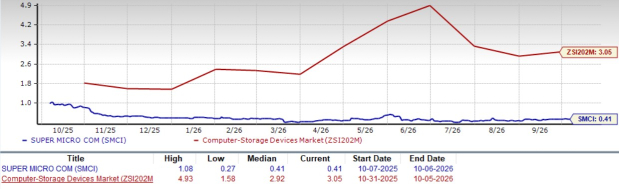
Super Micro Computer SMCI is trading at a discount at a forward 12 Month P/S multiple of 0.41X compared with the industry’s P/S multiple of 3.05X.
SMCI Forward 12-Month (P/S) Valuation Chart
Image Source: Zacks Investment Research
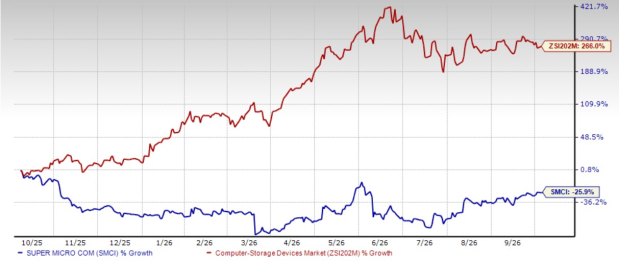
The discounted valuation is due to a decline of 25.9% in SMCI’s stock price in the past year, underperforming the Zacks Computer- Storage Devices industry’s appreciation of 266%.
SMCI YTD Performance Chart
Image Source: Zacks Investment Research
Given these dynamics, investors are wondering if it is the right time to buy, sell or hold SMCI stock. Let’s delve deeper into the fundamentals, growth drivers, competitive positioning, valuation and risks surrounding the company to better assess its long-term investment potential.
Global AI Infrastructure Expansion Fuels SMCI
Super Micro Computer remains positioned to benefit from expanding AI infrastructure demand, supported by rapid adoption of new GPU platforms, its modular Building Block architecture, liquid-cooling expertise and a broader Data Center Building Block Systems (DCBBS) offering. Record fiscal 2026 revenues and a large order pipeline support management’s fiscal 2027 sales outlook. SMCI’s fiscal 2026 revenues rose 78% to $39.1 billion, and management said more than $60 billion of new orders were received during the fourth quarter.
The company is benefiting from its emphasis on early availability of new AI systems as a competitive advantage. In fourth-quarter fiscal 2026, the company was shipping volume products across NVIDIA’s GB300 NVL72, HGX B300, B200 NVL4 and RTX 6000 Pro lines. It is also preparing systems based on NVIDIA Vera Rubin and Vera CPU platforms. With AMD, Super Micro Computer launched the Helios product line and MI450 Total Solution while continuing to support MI350 and MI355X systems.
Super Micro Computer is adding enterprise and channel customers. Enterprise and channel revenues represented 31% of fiscal 2026 sales and increased 39% year over year. In fourth-quarter fiscal 2026, the category accounted for 50% of revenue compared with 28% in the prior quarter, as customers upgraded compute, storage and networking infrastructure. The company also increased the number of customers generating more than $1 billion of annual revenues to nine in fiscal 2026 from four in fiscal 2025.
SMCI’s DCBBS and DLC Fuel its Growth
SMCI is positioning itself as a one-stop provider for the infrastructure required to build and operate AI factories and modern data centers with its DCBBS that combines rack-scale systems, networking, power, cooling, software and deployment services into an integrated solution. This approach can simplify data center construction and help customers accelerate the deployment of increasingly power- and cooling-intensive AI infrastructure.
The portfolio includes liquid-cooling solutions, such as in-rack coolant distribution units (CDUs), chilled doors and cooling towers. The company says its in-rack CDUs can support cooling capacity of up to 250 kilowatts, while cooling towers can support between 1 and 50 megawatts. Such capabilities are increasingly important as high-performance AI systems generate substantially more heat than conventional computing workloads.
DCBBS also includes 400G/800G networking solutions, power shelves capable of providing up to 33 kilowatts per shelf, battery backup systems and generators. On the software side, Supermicro offers tools, including SuperCloud Composer, SuperCloud Automation Center, SuperCloud Developer Console and SuperCloud Director. The company also provides planning, validation, onsite deployment, support and build/retrofit services, creating an integrated ecosystem around its hardware portfolio.
SMCI’s Modular Architecture Driving Continued Relevance
Despite SMCI’s extraordinary growth trajectory, competitive pressure, working capital strain and regulatory risks remain key concerns for the company. SMCI remains highly dependent on AI infrastructure spending cycles. Competition with giants like Hewlett Packard Enterprise HPE, Dell Technologies DELL and Cisco CSCO remains meaningful. Hewlett Packard Enterprise is providing enterprises with an integrated AI infrastructure portfolio spanning hardware, software and cloud management.
Hewlett Packard Enterprise combines compute, storage, networking and the GreenLake platform with NVIDIA's GPUs, CPUs, networking technologies and AI Enterprise software. Dell Technologies, meanwhile, is pursuing a broader ecosystem strategy through its Dell AI Factory. Rather than focusing solely on servers, Dell is expanding across compute, storage, networking, automation and software. Dell recently introduced PowerEdge R9822 and M9822 servers.
Cisco Systems is the undisputed king of the networking space with its offerings covering a full-stack portfolio of switching, routing, wireless, servers, software and SaaS services designed to support on-prem, cloud-managed and hybrid systems. Nevertheless, SMCI is a leader in modular architecture, which allows it to serve a diverse customer base and their unique needs. Although its profitability continues to vary sharply with customer and product mix.
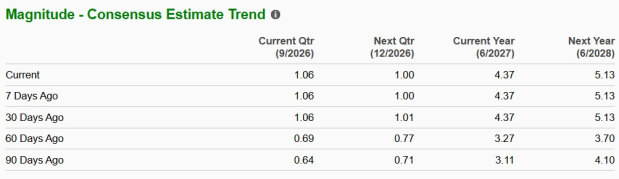
The Zacks Consensus Estimate for SMCI’s fiscal 2027 earnings is pegged at $4.37 per share, suggesting year-over-year growth of 20.4%. Estimates remained unchanged for the past 30 days.
Image Source: Zacks Investment Research
Conclusion: Buy SMCI Stock Now
SMCI’s discounted valuation, strong AI infrastructure demand and modular architecture provide a compelling long-term growth opportunity. Its expanding customer base, liquid-cooling expertise and integrated DCBBS portfolio further strengthen its competitive position. While execution, competition and margin volatility remain risks, the company’s growth prospects support a Buy rating for investors seeking AI infrastructure exposure. SMCI carries a Zacks Rank #2 (Buy) at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Super Micro Computer, Inc. (SMCI): Free Stock Analysis Report
Cisco Systems, Inc. (CSCO): Free Stock Analysis Report
Dell Technologies Inc. (DELL): Free Stock Analysis Report
Hewlett Packard Enterprise Company (HPE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).