

FIGS, Inc. FIGS is pairing its premium apparel positioning with a greater emphasis on full-price sales. Pricing changes introduced early in 2026 reduced discounting and lower return rates supported sales quality in the second quarter. Management reported positive customer feedback on fit improvements, suggesting that product execution is complementing the company’s efforts to strengthen price realization.
Average order value reached a record $127, up approximately 9% year over year. Management attributed the increase partly to higher average unit retail following first-quarter pricing actions, with lower discounts and improved returns contributing further. The gain was not primarily driven by more units per transaction, making pricing and reduced promotional activity central to the improvement.
Customer demand remained strong alongside these developments. Active customers increased approximately 13% to 3.1 million and purchase frequency improved. Trailing 12-month net revenues per active customer reached a record $229, exceeding the pandemic-era peak of $227. Higher orders and average order value helped drive a 28.8% increase in quarterly revenues to $196.6 million.
Assortment expansion added to the momentum. Scrubwear revenues grew about 27%, while non-scrubwear sales increased 40%, with strength across underscrubs, outerwear and accessories. Pricing and efficiency gains also helped counter higher tariffs. However, tariff refunds contributed 780 basis points of the 820-basis-point gross-margin increase to 75.2%, underscoring the distinction between underlying improvements and the refund benefit.
FIGS raised its 2026 revenue growth outlook to approximately 20% and adjusted EBITDA margin guidance to 14.8-15%. The margin outlook includes tariff refund benefits associated with current-year costs. Planned air freight spending could offset some gains, leaving sustained customer engagement, lower discounting and operational efficiency important to maintaining profitability as the company pursues further growth.
FIGS’ Price Performance, Valuation & Estimates
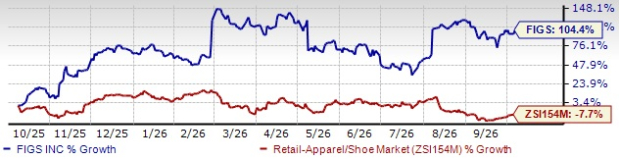
Shares of FIGS have skyrocketed 104.4% over the past year against the industry’s 7.7% decline.
Image Source: Zacks Investment Research
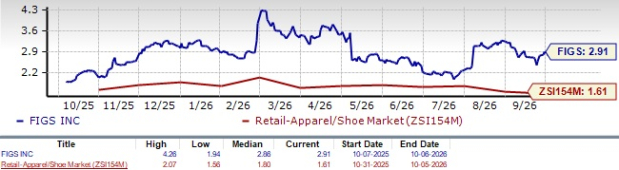
From a valuation standpoint, FIGS trades at a forward price-to-sales ratio of 2.91, above the industry’s average of 1.61. It has a Value Score of B.
Image Source: Zacks Investment Research
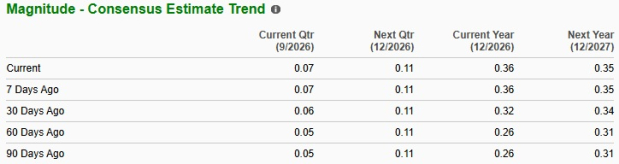
The Zacks Consensus Estimate for FIGS’ 2026 earnings implies year-over-year growth of 89.5%, while the same for 2027 indicates a decline of 1.9%. Estimates for 2026 and 2027 have been revised upward by 4 cents and 1 cent, respectively, over the past 30 days.
Image Source: Zacks Investment Research
FIGS currently carries a Zacks Rank #2 (Buy).
Other Key Picks
Genesco Inc. GCO is a Nashville-based specialty retailer and branded company. It sells footwear and accessories through retail stores. The company sports a Zacks Rank #1 (Strong Buy) at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Genesco’s current fiscal-year earnings indicates 62.1% growth from the year-ago actual. GCO delivered a trailing four-quarter average earnings surprise of 11.2%.
Designer Brands Inc. DBI designs, produces and retails footwear and accessories. It offers shoes, boots, sandals, sneakers, socks, handbags and accessories. It currently carries a Zacks Rank #2.
The Zacks Consensus Estimate for Designer Brands’ current fiscal-year earnings and sales implies growth of 225% and 0.6%, respectively, from the year-ago actuals. DBI delivered a trailing four-quarter average earnings surprise of 108.1%.
Urban Outfitters, Inc. URBN is a lifestyle products and services company that sells fashion apparel, accessories, footwear, home goods and related offerings through a portfolio of global consumer brands. The company carries a Zacks Rank of 2 at present.
The Zacks Consensus Estimate for Urban Outfitters’ current fiscal-year earnings and sales indicates growth of 14% and 9.5%, respectively, from the year-ago actuals. URBN delivered a trailing four-quarter average earnings surprise of 9.7%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
FIGS, Inc. (FIGS): Free Stock Analysis Report
Urban Outfitters, Inc. (URBN): Free Stock Analysis Report
Genesco Inc. (GCO): Free Stock Analysis Report
Designer Brands Inc. (DBI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).