

Willis Towers Watson Public Limited Company WTW appears capable of sustaining more than 5% organic growth, but maintaining that pace will depend heavily on Risk & Broking and the company’s ability to offset softer insurance pricing.
WTW’s organic growth remains a key strength, with organic revenue growth reaching 5% in the second quarter of 2026, supported by solid momentum across both major businesses. The biggest support is WTW’s specialization strategy. Although insurance rates continued to decline across most lines, WTW said its specialty offerings are helping it grow through the cycle.
Risk & Broking led the performance with 7% organic growth, driven by new business, strong client retention and double-digit growth across most specialty businesses, while Health, Wealth & Career delivered 4% growth, led by an 8% increase in Health. Insurance Consulting & Technology also grew 6%, helped by software sales and new business wins.
The sustainability of this growth will depend on whether WTW can continue gaining business despite declining insurance rates across most lines. Its specialization strategy, broad specialty offerings, client retention and technology-based solutions provide important offsets to softer pricing. Management continues to expect mid-single-digit organic growth in Risk & Broking and HWC for 2026, suggesting that 5% growth is achievable, although maintaining this pace will require continued new-business wins and strong execution.
However, sustaining 5%+ growth could become more challenging. HWC grew only 4% organically in the second quarter, with Career flat, while R&B's acceleration partly reflected activity that had been delayed earlier in the year. WTW itself continues to guide for mid-single-digit organic growth in both major segments for 2026, suggesting that 5% is achievable but not necessarily a new baseline above that level.
What About Its Peers?
Brown & Brown, Inc. BRO experienced a moderation in organic growth in the second quarter of 2026, reflecting a softer insurance pricing environment and weakness in its Specialty Distribution business. Organic revenues declined 0.7% year over year, while organic revenues, including contingent commissions, increased 0.7%. Despite the near-term pressure, BRO expects organic growth to improve in the second half of 2026, with management targeting 1.5-2.5% growth in Retail and 2-4% in Specialty Distribution, excluding contingents.
Arthur J. Gallagher & Co. AJG appears well positioned to sustain around 6% organic growth and continue expanding underlying margins even as insurance pricing moderates. AJG witnessed another solid quarter of organic growth across each business and geography. The bigger drivers of Organic growth remain new business, strong client retention, exposure growth and the diversity of the model across P/C, benefits, reinsurance and claims. AJG is also gaining from activity across construction, infrastructure, energy and data centers. AJG projects a total company organic outlook of 6%, brokerage at 5.5% and risk management at 9% for 2026. AJG expects 2026 will be another year of excellent organic growth.
WTW’s Price Performance
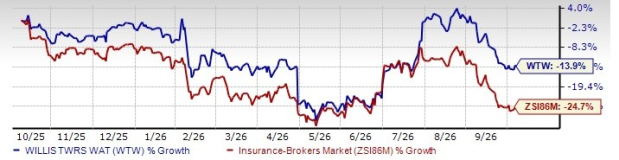
Shares of WTW have lost 13.9% in the past year compared with the industry’s decline of 24.7%.
Image Source: Zacks Investment Research
WTW’s Undervaluation
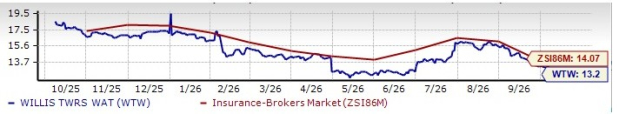
The stock is undervalued compared with its industry. It is currently trading at a price-to-earnings multiple of 13.2, lower than the industry average of 14.07.
Image Source: Zacks Investment Research
Estimate Movement for WTW
The Zacks Consensus Estimate for WTW’s third-quarter 2026 and fourth-quarter 2026 EPS has moved down 0.9% and 0.2%, respectively, in the past 30 days. The same for full-year 2026 and 2027 EPS has moved down 0.1% and 0.08%, respectively, in the past 30 days.
Image Source: Zacks Investment Research
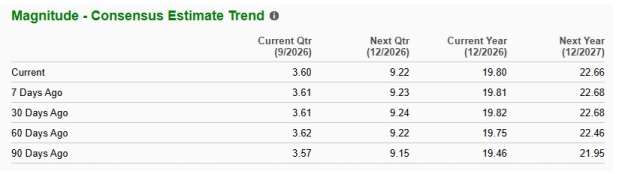
The consensus estimate for WTW’s 2026 and 2027 EPS and revenues indicates a year-over-year increase.
WTW stock currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Willis Towers Watson Public Limited Company (WTW): Free Stock Analysis Report
Arthur J. Gallagher & Co. (AJG): Free Stock Analysis Report
Brown & Brown, Inc. (BRO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).