

As Crocs, Inc. CROX prepares to unveil its third-quarter fiscal 2026 results on Oct. 29, before market open, investors are eager to see whether the company can beat market expectations.
The Zacks Consensus Estimate for revenues is pegged at $1 billion, implying 0.9% growth from the prior year. Meanwhile, the consensus mark for earnings has been steady at $3.31 per share in the past seven days, though it indicates growth of 13.4% from the year-ago period. CROX has a trailing four-quarter earnings surprise of 13.6%, on average.
Crocs, Inc. Price, Consensus and EPS Surprise
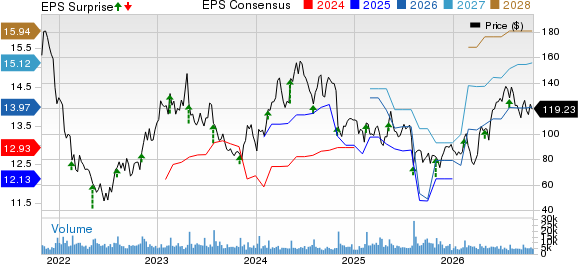
Crocs, Inc. price-consensus-eps-surprise-chart | Crocs, Inc. Quote
Key Factors to Note for CROX's Q3 Earnings
Crocs’ third-quarter fiscal 2026 performance is likely to have benefited from continued strength in direct-to-consumer (DTC) sales across both brands. The Crocs brand benefited from higher DTC sales alongside reduced promotional activity, while HEYDUDE also delivered growth despite lower performance marketing spending. These trends are likely to have reflected sustained consumer demand and effective brand engagement. In addition, the halo effect from social media promotions, particularly TikTok content featuring popular styles and creators, might have supported sales across marketplaces, the company’s websites and retail stores, further strengthening overall DTC momentum.
The company’s focus on strengthening global brand relevance is also likely to have remained a positive contributor. As the market leader in clogs, Crocs continues to diversify its clog portfolio through differentiated product franchises that enable better consumer segmentation and expand category relevance beyond its classic offerings. These initiatives might have supported continued consumer engagement and reinforced the company’s competitive positioning during the quarter.
Consumer engagement initiatives are likely to have provided an additional tailwind. The company’s Glad You Noticed campaign, launched in April, leveraged creative partnerships and an integrated media strategy to highlight its sandal business. The campaign was previously identified as a key driver of category momentum, suggesting that continued traction from socially driven storytelling and targeted marketing might have supported sandal demand and overall brand performance during the quarter.
That said, the company is likely to have faced cost headwinds from tariff-related uncertainty.
What the Zacks Model Says About CROX
Our proven model predicts an earnings beat for CROX this time. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is the case here.
CROX has an Earnings ESP of +0.60% and a Zacks Rank #2. You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
Other Stocks With Favorable Combination
Here are three other companies you may also want to consider, as our model shows that these too have the right combination of elements to post an earnings beat this season:
Ralph Lauren Corporation RL currently has an Earnings ESP of +0.56% and a Zacks Rank of 2. The Zacks Consensus Estimate for second-quarter fiscal 2027 earnings per share is pegged at $4.22, implying 11.4% year-over-year growth. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for quarterly revenues is pegged at $2.1 billion, which indicates growth of 6.1% from the figure reported in the prior-year quarter. RL has a trailing four-quarter earnings surprise of 8.7%, on average.
Cintas Corporation CTAS currently has an Earnings ESP of +0.24% and a Zacks Rank of 3. The Zacks Consensus Estimate for second-quarter 2027 earnings per share is pegged at $1.36, implying 12.4% year-over-year growth.
The Zacks Consensus Estimate for quarterly revenues is pegged at $3 billion, which indicates an increase of nearly 8% from the figure reported in the prior-year quarter. CTAS has a trailing four-quarter earnings surprise of 2.4%, on average.
V.F. Corporation VFC currently has an Earnings ESP of +0.80% and a Zacks Rank of 3. The Zacks Consensus Estimate for second-quarter fiscal 2027 earnings per share is pegged at 54 cents, implying a 3.9% year-over-year increase.
The Zacks Consensus Estimate for quarterly revenues is pegged at $2.7 billion, which indicates a decrease of 3.9% from the figure reported in the prior-year quarter. VFC has a trailing four-quarter earnings surprise of roughly 34%, on average.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Crocs, Inc. (CROX): Free Stock Analysis Report
V.F. Corporation (VFC): Free Stock Analysis Report
Cintas Corporation (CTAS): Free Stock Analysis Report
Ralph Lauren Corporation (RL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).