

EuroDry (EDRY), which operates in the dry cargo and dry bulk shipping markets, is benefiting from a stronger dry bulk market. Favorable spot rate forecasts for the global dry bulk market are likely to support the company’s top line.
EuroDry was formed on Jan. 8, 2018, to bring the dry bulk fleet of Euroseas Ltd. ESEA under a separate publicly traded company. Euroseas completed the spin-off of its dry bulk fleet into a separate publicly traded company, EuroDry Ltd., on May 30, 2018.
Given this dry bulk market strength, the question that naturally arises is whether investors should buy EDRY stock at current prices. Let us dig deeper to find out.
How Dry Bulk Market Strength Is Aiding EDRY
Robust global dry bulk trade, including demand for iron ore, bauxite and coal, helped EuroDry’s average Time Charter Equivalent (“TCE”) rate more than double year over year to $20,398 per day in the second quarter of 2026. As a result, revenues rose 57% to $17.7 million, despite the company operating fewer vessels.
Average TCE rate measures the average daily net revenues generated by the company’s vessels. EDRY calculates this metric by dividing time charter revenues and voyage charter revenues, if any, after deducting voyage expenses, by the number of voyage days during the applicable period.
Adjusted EBITDA increased to $11.7 million from $1.9 million. EuroDry also reported net income attributable to controlling shareholders of $6.6 million, in contrast to a loss of $3.1 million a year earlier. Demand for iron ore and bauxite shipments, longer voyage distances and geopolitical trade disruptions have tightened vessel availability and supported dry bulk rates.
EuroDry is positioned to benefit if market conditions remain strong. Several of its vessels operate under index-linked charters, allowing higher Supramax rates to flow through to revenues. Other charters were set to expire between August and November 2026, giving the company opportunities to renew them at prevailing rates. Forward freight agreements also pointed to elevated rates through the rest of 2026 and into 2027.
Near-full fleet utilization and relatively stable vessel operating expenses could further increase the earnings benefit from higher rates. In addition, the planned delivery of four vessels in 2027 and 2028 could expand EuroDry’s revenue-generating capacity if favorable dry bulk market conditions continue.
EDRY’s Fleet-Upgrade Efforts Bode Well
EuroDry is following a disciplined fleet-renewal approach, focused on acquiring larger and more fuel-efficient vessels while gradually phasing out older tonnage. The company currently operates a fleet of 11 vessels, comprising three Panamax dry bulk carriers, five Ultramax dry bulk carriers, two Kamsarmax dry bulk carriers and one Supramax dry bulk carrier.
EuroDry’s dry bulk fleet has an aggregate cargo-carrying capacity of 766,420 dwt. Following the scheduled delivery of two Ultramax vessels in 2027 and two Kamsarmax vessels in 2028, the fleet is expected to expand to 15 vessels with a combined carrying capacity of 1,050,420 dwt.
EDRY’s Upbeat Price Performance
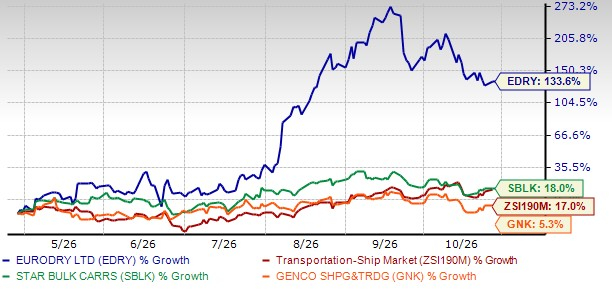
Shares of EDRY have gained in triple digits over the past six months. Courtesy of the upbeat performance, EDRY’s shares have outperformed the Zacks Transportation-Shipping industry and peers Star Bulk Carriers SBLK and Genco Shipping & Trading GNK over the same time frame.
6- Month Price Comparison
Strength in the dry-bulk market is translating into substantially higher charter rates and earnings for Star Bulk Carriers as well. Its average daily time-charter-equivalent rate surged 79.7% year over year to $24,486 in the second quarter of 2026. This lifted voyage revenues 44.5% to $357.4 million despite a reduction in the average fleet size. Robust freight rates are also strengthening Star Bulk’s cash generation and shareholder returns.
Genco Shipping & Trading is benefiting from higher rates across both its major and minor-bulk fleets. Its average daily fleet-wide time-charter-equivalent rate advanced 78.1% year over year in the second quarter of 2026. Voyage revenues at Genco Shipping & Trading increased 68.5% to $136.4 million, aided by stronger rates, a larger fleet and fewer dry-docking days. Adjusted EBITDA nearly quadrupled to $56.7 million, while adjusted net income reached $29.2 million against an adjusted loss of $6.2 million a year earlier.
Headwinds That Cannot Be Overlooked
EuroDry faces considerable operational uncertainty from geopolitical conflicts, trade disputes and disruptions along major shipping routes. The ongoing conflicts in the Middle East, particularly around the Strait of Hormuz, have increased risks for commercial vessels. Prolonged disruptions could increase insurance expenses, delay voyages and adversely affect operating efficiency.Top of Form
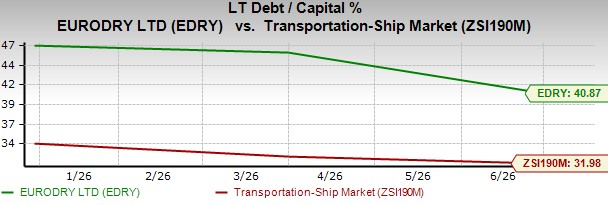
The shipping company's debt levels are expected to rise as it finances newbuildings, with scheduled repayments increasing in 2027 and beyond.
Moreover, EDRY’s earnings history is not very impressive, having surpassed the Zacks Consensus Estimate in two of the past four quarters, missing the mark in the other quarters. The average miss is 5.6%.
EuroDry Price and EPS Surprise
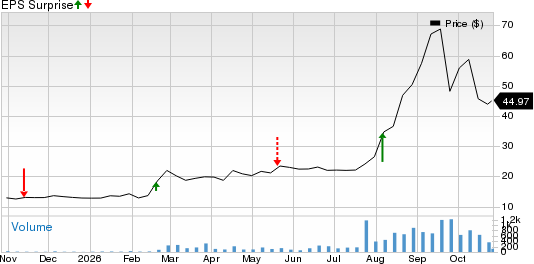
EuroDry price-eps-surprise | EuroDry Quote
While releasing its second-quarter 2026 results, EDRY’s management said that the global dry bulk order book has climbed to roughly 14.4% of the existing fleet, giving rise to concerns over future vessel oversupply and potential downward pressure on charter rates.
Don’t Buy EDRY Stock Now
Agreed that EuroDry is benefiting from the dry bulk market strength, apart from efforts to expand its fleet, but headwinds like the ongoing economic uncertainties and fears of charter rates going down due to oversupply of vessels remain bothersome.
As a result, we believe that new investors should prefer to wait for a better entry point. Those who already have this stock may stay invested, considering the tailwinds. EDRY currently has a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
EuroDry (EDRY): Free Stock Analysis Report
Genco Shipping & Trading Limited (GNK): Free Stock Analysis Report
Star Bulk Carriers Corp. (SBLK): Free Stock Analysis Report
Euroseas Ltd. (ESEA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).