

Flex Ltd. FLEX reported second-quarter fiscal 2027 adjusted earnings of $1.18 per share, up 49.4% year over year. The figure beat the Zacks Consensus Estimate of $1.05 by 12.38%.
Revenues increased 24.8% year over year to $8.49 billion, surpassing the consensus mark of $8.18 billion by 3.85%. Strong AI-related demand across Cloud and Power Infrastructure (CPI), along with growth in high-value markets, supported the results. Adjusted operating margin expanded 110 basis points (bps) to 7.1%.
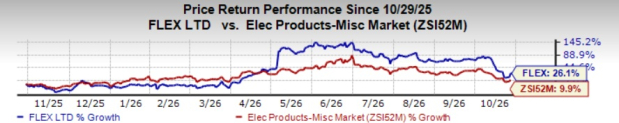
Shares of the company gained around 8% in the pre-market trading session today. In the past year, the stock has rallied 26.1% compared with the Zacks Electronics - Miscellaneous Products industry’s growth of 9.9%.
Image Source: Zacks Investment Research
FLEX Gains From Broad-Based Segment Growth
Regulated Manufacturing Solutions (RMS) revenues increased 9% year over year to $2.68 billion. Growth was supported by high-value markets, particularly Industrial, where energy infrastructure and robotics remained important demand drivers.
Integrated Technology Solutions (ITS) revenues climbed 22% to $3.31 billion. Communications benefited from strong AI-related demand for advanced networking infrastructure, while consumer-related Lifestyle markets experienced softness.
Cloud and Power Infrastructure revenues surged to $2.51 billion from $1.63 billion a year earlier. Growth across Power and Cloud & Cooling reflected continued data center investment and robust demand for critical infrastructure solutions.
Flex Sees Strong Profit Growth Across Segments
CPI-adjusted operating income jumped 97% year over year to $268 million. The segment's adjusted operating margin expanded 240 bps to 10.7%, reflecting favorable business mix and operating execution.
RMS adjusted operating income increased 19% to $172 million, with margin improving 50 bps to 6.4%. ITS adjusted operating income rose 26% to $181 million, while margin expanded 20 bps to 5.5%.
Corporate and Other expenses were $14 million compared with $15 million in the year-ago quarter. The improvements across all three operating segments supported consolidated profitability.
FLEX Expands Margins Despite Higher Expenses
Adjusted gross profit increased 33% year over year to $842 million. Adjusted gross margin expanded 60 bps to 9.9%, benefiting from productivity improvements and favorable business mix.
Adjusted operating income climbed 48% to $607 million from $409 million. GAAP operating income increased to $414 million from $296 million, while GAAP operating margin improved to 4.9% from 4.4%.
GAAP selling, general and administrative expenses rose to $371 million from $260 million. Legal and other adjustments totaled $110 million, including approximately $91 million related primarily to the planned CPI spin-off and $19 million in acquisition costs.
Flex Ltd. Price, Consensus and EPS Surprise
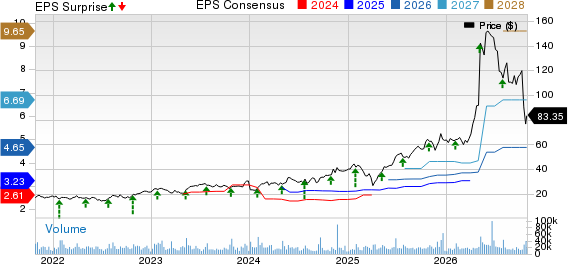
Flex Ltd. price-consensus-eps-surprise-chart | Flex Ltd. Quote
Flex Generates Solid Operating Cash Flow
Cash provided by operating activities increased to $501 million from $453 million in the year-ago quarter. Changes in working capital and other items contributed $82 million compared with $98 million previously.
Net capital expenditures totaled $240 million, leaving free cash flow of $261 million, down from $305 million a year earlier. Free cash flow included a $61 million negative impact from separation costs associated with the CPI spin-off.
FLEX's Balance Sheet Reflects Expansion
Cash and cash equivalents reached $3.08 billion as of Sept. 25, 2026, compared with $2.39 billion at fiscal 2026-end. Long-term debt increased to $5.21 billion from $3.75 billion over the same period.
Total assets rose to $27.38 billion from $22.06 billion. Inventories increased to $7.32 billion from $5.85 billion, while accounts receivable climbed to $5.78 billion from $4.68 billion.
Flex Issues Upbeat Q3 Guidance
For the third quarter of fiscal 2027, Flex expects revenues between $8.87 billion and $9.17 billion. Adjusted operating income is projected at $685-$715 million, with adjusted earnings of $1.19-$1.25 per share.
Management expects CPI revenues to grow 105-115% year over year. RMS revenues are projected to increase in the low-single to mid-single digits, while ITS revenues are expected to grow in the mid-single to high-single digits.
FLEX Raises Fiscal 2027 Outlook
Flex raised its fiscal 2027 revenue guidance to $34.9-$35.9 billion from $33.7-$35.2 billion. The adjusted operating margin outlook was increased to 7.6-7.8% from 7-7.2%.
Adjusted earnings guidance was raised to $4.84-$5.16 per share from $4.42-$4.74. Management expects CPI revenues to increase 75-85%, while RMS and ITS combined revenues are projected to grow 8-11%.
The updated outlook incorporates recent acquisitions, including EPC Power, which was completed on Oct. 14, 2026. Management continues to target a tax-free spin-off of CPI, operating under the Axiom name, during the first quarter of calendar 2027.
FLEX’s Zacks Rank
Flex currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Recent Performances
Progress Software Corporation PRGS reported third-quarter fiscal 2026 results wherein revenues came in at $246 million, down 2% year over year and on a constant currency (cc) basis. ARR of $873 million inched up 1% year over year on a cc basis. Progress Software Corporation reported a 13% year-over-year increase in non-GAAP earnings per share, which stood at $1.69.
Shares of Progress Software Corporation have increased 6.4% in the past year.
Synopsys, Inc SNPS reported third-quarter fiscal 2026 non-GAAP earnings of $3.91 per share, which increased 15.3% year over year and beat the Zacks Consensus Estimate by 6.5%. Broad-based strength, led by EDA and Ansys, supported the earnings outperformance.
Revenues for Synopsys rose 42.4% year over year to $2.48 billion, topping the consensus mark by 1.7%. Backlog remained strong at $10.9 billion, while Design IP returned to year-over-year growth.
Shares of Synopsys have gained 4.2% in the past year.
Oracle ORCL reported first-quarter fiscal 2027 non-GAAP earnings of $1.92 per share, which beat the Zacks Consensus Estimate by 10.3% and increased 30% in dollar terms and 30% in cc on a year-over-year basis.
Total quarterly revenues increased 30% year over year to $19.3 billion, which beat the consensus mark by 1.11%, reflecting strong demand for Oracle's cloud infrastructure and applications suites, particularly from AI-focused enterprises.
Shares of Oracle have lost 52.6% in the past year.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Flex Ltd. (FLEX): Free Stock Analysis Report
Oracle Corporation (ORCL): Free Stock Analysis Report
Synopsys, Inc. (SNPS): Free Stock Analysis Report
Progress Software Corporation (PRGS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).