

Navitas Semiconductor NVTS and Semtech Corporation SMTC are semiconductor companies developing technologies that support next-generation electronics and connectivity. NVTS specializes in gallium nitride (GaN) and silicon carbide (SiC) power semiconductors for applications such as AI data centers, fast charging and energy systems. Semtech focuses on analog and mixed-signal semiconductors, high-speed connectivity and IoT technologies.
Both NVTS and SMTC are well-positioned to benefit from long-term growth in data centers and advanced technology infrastructure. However, from an investment point of view, one stock offers a more favorable outlook than the other right now. Let’s break down their fundamentals, growth prospects, market challenges and valuation to determine which stock offers a more compelling investment case.
The Case for Navitas Semiconductor Stock
Navitas Semiconductor is positioning itself to benefit from the growing power needs of AI data centers. The company is focusing on high-power applications using its GaN and SiC technologies. In the second quarter of 2026, total revenues increased 22% sequentially, while high-power markets grew more than 50% year over year. NVTS expects AI infrastructure to account for more than one-third of its total sales by the end of 2026.
The transition to 800V is expected to create several growth opportunities for NVTS. The company sees the first stage already taking place, with higher-power AC/DC power supplies increasingly using SiC as data center racks demand greater power and density. The next stage is the adoption of 800V through power sidecar racks, which is expected to ramp in 2027. Later stages could bring 800V directly to GPU and XPU trays, increasing the use of GaN for high-frequency DC/DC conversion. NVTS expects these developments to happen in steps across multiple platforms and customers rather than through a single rollout.
NVTS is already working with hyperscalers, data centers, OEMs and ODMs on programs that are expected to ramp in the second half of 2026 and accelerate in 2027. The company is also seeing traction in DC/DC power supplies and battery backup units, where both GaN and SiC are being designed in. This is supporting strong growth in NVTS’ AI infrastructure revenues, which have increased more than 50% sequentially in both the first and second quarters of 2026, with growth expected to accelerate as more programs move toward production.
However, NVTS’ “Navitas 2.0” strategy involves moving away from mobile charging and consumer electronics toward higher-power AI and industrial markets. While this may improve long-term growth, it also introduces meaningful near-term revenue volatility. The company is effectively walking away from markets where it already had product traction and revenue history in exchange for newer markets with longer design cycles and more demanding qualification requirements. This transition could create revenue volatility over the next several quarters.
The Case for Semtech Stock
Semtech is seeing strong demand for its data center products as hyperscalers increase spending on AI infrastructure. The company’s data center revenues reached a record $100 million in the second quarter of fiscal 2027, up 39% sequentially and 91% year over year. Growth was driven by continued strength in 800G products, along with the ramp of 1.6T CopperEdge and FiberEdge solutions. Management expects this momentum to continue, with data center revenues projected to increase 45% sequentially and 160% year over year in the third quarter of fiscal 2027.
The 1.6T transition could become an important growth driver for Semtech. Management expects 1.6T FiberEdge and CopperEdge products to account for more than 50% of total data center revenues in the third quarter of fiscal 2027. Semtech is also gaining market share in optical connectivity, where its FiberEdge business has grown from about 18% market share in 800G two years ago to more than 50%. Further, the company expects its 1.6T FiberEdge market share to exceed 50% by the end of fiscal 2027.
The company is also preparing for the next stage of data center growth. Semtech is expanding its photonics portfolio through gain chips, high-power CW lasers, semiconductor optical amplifiers and photodiodes. These products are aimed at higher-speed applications, including 3.2T transceivers and co-packaged optics. Management expects its content per transceiver to increase from high single-digit dollars to high double-digit dollars as data center speeds move from 800G to 3.2T.
Strong customer demand supports SMTC’s prospects as well, with the company reporting that its backlog for the remainder of fiscal 2027 was fully booked and more than 70% of its target for fiscal 2028 was already covered. Management is also working with manufacturing partners to secure additional capacity for fiscal 2028 and beyond. If it can meet customer requirements and maintain its product momentum, the 1.6T ramp could remain an important driver of Semtech’s data center growth over the next several quarters.
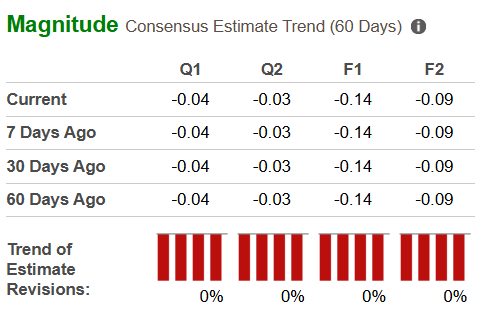
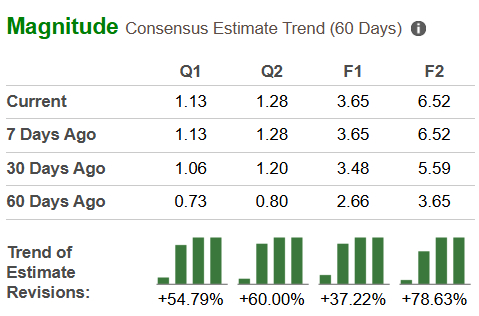
NVTS vs. SMTC: Earnings Estimate Trend
The earnings estimate revision trend for the two companies reflects that analysts are turning more bullish toward SMTC.
NVTS Earnings Estimate Revision Trend
Image Source: Zacks Investment Research
SMTC Earnings Estimate Revision Trend
Image Source: Zacks Investment Research
NVTS vs. SMTC: Price Performance and Valuation
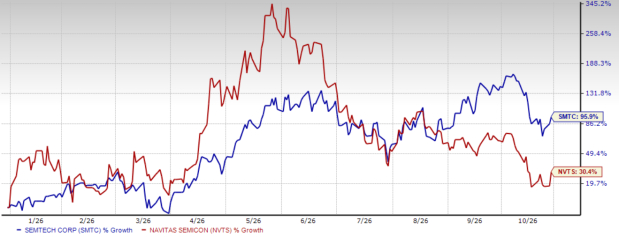
Year to date, shares of NVTS and SMTC have surged 30.4% and 95.9%, respectively.
NVTS Vs. SMTC: YTD Price Return Performance
Image Source: Zacks Investment Research
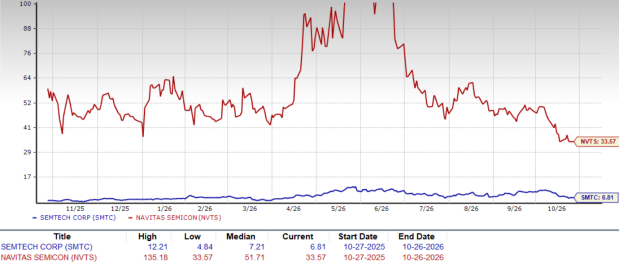
Currently, SMTC is trading at a forward sales multiple of 6.81X, significantly lower than NVTS’ forward sales multiple of 33.57X. SMTC’s reasonable valuation makes it more attractive for investors looking for value and stability.
NVTS vs. SMTC: Forward 12-Month P/S Ratio
Image Source: Zacks Investment Research
Conclusion: Buy SMTC, Hold NVTS Right Now
Navitas Semiconductor and SMTC are both set to ride the long-term growth in AI and data center markets, but their current positions are very different. Currently, NVTS faces near-term risks from its decision to deprioritize its lower-margin mobile and consumer business, which could create revenue volatility in the upcoming quarters.
In contrast, Semtech is seeing strong demand for AI data center products, with the ramp-up of 1.6T solutions driving revenue growth and a strong backlog supporting future demand. Further, SMTC’s reasonable valuation offers some downside protection as well, making the stock an attractive buy.
Currently, SMTC sports a Zacks Rank #1 (Strong Buy), giving a clear edge over NVTS, which carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Semtech Corporation (SMTC): Free Stock Analysis Report
Navitas Semiconductor Corporation (NVTS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).