

Sandisk SNDK is expected to have benefited from strong Data Center and Edge revenues in the first quarter of fiscal 2027, the results of which are scheduled to be released on Oct. 29, 2026. Click here to learn how SNDK’s overall fiscal fourth-quarter performance is likely to be.
SNDK’s Data Center Revenues to Ride on Strong AI Growth
Accelerating investments in artificial intelligence (AI) infrastructure, particularly inference and agentic AI workloads, are expected to have boosted demand for high-capacity enterprise solid-state drives (SSDs). The growing adoption of compute-focused TLC SSDs among hyperscale customers and initial shipments of its QLC-based Stargate platform are likely to have supported Datacenter revenues in the to-be-reported quarter. In the fourth quarter of fiscal 2026, Datacenter revenues surged 103% sequentially to $2.98 billion, reflecting strong customer demand and an improving product mix.
The Zacks Consensus Estimate for fiscal first-quarter Data Center revenues is pegged at $4.049 billion, indicating sequential growth of 36%.
Sandisk Corporation Revenue (TTM)
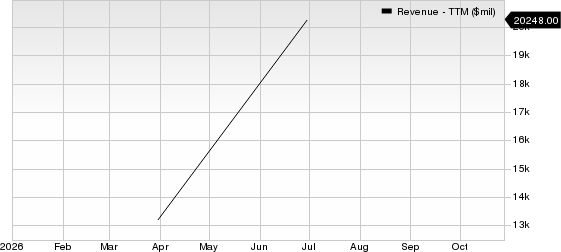
Sandisk Corporation revenue-ttm | Sandisk Corporation Quote
However, Sandisk is facing stiff competition from the likes of Micron Technology MU, Seagate STX and SK Hynix SKHY in the data center space. Micron poses a significant competitive threat to Sandisk in both the data center and edge markets through its expanding enterprise SSD portfolio and AI memory leadership. SK hynix is strengthening its position against Sandisk by rapidly expanding its enterprise SSD business alongside AI memory products. Seagate is emerging as a formidable competitor by promoting HDDs as an essential component of AI storage architectures rather than relying solely on flash.
SNDK’s Edge: AI PCs and Premium Smartphones to Drive Growth
Sandisk’s Edge revenues are likely to have benefited from increasing storage requirements in premium smartphones, PCs and other connected devices. The shift toward higher-end configurations and AI-enabled devices is expected to have supported NAND content growth despite ongoing adjustments in PC and smartphone demand. In the fourth quarter of fiscal 2026, Edge revenues jumped 48% sequentially to $5.43 billion.
Additionally, favorable pricing trends, constrained NAND supply and stronger customer commitments under Sandisk’s long-term New Business Model agreements are likely to have supported revenues and profitability in the to-be-reported quarter.
The Zacks Consensus Estimate for fiscal first-quarter Edge revenues is pegged at $6.138 billion, indicating sequential growth of 13%.
Zacks Rank
Sandisk currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Sandisk Corporation (SNDK): Free Stock Analysis Report
Seagate Technology Holdings PLC (STX): Free Stock Analysis Report
Micron Technology, Inc. (MU): Free Stock Analysis Report
SK Hynix, Inc. - Sponsored ADR (SKHY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).