

Innodata Inc. INOD and Accenture plc ACN are capitalizing on the accelerating adoption of artificial intelligence (AI), supported by rising enterprise investments in automation, advanced data engineering and digital transformation. Both companies are expanding their AI capabilities to address increasingly complex business requirements, although their operating models and growth strategies differ considerably.
While Innodata specializes in high-quality AI training datasets, model evaluation, reinforcement learning and emerging physical AI applications, Accenture focuses on enterprise-wide AI implementation, technology consulting, managed services and business reinvention. Both compete in an evolving AI services landscape alongside Cognizant Technology Solutions CTSH and EPAM Systems EPAM.
With AI investments reshaping technology spending and creating new revenue opportunities, comparing their growth prospects, competitive advantages, valuations and earnings expectations is particularly relevant.
Let's dive deep and closely compare the fundamentals of the two stocks to determine which one is a better investment now.
The Case for Innodata Stock
Innodata is benefiting from robust demand for AI data engineering, high-value training datasets and model evaluation services. Its strategic relationships with leading technology companies and frontier AI laboratories position it to capitalize on increasing investments in advanced AI models.
The company's expanding capabilities across pre-training, post-training, agentic reinforcement learning and benchmarking are strengthening its competitive differentiation. Innodata has secured programs involving personalized AI agents and reinforcement-learning environments for computer-use applications, creating opportunities for larger engagements and recurring demand.
Its growing portfolio of reusable proprietary datasets and high-value pre-training services is also supporting profitability. In the second quarter of 2026, adjusted gross margin reached 49%, while revenues increased 58% year over year. Management reiterated its expectation of at least 40% revenue growth for 2026, highlighting sustained business momentum.
Innodata is also expanding into physical AI and robotics. Its newly opened motion-capture laboratory, designed to generate high-precision three-dimensional movement data, strengthens its ability to support humanoid robotics development. Opportunities in enterprise AI deployment assurance, cybersecurity and federal AI initiatives could further diversify revenues.
Compared with Cognizant and EPAM, Innodata's specialized exposure to frontier-model development offers substantial growth opportunities as AI complexity increases. However, Cognizant's extensive enterprise relationships and EPAM's advanced engineering expertise intensify competition for sophisticated AI engagements.
Despite improving customer diversification, concentration remains a significant concern. Its two largest customers collectively accounted for 71% of second-quarter 2026 revenues. Dependence on major technology customers, project-based contracts and unpredictable AI research spending could create revenue volatility. Rising competition from Cognizant and EPAM, alongside execution challenges in emerging AI markets, also presents risks.
The Case for Accenture Stock
Accenture's diversified business model, extensive enterprise relationships and broad technology ecosystem provide a strong foundation for sustained growth. Increasing demand for AI-led business reinvention, cloud modernization, cybersecurity and intelligent automation continues to create opportunities across consulting and managed services.
The company's AI strategy focuses on embedding advanced technologies into enterprise workflows while helping clients develop the digital infrastructure required for large-scale adoption. More than 400 clients initiated their first advanced AI engagements with Accenture during fiscal 2026, demonstrating expanding commercialization opportunities.
Its partnerships with leading technology providers are particularly important. Revenues associated with its top 10 ecosystem partners represented more than 60% of fiscal 2026 revenues, while bookings involving emerging AI and data partners more than tripled. These relationships strengthen Accenture's competitive positioning against Cognizant and EPAM.
Strategic acquisitions are another growth catalyst. Investments in cybersecurity, network intelligence, cloud transformation and engineering are broadening Accenture's addressable markets. At its October 2026 Investor Day, management outlined ambitions for mid-single-digit revenue growth in fiscal 2027 and 2028, accelerating to mid-to-high-single-digit growth in fiscal 2029.
Accenture's financial strength supports continued investment and shareholder returns. Fiscal 2026 free cash flow totaled $11.6 billion, while shareholder distributions reached $11.5 billion. Its scale and diversified customer relationships offer greater business stability than smaller AI specialists.
However, cautious discretionary technology spending, pricing pressures and uncertain conversion of AI experimentation into large-scale projects could constrain growth. Increasing AI-driven delivery efficiencies may also pressure traditional labor-based service revenues. Competition from Cognizant and EPAM, which are expanding their AI-enabled transformation offerings, adds further pressure.
INOD Outperforms ACN Despite Broader Market Weakness
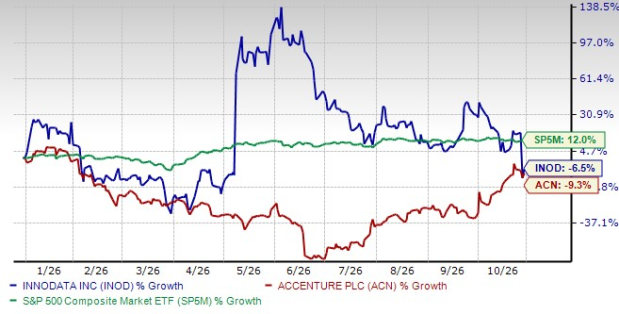
In the year-to-date (YTD) period, Innodata shares have lost 6.5%, outperforming Accenture's 9.3% decline. Both stocks have underperformed the Zacks S&P 500 Composite's 12% gain, indicating investor caution toward AI services stocks despite favorable long-term demand prospects.
INOD vs. ACN Price Performance (YTD)
Image Source: Zacks Investment Research
INOD's Premium Valuation Versus ACN's Discount
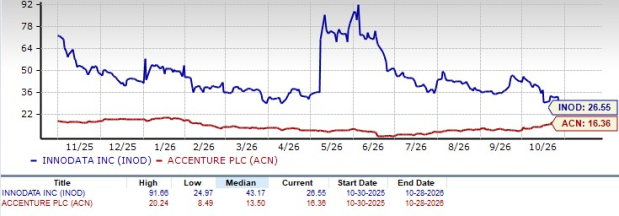
On a forward 12-month price-to-earnings basis, Innodata trades at 26.55X, considerably above Accenture's 16.36X.
Innodata's premium reflects expectations for stronger AI-driven growth but leaves limited room for execution setbacks. Accenture's lower valuation provides a comparatively attractive entry point, supported by diversified revenues, established profitability and substantial cash generation.
INOD vs. ACN Valuation (P/E F12M)
Image Source: Zacks Investment Research
Earnings Estimate Revisions Favor Accenture
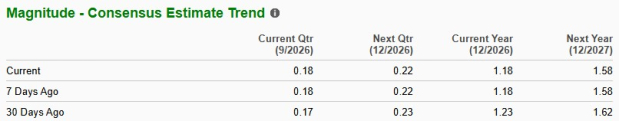
Over the past 30 days, the Zacks Consensus Estimate for Innodata's 2026 earnings per share (EPS) has declined from $1.23 to $1.18, while its 2027 estimate has decreased from $1.62 to $1.58.
Nevertheless, Innodata's 2026 earnings are expected to grow 28.3%, accompanied by 43.1% revenue growth. For 2027, earnings and revenues are projected to increase 34.2% and 27.7%, respectively.
Innodata's EPS Estimate
Image Source: Zacks Investment Research
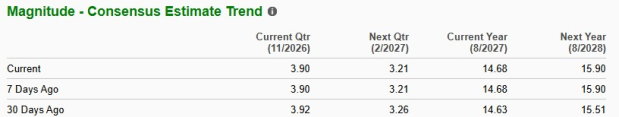
Conversely, Accenture's fiscal 2027 EPS estimate has increased from $14.63 to $14.68, while its fiscal 2028 estimate has risen from $15.51 to $15.90.
Accenture's fiscal 2027 earnings and revenues are expected to increase 5.1% and 4.2%, respectively. For fiscal 2028, earnings growth of 8.3% is anticipated alongside 4.7% revenue growth.
Accenture's EPS Estimate
Image Source: Zacks Investment Research
Although Accenture enjoys more favorable estimate revisions, Innodata offers substantially stronger projected earnings and revenue growth.
INOD or ACN: Which Stock Offers Better Upside?
Both Innodata and Accenture currently carry a Zacks Rank #3 (Hold), suggesting a neutral near-term outlook. However, their growth trajectories differ significantly. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Accenture offers greater financial stability, attractive valuation, improving earnings estimates and diversified enterprise exposure. Nevertheless, its mature operating structure limits its potential for rapid expansion.
Innodata appears better positioned for higher long-term growth potential, supported by accelerating demand for frontier AI services, agentic reinforcement learning, proprietary datasets and physical AI applications. Its substantially stronger revenue and earnings growth expectations, alongside expanding customer relationships, outweigh its valuation premium for growth-oriented investors willing to tolerate greater volatility.
Therefore, Innodata holds the edge over Accenture for investors seeking greater AI-driven upside potential, although customer concentration, earnings estimate reductions and elevated valuation warrant caution.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Accenture PLC (ACN): Free Stock Analysis Report
Innodata Inc (INOD): Free Stock Analysis Report
Cognizant Technology Solutions Corporation (CTSH): Free Stock Analysis Report
EPAM Systems, Inc. (EPAM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).