

Marvell Technology MRVL and Sandisk SNDK are benefiting from the expanding artificial intelligence (AI) infrastructure market, but their businesses address different requirements. Marvell develops custom silicon, networking and connectivity solutions that help AI systems process and transmit data. Sandisk supplies NAND flash-based storage products, including enterprise solid-state drives (SSDs), that support data-intensive workloads.
As AI infrastructure spending expands, both companies have opportunities to grow revenues and earnings. However, differences in growth visibility, profitability, valuation and execution risks raise the question: Which stock is the better investment right now?
The Case for MRVL Stock
Marvell is benefiting from rising demand for custom AI silicon, high-speed optical interconnects and advanced networking solutions. In the second quarter of fiscal 2027, revenues increased 36.5% year over year to $2.74 billion, while non-GAAP earnings rose 40.3% to 94 cents per share. Data center revenues reached a record $2.17 billion, up 46% year over year, accounting for 79% of total revenues.
The company is expanding its AI infrastructure portfolio as hyperscalers invest in larger and more complex AI clusters. Demand for 800G optical digital signal processors remains strong, while 1.6T products are ramping rapidly. Marvell also expects its scale-out switching business to more than double in fiscal 2027, supported by wider adoption of its 51.2T products.
Custom silicon represents another important growth opportunity. Management expects the business to more than double year over year in fiscal 2028, with further acceleration anticipated in fiscal 2029. Marvell's expanded commercial agreement with a key hyperscaler covers existing and potential programs involving AI accelerators, storage controllers, network interface cards and memory interface controllers.
Strategic ties with NVIDIA and the acquisitions of Celestial AI and XConn Technologies further expand Marvell's opportunities in optical interconnects and next-generation AI networking. Management expects fiscal 2027 revenues to increase approximately 45% to $12 billion and fiscal 2028 revenues to reach roughly $18 billion, implying growth of about 50% in the latter year.
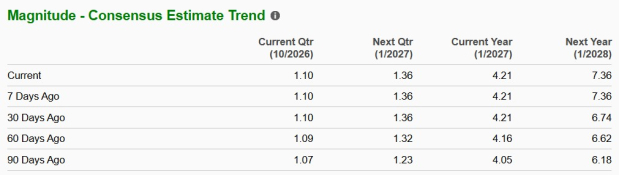
Nevertheless, Marvell faces margin pressure as custom silicon scales, along with customer concentration, supply constraints, geopolitical exposure and uneven communications demand. Its growing dependence on data center customers makes execution and hyperscaler spending particularly important. The Zacks Consensus Estimate for MRVL’s fiscal 2027 earnings suggests year-over-year growth of 48%. Estimates have remained unchanged in the past 30 days.
Image Source: Zacks Investment Research
The Case for SNDK Stock
Sandisk is benefiting from accelerating demand for enterprise storage as AI workloads require greater capacity and performance. The company's first-quarter fiscal 2027 revenues surged 378% year over year and increased 23% sequentially to $11.03 billion. SNDK’s data center revenues increased 61% sequentially to $4.80 billion, reflecting strong demand for enterprise SSDs across hyperscalers and AI infrastructure customers.
The company reported significant growth in its TLC enterprise SSD business and continued ramping of its QLC products, which address capacity-intensive applications such as AI data lakes, vector databases and retrieval repositories. SNDK’s edge revenues rose 7% sequentially to $5.83 billion, supported by resilience in premium and mainstream markets and stronger automotive and IoT demand.
Sandisk's technology roadmap, including BiCS8, BiCS9 and BiCS10, supports higher storage density, interface performance and bandwidth. BiCS9 is expected to improve interface performance through next-generation CMOS, while BiCS10 introduces a 1-terabit TLC die for performance-intensive workloads and a 2-terabit QLC die with twice the read and write bandwidth of BiCS8. Its high-bandwidth flash (HBF) technology also advanced during the quarter, with the first HBF memory die completing tape-out and fabrication underway.
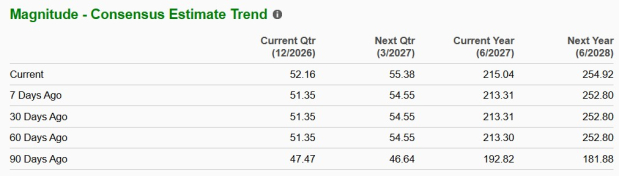
Sandisk expects to deliver samples of its first HBF-based products in 2027, although this opportunity is not yet included in its long-term financial model. SNDK’s profitability and cash generation remain strong. Sandisk's non-GAAP gross margin increased to 85.1% from 84.6% in the preceding quarter, while non-GAAP operating margin improved to 80.4% from 79.2%. The Zacks Consensus Estimate for SNDK’s fiscal 2027 earnings suggests year-over-year growth of 200%. Estimates have been revised upward in the past seven days.
Image Source: Zacks Investment Research
Stock Price Performance and Valuation of MRVL & SNDK
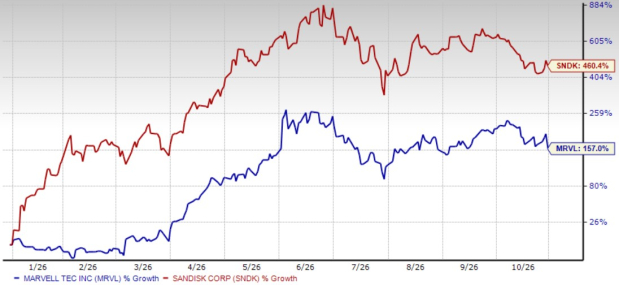
In the year-to-date period, MRVL shares have gained 157% compared with the surge of 460.4% in SNDK shares.
YTD Performance Chart
Image Source: Zacks Investment Research
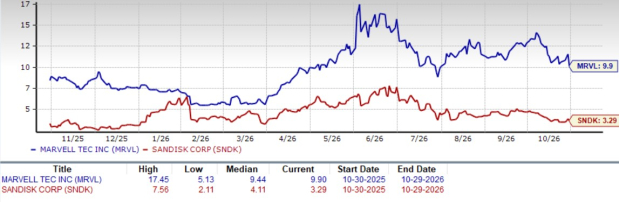
SNDK is trading at a forward sales multiple of 3.29X, way below its median of 4.11X. MRVL’s forward sales multiple sits at 9.90X, higher than its median of 9.44X over the past year.
Forward 12-Month (P/S) Valuation Chart
Image Source: Zacks Investment Research
Conclusion: MRVL vs. SNDK
Sandisk appears better positioned than Marvell at present, supported by significantly stronger revenue growth, expanding profitability and a more attractive valuation. While Marvell offers promising opportunities in custom AI silicon, optical interconnects and networking, Sandisk is benefiting from the growing importance of NAND storage in AI infrastructure, with data center revenues accelerating rapidly. This is strongly supported by SNDK’s massive bottom-line growth projection. SNDK and MRVL carry a Zacks Rank #2 (Buy) each at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Sandisk Corporation (SNDK): Free Stock Analysis Report
Marvell Technology, Inc. (MRVL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).