

Okta OKTA and SentinelOne S are both cybersecurity companies benefiting from enterprise security modernization, increasing adoption of artificial intelligence (AI) and growing demand for protecting autonomous AI agents. However, their core offerings differ significantly: Okta specializes in identity and access management, while SentinelOne focuses on autonomous threat detection, prevention and response.
OKTA or SentinelOne, which has an edge right now?
The Case for OKTA Stock
Okta is benefiting from growing enterprise demand for identity security, modernization of cybersecurity infrastructure and accelerating adoption of AI agents. The company’s unified identity platform supports workforce identity, customer identity, privileged access and identity governance, positioning it to capitalize on increasing security requirements across hybrid and multi-cloud environments. In the second quarter of fiscal 2027, revenues increased 11% year over year to $805 million, while subscription revenues grew 12% to $793 million. Remaining performance obligations (RPO) increased 17% to $4.86 billion, while current RPO advanced 14% to $2.59 billion, indicating healthy demand and improving revenue visibility. The company’s trailing 12-month dollar-based net retention rate was 107%, reflecting steady customer expansion.
Okta’s growing portfolio of newer products is strengthening its competitive position. Okta Identity Governance, Okta Privileged Access, Identity Threat Protection and Okta for AI Agents are creating additional cross-selling opportunities across its installed base of more than 20,000 customers. New products contributed approximately 30% of fiscal second-quarter bookings, with average annual contract value increase of approximately 40% when newer offerings were included in deals. The acquisition of Permiso further enhances Okta’s ability to detect and mitigate threats across human, nonhuman and AI-agent identities. Partnerships with Anthropic, Amazon Web Services, Cisco and OpenAI are expanding its ecosystem and reinforcing its vendor-neutral identity security strategy. These developments should support customer monetization and recurring revenue growth over the long term.
Okta also demonstrates stronger profitability and cash generation. In the fiscal second quarter, Okta generated non-GAAP operating income of $226 million, representing a margin of 28%. Okta’s free cash flow increased to $227 million, representing a margin of 28%, supported by operating efficiencies and disciplined expense management. The company had $2.3 billion in cash, cash equivalents and short-term investments at quarter-end, providing financial flexibility for innovation, strategic acquisitions and shareholder returns. For fiscal 2027, Okta expects revenues between $3.216 billion and $3.226 billion, with a non-GAAP operating margin of approximately 26% and free cash flow margin of 28-29%.
The Case for SentinelOne Stock
SentinelOne is benefiting from strong demand for AI-powered cybersecurity, autonomous threat detection and enterprise security platform consolidation. Its Singularity platform integrates endpoint security, cloud workload protection, security data analytics and AI-driven security operations, providing a broader threat detection and response offering than Okta’s identity-focused platform. In the second quarter of fiscal 2027, SentinelOne’s revenues increased 21% year over year to $292 million. Annual Recurring Revenue (ARR) increased 22%, while net new ARR reached $56 million, up 4% year over year. RPO surged 45% to approximately $1.7 billion, highlighting expanding enterprise commitments and improving revenue visibility. The company expects fiscal 2027 revenues between $1.202 billion and $1.207 billion, representing approximately 20% growth at the midpoint.
SentinelOne’s expanding AI security portfolio offers substantial long-term growth opportunities. Its Purple AI platform automates security investigations, threat detection and response, while Prompt Security provides visibility, governance and protection across enterprise AI applications and autonomous agents. ARR from Purple AI and Prompt Security combined tripled year over year in the fiscal second quarter, reflecting growing demand for AI-native cybersecurity solutions. The company is also benefiting from accelerating adoption of its AI SIEM, cloud security and security data solutions. Large enterprise customer wins, improving retention among customers generating more than $100,000 in ARR and growing adoption of multiple Singularity products support its expansion opportunities.
SentinelOne is also demonstrating improving operational efficiency and expanding enterprise adoption. In the fiscal second quarter, its non-GAAP operating margin reached a record 10%, expanding 820 basis points year over year. The company’s trailing 12-month adjusted free cash flow margin improved to 6%, while cash, cash equivalents and investments totaled approximately $813 million, with no debt. For fiscal 2027, SentinelOne expects non-GAAP operating income between $124 million and $128 million, reflecting continued margin improvement.
OKTA & SentinelOne’s Earnings Estimate Revisions Steady
The Zacks Consensus Estimate for OKTA’s fiscal 2027 earnings is pegged at $3.93 per share, unchanged over the past 30 days, indicating a 12.3% increase over fiscal 2026’s reported figure.
Okta, Inc. Price and Consensus
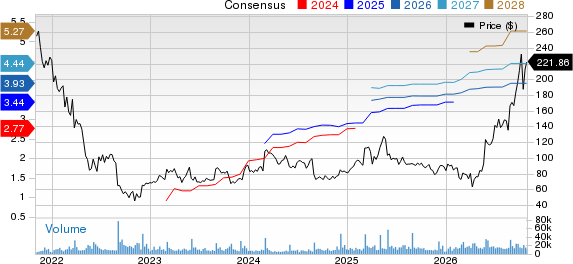
Okta, Inc. price-consensus-chart | Okta, Inc. Quote
The consensus mark for SentinelOne’s fiscal 2026 earnings has been steady at 32 cents per share over the past 30 days, suggesting 60% growth over fiscal 2026’s reported figure.
SentinelOne, Inc. Price and Consensus
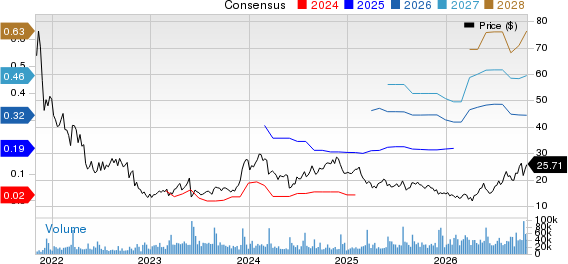
SentinelOne, Inc. price-consensus-chart | SentinelOne, Inc. Quote
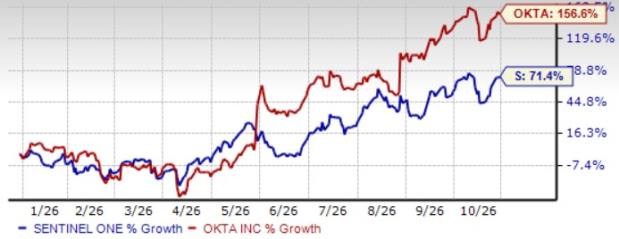
SentinelOne Shares Underperform Okta
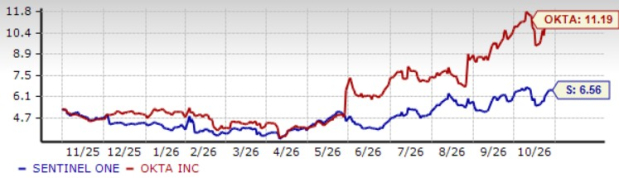
Year to date (YTD), SentinelOne shares have returned 71.4%, underperforming Okta’s appreciation of 156.6%.
S and OKTA Stock’s Price Performance
Image Source: Zacks Investment Research
In terms of forward 12-month Price/Sales (P/S), Okta shares are trading at 11.19X, higher than SentinelOne’s 6.56X.
Okta and SentinelOne has a Value Score of F, suggesting both shares are overvalued.
S and OKTA Valuation
Image Source: Zacks Investment Research
Here’s Why OKTA Has an Edge Right Now
Okta appears better positioned than SentinelOne, supported by its established identity security platform, expanding AI-agent governance capabilities and stronger financial profile. Okta’s customer base of more than 20,000 provides significant cross-selling opportunities for newer offerings, including Okta Identity Governance and Okta for AI Agents. Although SentinelOne delivers faster revenue growth, Okta’s superior profitability, robust cash generation and growing presence in AI-driven identity security make it a comparatively attractive investment proposition.
Currently, Okta and SentinelOne carry a Zacks Rank #3 (Hold) each. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
SentinelOne, Inc. (S): Free Stock Analysis Report
Okta, Inc. (OKTA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).