

Energy Transfer LP ET is expected to post a year-over-year improvement in both revenues and earnings when it reports third-quarter 2026 results on Nov. 3, before the market opens.
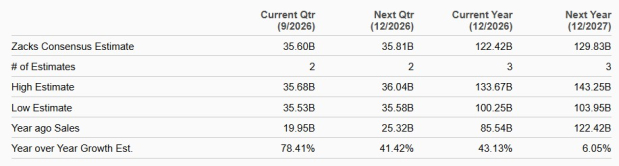
The Zacks Consensus Estimate for ET’s third-quarter revenues is pegged at $35.60 billion, indicating a 78.41% increase from the year-ago reported figure.
Image Source: Zacks Investment Research
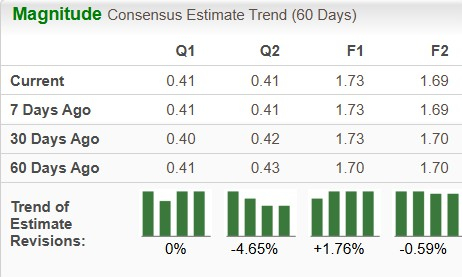
The consensus estimate for earnings is pegged at 41 cents per unit. The Zacks Consensus Estimate for ET’s third-quarter earnings has remained unchanged in the past 60 days.
Image Source: Zacks Investment Research
What the Zacks Model Unveils
Our model conclusively predicts an earnings beat for Energy Transfer this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an earnings beat. That is exactly the case here, as you can see below.
You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
ET’s Earnings ESP: Energy Transfer has an Earnings ESP of +8.46% at present.
Zacks Rank: Energy Transfer currently carries a Zacks Rank #3.
Stocks to Consider This Season
Here are some other stocks in the same sector that have the combination of factors indicating an earnings beat this season.
Some companies in the same sector that also have the right combination of the two factors for an earnings beat this season are Plains All American Pipeline PAA, Calumet Inc. CLMT and EOG Resources EOG. PAA, CLMT and EOG have an Earnings ESP of +11.94%, +48.76% and +0.79%, respectively. All three currently carry a Zacks Rank #2. You can see the complete list of today’s Zacks #1 Rank stocks here.
Factors Likely to Have Shaped ET’s Q3 Earnings
Energy Transfer is well-positioned to benefit from growing demand for natural gas, higher pipeline utilization and expanding natural gas liquids (“NGL”) infrastructure. The company's strong performance in the second quarter of 2026 provides a favorable foundation for third-quarter results. Positive trends in the second quarter, supported by strong Permian Basin activity and higher demand for energy transportation services, are expected to have supported operational performance in the third quarter.
Energy Transfer's ongoing infrastructure expansion is expected to strengthen its earnings growth prospects in the third quarter and beyond. The Hugh Brinson Pipeline entered commercial service in the second quarter, with its full Phase I transportation capacity of 1.5 billion cubic feet per day targeted for September 2026. The gradual commencement of contracted transportation services should support incremental revenues during the third quarter. Additionally, the Mustang Draw I processing plant, which commenced operations in June 2026, is expected to have benefited from increasing Permian production volumes.
The completed Lone Star Express expansion, providing more than 90,000 barrels per day of incremental NGL takeaway capacity, might have further supported throughput growth. Strong demand from data centers, artificial intelligence facilities and natural gas-fired power plants also creates additional opportunities for Energy Transfer's extensive pipeline network. These developments might have supported higher contracted volumes and strengthened its third-quarter earnings visibility. Energy Transfer’s predominantly fee-based business model, diversified asset portfolio and long-term transportation agreements provide earnings stability, while management targets annual distribution growth of 3-5%.
However, elevated capital spending, substantial debt obligations and potential normalization of commodity spreads and market volatility could limit near-term earnings growth.
ET Stock Trading at a Discount
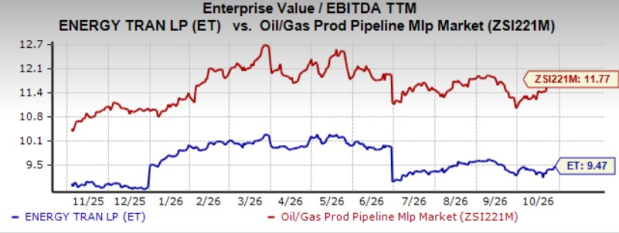
Energy Transfer units are somewhat inexpensive on a relative basis, with its current trailing 12-month Enterprise Value/Earnings before Interest Tax Depreciation and Amortization (EV/EBITDA TTM) being 9.47X compared with the industry average of 11.77X.
Image Source: Zacks Investment Research
ET Stock’s Price Performance
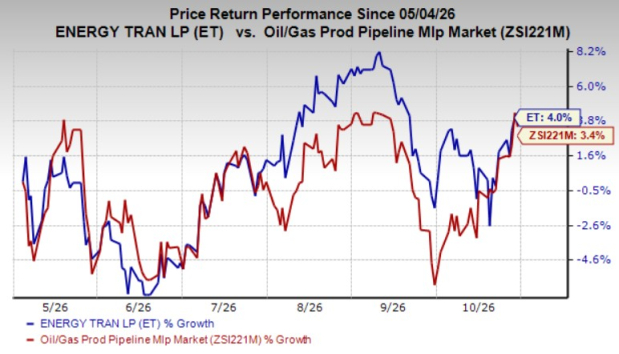
ET’s units have gained 4% in the past six months compared with the Zacks Oil and Gas Production Pipeline – MLB industry’s rise of 3.4%.
Image Source: Zacks Investment Research
Investment Thesis
Energy Transfer’s extensive network of nearly 140,000 miles of pipelines across 44 states positions it to benefit from rising U.S. hydrocarbon production and growing energy demand. With approximately 90% of adjusted EBITDA derived from fee-based operations, the partnership enjoys predictable cash flows and limited direct commodity price exposure. Increasing natural gas demand from power generation and AI-driven data centers, along with expanding export opportunities, should support sustained volume growth.
Energy Transfer is largely backed by long-term contracts and, through strategic investments, is expected to strengthen its infrastructure network. Its targeted annual distribution growth of 3-5%, supported by healthy distributable cash flow, enhances ET’s appeal to income-focused investors.
However, Energy Transfer faces risks from elevated capital spending, regulatory hurdles, project execution challenges and fluctuating commodity-driven production volumes. Nevertheless, diversified operations, long-term contractual commitments and disciplined capital allocation should help mitigate these challenges and support sustainable long-term growth.
Wrapping Up
Energy Transfer remains well positioned to benefit from growing energy demand, leveraging its extensive U.S. pipeline and midstream infrastructure network. Strategic acquisitions and ongoing organic expansion projects continue to strengthen its operational capabilities, enhance transportation and processing capacity, and create additional growth opportunities.
The partnership’s diversified geographic footprint, expanding asset base and disciplined investments provide a solid foundation for long-term earnings and cash flow growth.
Energy Transfer’s units have outperformed the broader industry over the past six months while trading at a relative valuation discount to peers. These favorable factors, combined with rising global demand for natural gas and other energy products, make ET an attractive investment consideration for investors seeking income and long-term growth potential.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Energy Transfer LP (ET): Free Stock Analysis Report
Plains All American Pipeline, L.P. (PAA): Free Stock Analysis Report
EOG Resources, Inc. (EOG): Free Stock Analysis Report
Calumet, Inc. (CLMT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).