

Silicon Motion Technology Corporation SIMO reported strong third-quarter 2026 results, with both the top and bottom lines surpassing the Zacks Consensus Estimate. Non-GAAP earnings of $4.35 per American Depositary Share (ADS) increased 335% year over year and beat the consensus estimate of $3.30 by 31.82%.
Revenues surged 131% year over year to approximately $560 million, exceeding the Zacks Consensus Estimate of $533 million by 5.07%. Growth was supported by robust demand for SSD controllers and Ferri & Boot Drive solutions, with the latter witnessing a remarkable 2,580-2,585% year-over-year sales increase.
SIMO Buoyed by Healthy Demand Trends
Silicon Motion is witnessing solid growth dynamics driven by strong momentum in enterprise and edge SSD controllers, automotive storage solutions and enterprise boot drive products. SSD controller sales increased 55-60% year over year and 20-25% sequentially, benefiting from expanding demand for edge and enterprise storage applications. Sales of embedded Multi-Media Card and Universal Flash Storage (eMMC+UFS) controllers rose 35-40% year over year.
Ferri & Boot Drive solutions sales increased 75-80% sequentially, supported by rapid adoption of automotive, edge artificial intelligence (AI) and enterprise boot drive solutions. Management highlighted growing contributions from its MonTitan enterprise and AI controllers as the company expands beyond traditional consumer storage markets.
Fabless Business Model Aids SIMO
Silicon Motion operates a fabless business model, focusing on chip design while outsourcing manufacturing to foundries like TSMC. Consequently, the company has a low capital investment requirement as it does not require expensive fabrication plants, enabling it to adopt advanced manufacturing nodes quickly, leading to higher margins compared to integrated manufacturers. This enables the company to focus on innovation and product development rather than manufacturing complexity.
The key growth drivers for SIMO include AI and high-performance computing, cloud data centers, automotive storage, smartphones and mobile devices. Each of these end markets is growing fast and offers lucrative growth potential. An expanding customer base and innovative products will likely act as tailwinds for the company’s top-line growth. Silicon Motion has shipped more than 10 billion NAND flash controllers in its operating history, with more than 750 million NAND controllers on average every year.
Price Performance
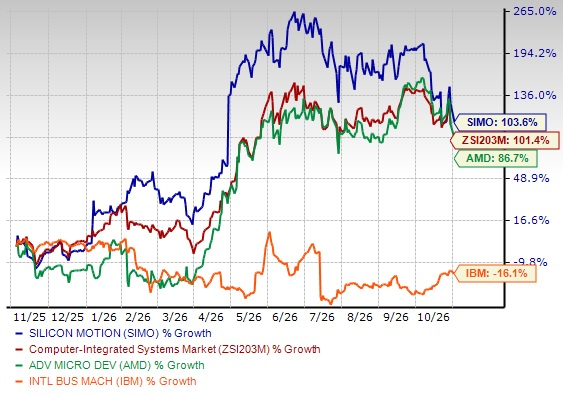
SIMO has gained 103.6% over the past year compared with the industry’s growth of 101.5%. It has also outperformed peers like Advanced Micro Devices, Inc. AMD and International Business Machines Corporation IBM. Advanced Micro has gained 86.7%, while IBM is down 16.1% over this period.
One-Year SIMO Stock Price Performance
Image Source: Zacks Investment Research
Stiff Competition, Geopolitical Issues Hurt SIMO
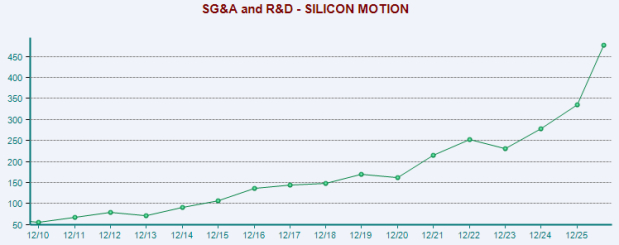
Despite the positives, Silicon Motion faces stiff competition in the mobile storage market from players like Micron, Microchip, Marvell and ON Semiconductor. Of late, intensifying competition in the card and USB flash drive controller markets is proving to be a major headwind. The tense political conditions between Taiwan and the People’s Republic of China increase the extent of political risk for the company. Moreover, North Korea’s nuclear and ballistic missile testing programs, deteriorating relationship with South Korea, leadership woes and strained relations with the United States are likely to affect its business. In addition, high R&D costs have adversely impacted its margins.
Image Source: Zacks Investment Research
Estimate Revision Trend
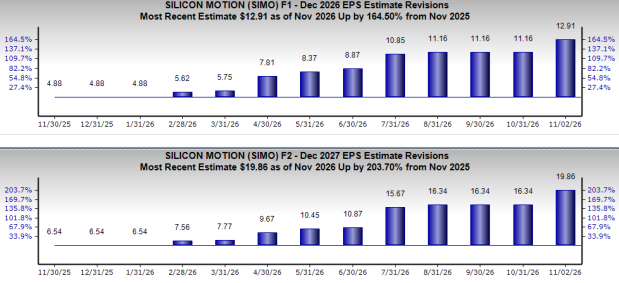
Earnings estimates for SIMO for 2026 have moved up 164.5% to $12.91 over the past year, while the same for 2027 has increased 203.7% to $19.86. The positive estimate revision depicts bullish sentiment about the stock’s growth potential.
Image Source: Zacks Investment Research
End Note
With solid fundamentals and healthy revenue-generating potential, driven by robust demand trends, Silicon Motion is poised for long-term growth. Further, a strong emphasis on quality, diligent execution of operational plans and continuous portfolio enhancements are driving more value for customers. An asset-light fabless semiconductor model, solid growth exposure to AI, cloud and automotive markets, increasing market share in SSD and mobile controllers and continuous innovation in storage technologies are key growth drivers for the company. With upward earnings estimate revisions, the stock is witnessing positive investor sentiment.
However, stiff competition and supply chain issues are likely to put pressure on the bottom-line growth. High R&D costs erode its profitability to a large extent. Silicon Motion is facing a tough operating environment amid tense geopolitical conditions across the globe. With a Zacks Rank #3 (Hold), Silicon Motion appears to be treading in the middle of the road, and investors could be better off if they trade with caution. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Silicon Motion Technology Corporation (SIMO): Free Stock Analysis Report
Advanced Micro Devices, Inc. (AMD): Free Stock Analysis Report
International Business Machines Corporation (IBM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).