

Monolithic Power Systems, Inc. MPWR is pairing rapid artificial intelligence-driven growth with a valuation that already reflects high expectations. Enterprise Data is expanding sharply, earnings estimates are moving higher and operating leverage is improving, but the stock’s premium leaves less room for execution setbacks.
The investment question is whether those growth drivers can keep compounding fast enough to justify the price investors are paying.
MPWR’s AI Growth Versus Its Premium Valuation
Enterprise Data revenues reached $506.7 million in the third quarter of 2026, rising 164.6% year over year and 33.2% sequentially. Higher sales of power-management solutions for AI and server applications, greater module content and a broader customer base are supporting that expansion.
The valuation raises the hurdle. MPWR trades at 36.21X forward 12-month earnings, compared with 21.66X for its Zacks sub-industry. That premium can be supported by exceptional growth, but it also means investors are paying in advance for continued execution, customer expansion and margin discipline.
MPWR’s Earnings Momentum Strengthens the Case
Third-quarter non-GAAP earnings increased 73.2% year over year to $8.19 per share and topped the Zacks Consensus Estimate of $7.80 by 5%. Revenues rose 63.1% to $1.20 billion and exceeded the consensus mark by 3.6%.
Monolithic Power Systems, Inc. Price, Consensus and EPS Surprise
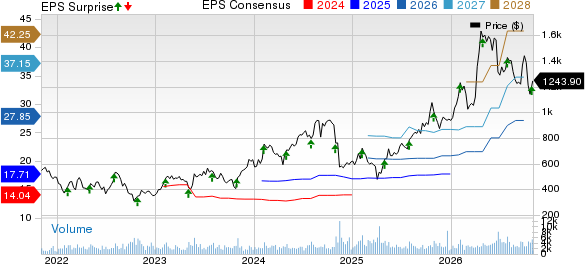
Monolithic Power Systems, Inc. price-consensus-eps-surprise-chart | Monolithic Power Systems, Inc. Quote
Analyst expectations have continued to move higher. The Zacks Consensus Estimate for current-fiscal-year earnings increased 3.9% over the past four weeks. Non-GAAP operating margin also expanded 320 basis points year over year to 38.6%, showing that revenue growth is translating into operating leverage.
Capacity Expansion Could Extend MPWR’s Runway
MPWR surpassed $6 billion in annual revenue-supporting capacity during the third quarter and is targeting $8 billion by the second half of 2027. The company’s fabless model and broader supplier network are designed to support new ramps without a comparable increase in capital intensity.
That flexibility matters as demand broadens beyond AI servers. Communications revenues jumped 134.7% year over year, while automotive revenues rose 19.2%. New high-speed memory, robotics and automotive power designs provide additional paths for growth if customer ramps develop as planned.
MPWR Still Carries Execution and Demand Risks
Enterprise Data accounted for 42.1% of third-quarter revenues, increasing MPWR’s exposure to AI infrastructure spending cycles. Internal inventory also climbed to $764.9 million from $675.8 million sequentially, while management is absorbing part of rising manufacturing costs. Storage and Computing declined 3.8% sequentially, and Consumer revenues fell 11.6% year over year.
The competitive backdrop remains active. Texas Instruments Incorporated TXN reported broad third-quarter 2026 growth across industrial, automotive and data center markets. Analog Devices, Inc. ADI said fiscal third-quarter 2026 revenue reached $4.02 billion, with year-over-year growth led by Data Center and Industrial. MPWR therefore must sustain its product and customer gains while protecting margins.
MPWR’s Strong Signal Contrasts With Style Scores
The case for MPWR is strongest on earnings momentum, while valuation and broader style measures argue for selectivity. The stock currently sports a Zacks Rank #1 (Strong Buy), reflecting favorable near-term earnings estimate revisions. You can see the complete list of today’s Zacks #1 Rank stocks here.
MPWR has a Value Score of F, Growth Score of D, Momentum Score of C and VGM Score of F. Zacks Style Scores are designed to complement the Zacks Rank, with A and B scores generally representing the more favorable style characteristics. MPWR’s combination therefore presents a mixed setup: estimate revisions support the short-term signal, while the weaker Style Scores and premium valuation suggest investors should weigh the quality of the growth against the price required to own it.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Monolithic Power Systems, Inc. (MPWR): Free Stock Analysis Report
Analog Devices, Inc. (ADI): Free Stock Analysis Report
Texas Instruments Incorporated (TXN): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).