

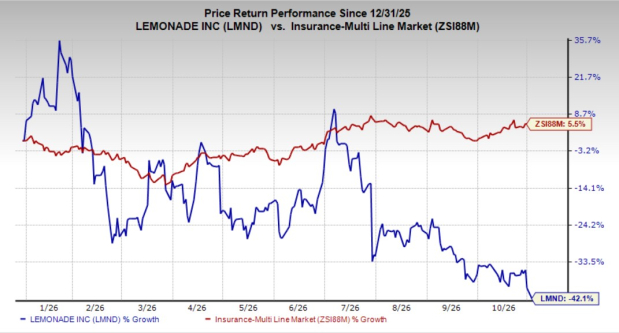
Lemonade Inc. shares LMND have lost 42.1% year to date, in contrast to the industry’s 5.5% growth. Continued unprofitability, high valuation and slower-than-expected progress toward sustainable earnings likely weighed on investors’ confidence.
Lemonade is a technology-focused insurer that leverages artificial intelligence, data analytics and automation to improve efficiency and support a scalable, low-cost operating model.
LMND vs Industry YTD
Image Source: Zacks Investment Research
Shares of Hippo Holdings, Inc. HIPO, a technology-enabled insurer, have gained 18.7% year to date, while those of EverQuote Inc. EVER and Root Inc. ROOT have lost 10.1% and 28.3%, respectively, in the same time frame.
The Case for Lemonade
Lemonade’s AI-driven operating model continues to enhance underwriting, pricing, claims processing and customer service, supporting a scalable and cost-efficient business. Operational efficiency is improving, with in-force premium per customer rising 8% in the second quarter of 2026. Underwriting performance also strengthened, as the gross loss ratio declined despite winter storm losses. Disciplined underwriting and favorable reserve development drove a 76% increase in gross profit.
Pet Insurance and Lemonade Auto remain key growth drivers, while rising multi-policy adoption supports customer retention, lifetime value and cross-selling opportunities. Management expects revenue growth of 65% for full-year 2026.
In-force premium increased 32.5% year over year to $1.43 billion, marking the 11th consecutive quarter of accelerating growth. Customer expansion, higher premiums per customer and platform scalability underpin momentum, with management targeting $10 billion in long-term in-force premium.
Lemonade’s reinsurance strategy helps limit claims exposure and earnings volatility, while a lower ceding rate enables it to retain more premiums. Despite profitability remaining a work in progress, rising margins and positive free cash flow indicate improvement. Management expects EBITDA profitability by the fourth quarter of 2026. Its $1.2 billion cash and investment balance provides financial flexibility to fund growth and innovation.
Yet, Lemonade remains exposed to catastrophe-related losses, with severe weather events potentially driving higher claims costs and underwriting volatility.
Additionally, rising customer acquisition expenses, with sales and marketing spending up over 30% year over year in the second quarter of 2026, could put pressure on margins if customer growth and retention fail to deliver adequate returns.
Are Lemonade Shares Expensive?
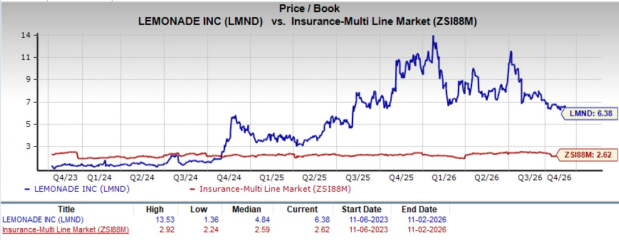
Lemonade trades at a 12-month trailing price-to-book ratio of 6.38X, well above the industry average of 2.58X and its three-year median of 4.84X. The premium likely reflects faster revenue growth, AI-driven operating efficiencies and substantial long-term market share gains.
Image Source: Zacks Investment Research
Lemonade is expensive compared to EverQuote, Hippo Holdings and Root.
Growth Estimates for LMND
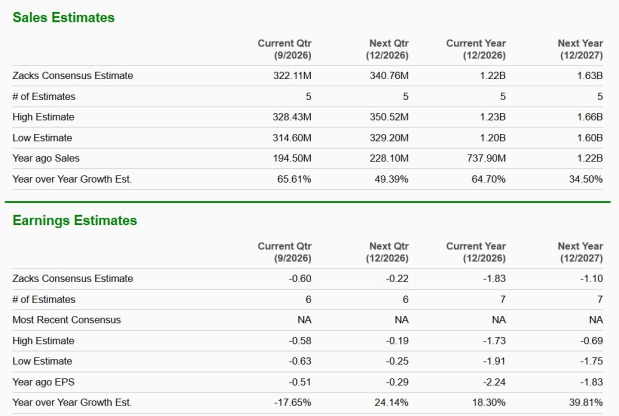
The Zacks Consensus Estimate for the company’s 2026 and 2027 earnings indicates an 18.3% and a 39.8% year-over-year increase, respectively.
The consensus estimates for 2026 and 2027 revenues suggest year-over-year improvements.
Image Source: Zacks Investment Research
Optimistic Analysts' Sentiment on LMND
The Zacks Consensus Estimate for LMND's 2026 and 2027 earnings has witnessed northbound movement, respectively, in the past 30 days.
Image Source: Zacks Investment Research
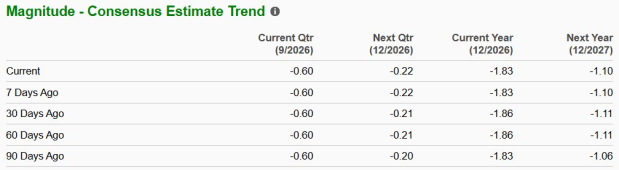
The consensus estimate for 2026 and 2027 earnings of EverQuote and Root witnessed no movement in the last 30 days, while that for Hippo Holdings witnessed northbound movement in the same time frame.
What Should Investors Do?
Lemonade is well-positioned for long-term growth, supported by strong premium expansion, an AI-driven operating model and improving profitability. Its diversified product portfolio, disciplined underwriting and reinsurance strategy strengthen its competitive position. Growth projections and optimistic analyst sentiment instill confidence.
Yet, Lemonade remains exposed to catastrophe-related losses, which could raise claims costs, put pressure on underwriting margins and increase earnings volatility. Given its premium valuation and price erosion, it is wise to adopt a wait-and-see approach for this Zacks Rank #3 (Hold) stock presently. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Lemonade, Inc. (LMND): Free Stock Analysis Report
EverQuote, Inc. (EVER): Free Stock Analysis Report
Root, Inc. (ROOT): Free Stock Analysis Report
Hippo Holdings Inc. (HIPO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).