

Zebra Technologies Corporation ZBRA highlighted broad-based demand, improving supply availability and strategic pricing actions during its third-quarter 2026 earnings call. Management emphasized accelerating mobile computing sales and continued customer investment in automation.
CEO William Burns attributed the strong performance to product innovation and expanding demand across key industries. CFO Nathan Winters outlined measures to manage rising memory costs while sustaining profitability.
Zebra reported third-quarter adjusted earnings of $4.95 per share, exceeding the Zacks Consensus Estimate of $4.90. Net sales increased 22.3% year over year to $1.61 billion, surpassing the Zacks Consensus Estimate of $1.56 billion. Organic sales increased 11.3%.
Zebra Technologies Corporation Price, Consensus and EPS Surprise
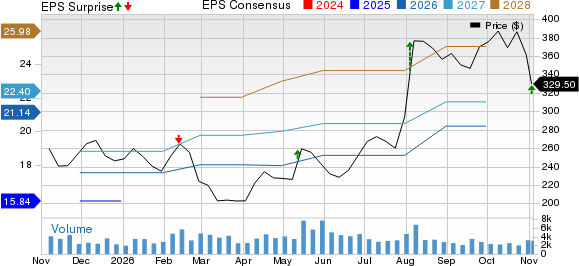
Zebra Technologies Corporation price-consensus-eps-surprise-chart | Zebra Technologies Corporation Quote
ZBRA Sees Broad-Based Demand Across Industries
Burns highlighted strong customer spending across retail, transportation and logistics, manufacturing and healthcare, supported by ongoing investments in workforce productivity and automation.
Transportation and logistics was the fastest-growing end market, while healthcare delivered double-digit growth. Retail and manufacturing recorded high-single-digit growth.
Winters reported 15% organic growth in Connected Frontline, led by mobile computing. Asset Visibility and Automation grew 7%, supported by machine vision, printing and RFID solutions.
Zebra Addresses Rising Memory Costs
Winters identified memory component inflation as a significant profitability headwind. Adjusted gross margin declined 220 basis points to 46%, reflecting higher memory costs and business mix.
Management increased its estimated full-year memory cost headwind to $145 million from $120 million, primarily reflecting stronger mobile computing volumes.
During the Q&A, a BNP Paribas analyst questioned the increase. Winters clarified that component pricing remained consistent with expectations and that targeted pricing actions, restructuring savings and operating efficiencies would offset the full-year impact.
ZBRA Raises Its Full-Year Growth Outlook
Zebra increased its 2026 sales growth outlook to approximately 17%, two percentage points above its previous forecast.
For the fourth quarter, management expects sales growth of 10% to 14%, adjusted EBITDA margin of approximately 22% and adjusted earnings between $5 and $5.40 per share.
Winters projected full-year adjusted EBITDA margin of approximately 23.5% and adjusted earnings of $21.20 per share, based on fourth-quarter guidance midpoint. Free cash flow is expected to reach at least $1 billion.
Zebra Expands AI-Enabled Solutions
Burns emphasized the growing importance of AI-enabled mobile computing, RFID and machine vision in customers' operational modernization efforts.
Zebra's Frontline AI suite is gaining early traction, including a deployment of its AI Companion across a large North American specialty retailer's locations.
During the Q&A, a Needham analyst questioned software monetization. Burns indicated that software currently contributes a low-single-digit percentage of revenues, while emphasizing AI's broader role in supporting hardware demand and customer upgrades.
ZBRA Anticipates Stronger 2027 Opportunities
Management highlighted a multiyear pipeline of transportation and logistics device refresh opportunities, with global customer deployments beginning in 2027.
Responding to a Stephens analyst, Burns indicated that 2027 growth could approach the upper end of Zebra's long-term growth range of 5% to 7%.
Winters noted that October pricing actions included increases of approximately 15% for mobile computing products, expected to contribute roughly 1.5 percentage points to 2027 revenue growth.
Zebra Maintains Disciplined Capital Allocation
Zebra generated $661 million in free cash flow during the first nine months of 2026, supporting continued investments and shareholder returns.
Winters reported third-quarter share repurchases of $75 million, bringing year-to-date repurchases above $640 million.
During the Q&A, a Needham analyst questioned acquisition priorities. Burns emphasized selectively pursuing complementary businesses while maintaining shareholder distributions and investments in existing operations.
ZBRA Focuses on Sustaining Profitable Growth
Burns reiterated that innovation, customer relationships and expanding automation opportunities remain central to Zebra's long-term strategy.
Management maintained confidence in meeting customer demand despite supply-chain pressures, with pricing discipline and operational productivity supporting its profitability objectives.
What ZBRA's Zacks Rank and Style Scores Indicate
Zebra currently carries a Zacks Rank #2 (Buy), indicating favorable near-term prospects based on earnings estimate revisions. Its Growth Score of A and Momentum Score of B reflect attractive growth and price-momentum characteristics. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The stock's Value Score of C indicates comparatively moderate valuation appeal, while its VGM Score of A highlights favorable combined characteristics. The combination of a Zacks Rank #2 and VGM Score of A is favorable under the Zacks framework. However, the Zacks Rank may change as analysts revise earnings estimates following the latest results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Zebra Technologies Corporation (ZBRA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).