

NGL Energy Partners LP NGL has strengthened its growth profile around Water Solutions, with rising volumes, better capital returns and higher fiscal 2027 adjusted EBITDA guidance. The question is whether those gains are enough to offset a heavy spending cycle and growing dependence on one business.
The setup is favorable in several areas, but the stock does not offer a clean buy signal. Valuation is below its sub-industry, while execution, cash flow and regulatory risks remain important.
NGL's Water Business Anchors the Growth Case
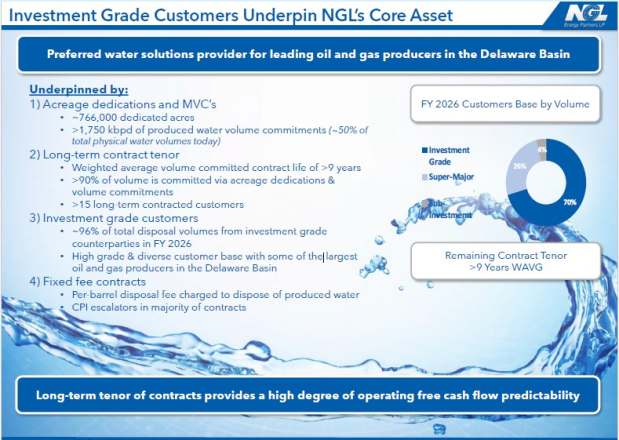
Water Solutions generated about $603 million of NGL's roughly $660 million in fiscal 2026 adjusted EBITDA from continuing operations. Trailing 12-month return on invested capital is 11.7%, above NGL's 10-year median of 5.5% and the 10.9% industry median, indicating stronger economics from recent investment.
The broader oilfield-water market is also attracting capital. Texas Pacific Land Corporation TPL supplies source and recycled or treated produced water in the Permian Basin and is developing additional beneficial-reuse capabilities. Select Water Solutions, Inc. WTTR expanded its Delaware Basin water-midstream footprint with its Nov. 2, 2026, acquisition of Pilot Water Solutions.
NGL's Contracts Improve Earnings Visibility
More than 90% of NGL's water volumes are supported by contractual commitments or dedicated production areas. Its volume-commitment contracts have an average remaining term of more than nine years, giving the partnership a longer runway to recover infrastructure investment.
Minimum-volume agreements can require customers to pay for specified quantities even when actual use falls short. That structure can reduce near-term volume volatility, although weaker drilling activity could still affect contract renewals and future expansion opportunities.
NGL Faces a Heavy Fiscal 2027 Spending Load
Management expects more than $200 million of fiscal 2027 growth spending plus roughly $45 million of maintenance capital. First-quarter operating cash flow was about $77 million, while capital expenditures reached $108.8 million, showing the near-term funding burden.
Spending is concentrated in the first half of the fiscal year, while much of the related EBITDA is expected in fiscal 2028. NGL is also trying to reduce leverage and redeem about half of its remaining Class D preferred units, increasing the importance of project execution and liquidity discipline.
NGL's Valuation Balances Discount and Risk
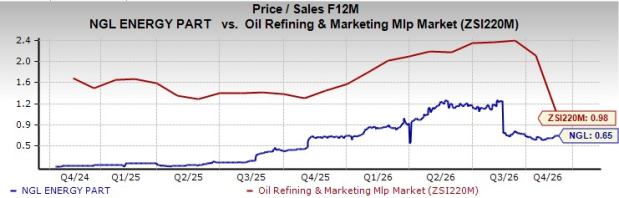
NGL trades at 0.65X forward 12-month sales, below the Zacks sub-industry's 0.98X. Its Value Score of B supports the relative-value case, but the multiple remains well above NGL's five-year median of 0.10X, meaning the market already reflects part of the improved outlook.
Regulatory exposure tempers that discount. Restrictions tied to underground injection, seismic activity or permitting could force NGL to redirect volumes, add transportation or treatment costs, or slow capacity expansion. Those risks matter more as Water Solutions becomes a larger share of earnings.
NGL's Scores Favor Growth Over Momentum
NGL's operating case remains constructive, but the combination of concentrated earnings, elevated capital spending and regulatory uncertainty supports a measured stance rather than an aggressive entry. The stock currently carries a Zacks Rank #3 (Hold), which is consistent with waiting for clearer evidence that growth spending converts into cash flow without disrupting deleveraging.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
NGL also has a VGM Score of A, Growth Score of A and Value Score of B. Its Momentum Score of D signals weaker price-based support. Because Style Scores are designed to complement the Zacks Rank, the current mix favors patience over treating the growth case alone as a buy signal.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
NGL Energy Partners LP (NGL): Free Stock Analysis Report
Select Water Solutions, Inc. (WTTR): Free Stock Analysis Report
Texas Pacific Land Corporation (TPL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).