

Clean Harbors CLH reported strong third-quarter 2026 results, with earnings and revenues surpassing the Zacks Consensus Estimate.
Earnings of $3.93 per share beat the consensus mark of $3.18 by 23.6%. Earnings surged 77.8% year over year. Revenues increased 20.7% year over year to $1.87 billion, beating the consensus estimate of $1.72 billion by 8.4%, as reported in the earnings data.
The better-than-expected results failed to impress the market as the stock declined 5.7% since the release of results on Oct. 28.
Growth was driven by substantial emergency response activity, robust environmental services demand and favorable base oil pricing. Incineration utilization remained healthy at 87%.
Clean Harbors, Inc. Price, Consensus and EPS Surprise
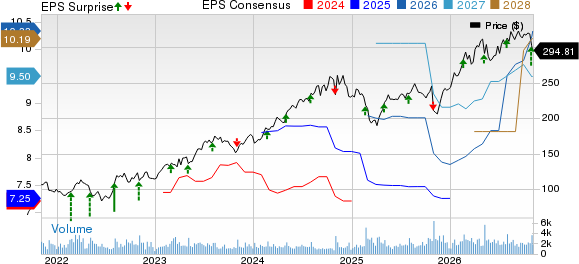
Clean Harbors, Inc. price-consensus-eps-surprise-chart | Clean Harbors, Inc. Quote
CLH's ES Revenues Rise 17%
Environmental Services (“ES”) generated third-quarter revenues of $1.55 billion, up 16.5% year over year. Field Services led growth, with revenues increasing more than 70%, supported by significant emergency response activity. One large-scale event contributed approximately $120 million in revenues.
Safety-Kleen Environmental Services (“SKSS”) revenues increased 11%, supported by pricing and higher volumes in containerized waste collection and vacuum services. Technical Services revenues grew 3%, benefiting from PFAS-related work despite challenging year-ago project comparisons. Industrial Services recorded modest growth, supported by Canadian operations and initial data center engagements, partially offset by subdued refinery turnaround activity.
Clean Harbors' SKSS Gains From Favorable Oil Pricing
SKSS reported revenues of $318.3 million, up 46% from $218 million a year ago. The increase primarily reflected elevated pricing for base oil and blended lubricants amid global supply constraints.
Adjusted EBITDA jumped 209% year over year to $126.5 million, with the segment margin expanding to 39.7% from 18.8%. The business collected 62 million gallons of waste oil compared with 64 million gallons a year ago, while maintaining a charge-for-oil position. Group III production increased approximately 20%, while direct blended sales accounted for 12% of total volumes sold, up from 9%.
CLH's Profitability Improves on Operating Efficiency
Consolidated adjusted EBITDA increased 42.5% year over year to $456.1 million. The adjusted EBITDA margin expanded 370 basis points to a record 24.4%, reflecting favorable business mix, effective pricing and productivity improvements.
ES adjusted EBITDA increased 19% to $425.4 million, while its margin improved 60 basis points to 27.4%, marking the 18th consecutive quarter of year-over-year expansion.
Gross profit increased to $661.4 million from $500.8 million, with the gross margin improving to 35.4% from 32.3%. Selling, general and administrative expenses increased to $217.1 million from $189.6 million, although their share of revenues declined 60 basis points to 11.6%. Income from operations rose 65% to $318.1 million, while net income increased 75% to $208.1 million.
CLH's Cash Generation Supports Strategic Investments
Cash provided by operating activities increased 38.8% year over year to $419.2 million. Adjusted free cash flow (FCF) was $323.1 million compared with $230.6 million a year ago, excluding qualifying growth investments.
The company invested $168.1 million in net capital expenditure during the quarter. Its growth initiatives include a $55-million Los Angeles hub acquisition and expanded data center investments. Management increased its overall dedicated data center capital target to $70 million, reflecting encouraging early project activity.
CLH ended September with $516.6 million in cash and short-term marketable securities. It repurchased approximately 82,000 shares for $25 million during the quarter, leaving nearly $525 million available under its authorization.
Clean Harbors Sees Continued Demand Across Key Markets
Management highlighted strong waste collection volumes, with deferred revenues increasing 20%. The company's $600-million, 10-year reshoring contract commenced in the fourth quarter, while PFAS-related opportunities continue to support demand for treatment and remediation services.
Recent ES&H and EnviroServe acquisitions are expected to strengthen the ES network. Management also expects data center activity and improving manufacturing demand to support longer-term growth.
Separately, Clean Harbors announced that Eric Gerstenberg will become sole CEO on Jan. 1, 2027, following Mike Battles' retirement from his co-CEO role and board position at year-end.
Clean Harbors Raises 2026 Profit & Cash Flow Outlook
For the fourth quarter, management anticipates year-over-year adjusted EBITDA growth of 23-26%, supported by healthy contributions from both operating segments. The outlook assumes no additional large-scale emergency response events during the quarter.
Following its strong year-to-date performance, Clean Harbors raised its 2026 adjusted EBITDA guidance to $1.44-$1.48 billion from the previous quarter’s view of $1.35-$1.41 billion.
The company also raised its adjusted FCF outlook to $600-$660 million from $520-$580 million provided in the preceding quarter. Expected net income is hiked to $528-$563 million from the preceding quarter’s view of $481-$531 million.
CLH carries a Zacks Rank #3 (Hold) at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Earnings Snapshot
Fiserv FISV reported better-than-expected third-quarter 2026 results.
FISV’s adjusted earnings of $1.75 per share beat the consensus estimate of $1.72 by 1.7% but declined 14% year over year. Adjusted revenues of $4.85 billion surpassed the consensus mark of $4.84 billion by 0.2% but decreased 1% from the year-ago quarter.
TransUnion TRU posted better-than-expected third-quarter 2026 results.
TRU’s adjusted earnings of $1.25 per share surpassed the Zacks Consensus Estimate by 3.3% and increased 13.6% year over year. Revenues of $1.31 billion beat the consensus estimate by 0.3% and rose 12% from the year-ago quarter.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Clean Harbors, Inc. (CLH): Free Stock Analysis Report
Fiserv, Inc. (FISV): Free Stock Analysis Report
TransUnion (TRU): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).