

Appian Corporation APPN highlighted accelerating enterprise AI adoption, stronger customer expansion and improving sales execution during its third-quarter 2026 earnings call. Management emphasized growing demand for automation in mission-critical business processes.
The company also raised its full-year outlook following better-than-expected results, while addressing AI monetization, government contracts and profitability investments.
Appian Sees AI Driving Enterprise Demand
CEO Matthew Calkins emphasized Appian's role in deploying AI within complex, regulated enterprise workflows. He identified deterministic orchestration, data connectivity, governance and cost-efficient model selection as key capabilities supporting adoption.
Management reported that customer AI usage increased more than 50% sequentially. Financial services, life sciences and the public sector collectively account for 80% of annual recurring revenue (ARR).
Calkins highlighted applications involving compliance audits, insurance claims and enterprise modernization. These deployments demonstrate how customers are incorporating AI into established operational processes.
APPN Raises 2026 Outlook Following Strong Quarter
CFO Srdjan Tanjga raised full-year revenue guidance to $873-$877 million, representing 20-21% year-over-year growth. Cloud subscription revenue is projected at $536-$538 million, implying 23% growth.
For the fourth quarter, management expects revenues of $233-$237 million, cloud subscription revenues of $143-$145 million and adjusted EBITDA of $30-$33 million.
The revised outlook follows third-quarter revenues of $234.63 million, exceeding the Zacks Consensus Estimate of $215.75 million. Non-GAAP earnings of 51 cents per share surpassed the 32-cent consensus estimate.
Appian Corporation Price, Consensus and EPS Surprise
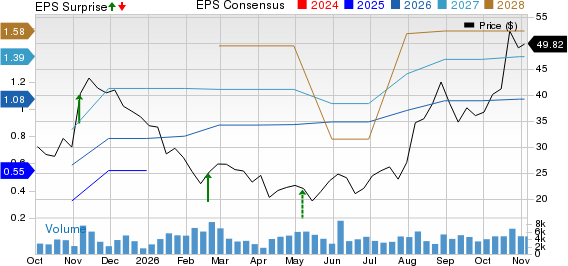
Appian Corporation price-consensus-eps-surprise-chart | Appian Corporation Quote
Appian Details AI Monetization Opportunities
During the analyst discussion, William Blair questioned whether AI consumption-based pricing was contributing meaningfully to growth.
Tanjga explained that customers typically access production AI capabilities through advanced subscription tiers priced 25-35% above standard subscriptions. Additional consumption generates revenue through overage charges or purchased usage bundles.
Management acknowledged that incremental consumption revenues are not yet material. However, customers increasingly exceed included allocations, establishing another potential revenue stream alongside subscription upgrades.
APPN Targets Larger Modernization Contracts
Calkins identified legacy application modernization as an important driver of larger enterprise transactions. Appian's enterprise growth plans allow customers to negotiate expanding annual commitments while supporting broader application deployment.
In response to William Blair's questions, Calkins said modernization initiatives are supporting some of the company's largest transactions. Customers are increasingly considering extensive application replacement rather than isolated development projects.
Management also highlighted AI-assisted development, which enables customers to build applications through external AI tools while retaining Appian's platform governance, security and maintenance capabilities.
Appian Benefits From Public Sector and Self-Managed Demand
Management reported particularly strong execution in the U.S. public sector, including seven-figure software transactions involving a cabinet-level agency and a military branch.
Responding to Morgan Stanley, Calkins said data sovereignty concerns were also strengthening European demand for self-managed software. Customers value retaining control over deployment environments and sensitive information.
Tanjga clarified that approximately 70% of self-managed contract bookings are recognized upfront under accounting rules. He emphasized that these annual contracts did not involve multiyear revenue pull-forwards.
APPN Balances Expansion With Investment
During the Q&A, D.A. Davidson questioned fourth-quarter profitability expectations. Tanjga attributed sequential expense increases partly to accelerated sales hiring, customer events and seasonal compensation.
Management expects full-year adjusted EBITDA of $116-$119 million, with approximately 3 percentage points of margin improvement. Tanjga reaffirmed the commitment to continued margin expansion without providing numerical targets for 2027.
Operating cash flow remained a concern after third-quarter cash usage reached $15.4 million. Addressing Barclays, Tanjga attributed the weakness to collection timing and highlighted particularly strong October collections.
Appian Maintains Focus on Durable Growth
Management expressed confidence in enterprise demand and improving sales productivity while declining to provide quantitative 2027 growth expectations.
Calkins and Tanjga emphasized expanding strategic customer relationships, strengthening AI adoption and investing in sales capacity while maintaining profitability discipline.
What Zacks Rank and Style Scores Indicate for APPN
APPN currently carries a Zacks Rank #3 (Hold), indicating a neutral near-term earnings-revision outlook. Its Growth Score of A and Momentum Score of A reflect favorable growth and price-momentum characteristics, while its Value Score of D indicates weaker relative valuation appeal. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The stock's VGM Score of A reflects a favorable combined assessment of value, growth and momentum. However, Zacks emphasizes combining strong Style Scores with Zacks Rank #1 or #2 (Buy) stocks. APPN's Hold ranking warrants a balanced interpretation, particularly as earnings estimate revisions following the reported quarter could change its Zacks Rank.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Appian Corporation (APPN): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).