

MKS Inc. MKSI emphasized accelerating artificial intelligence (AI)-related demand, expanding manufacturing capacity and improving customer visibility during its third-quarter 2026 earnings call. Management highlighted opportunities across semiconductor manufacturing and advanced electronics packaging.
The company also outlined stronger fourth-quarter expectations, supported by robust orders and improving operating leverage. Discussions with analysts focused on supply constraints, market share opportunities and the sustainability of margin expansion.
MKSI Sees Strong Momentum Heading Into Q4
President and CEO John Lee said demand across all three end markets exceeded or matched the upper end of management's expectations. Customer orders continue to strengthen, providing greater visibility into 2027 and beyond.
Fourth-quarter revenues are projected at $1.49 billion, plus or minus $40 million, representing approximately 44% year-over-year growth. Non-GAAP earnings are expected at $5 per share, plus or minus 38 cents.
Third-quarter revenues reached $1.41 billion, beating the Zacks Consensus Estimate of $1.36 billion. Adjusted earnings of $4.18 per share surpassed the consensus estimate of $3.64.
MKS Inc. Price, Consensus and EPS Surprise
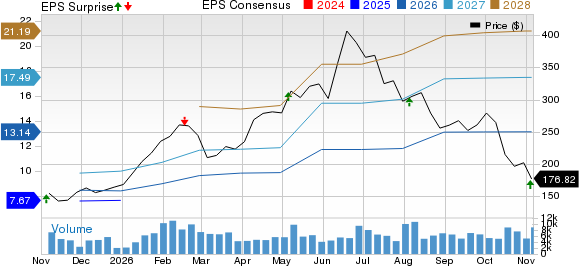
MKS Inc. price-consensus-eps-surprise-chart | MKS Inc. Quote
MKS Expects Semiconductor Growth to Outpace WFE
Semiconductor revenues increased 54% year over year to $638 million, supported by DRAM, advanced logic and NAND upgrade investments.
Lee highlighted strengthening demand for plasma, reactive gas, vacuum and power solutions. The company also secured design wins involving advanced logic applications and pulsed DC power technology.
During the Q&A, a Cantor Fitzgerald analyst questioned MKS' ability to outperform wafer fabrication equipment (WFE) spending. Lee indicated that semiconductor growth could approach 40% year over year, exceeding industry growth, with continued outperformance expected in 2027.
MKSI Expands Capacity Amid Packaging Demand
Electronics & Packaging revenues climbed 43% year over year to $415 million, reflecting strong demand for chemistry equipment and advanced PCB technologies.
Lee said chemistry equipment sales increased more than 75% year over year, with full-year revenues expected to exceed $300 million. Existing capacity is sold out through 2027, while bookings extend into 2028.
Management plans to double chemistry equipment capacity through its Guangzhou expansion, targeted for completion in the third quarter of 2027. During the Q&A, Lee explained that additional capacity should accelerate equipment revenue growth in the second half of 2027.
MKS Targets Higher Margins Despite Near-Term Pressure
Gross margin reached 47.7%, while non-GAAP operating margin expanded approximately 700 basis points year over year to 27.8%.
Executive vice president and CFO Ram Mayampurath attributed the improvement to higher volumes and operating leverage. However, growing sales of lower-margin chemistry equipment and manufacturing expansion costs remain near-term headwinds.
Responding to questions from Deutsche Bank and Wells Fargo analysts, Mayampurath indicated that higher-margin chemistry consumables should eventually offset these pressures. Management expects near-term incremental gross margins around 50%, with potential for higherlevels longer term.
MKSI Highlights Financial Flexibility and Shareholder Returns
MKS generated $243 million in free cash flow during the quarter, representing approximately 17% of revenues. Net leverage declined to 2.4 times trailing adjusted EBITDA.
Mayampurath highlighted continued debt reduction, including more than $450 million in year-to-date principal prepayments following an additional November payment.
The board also authorized a $500 million share repurchase program. Responding to a Wells Fargo analyst, Mayampurath emphasized that organic investment and debt management remain priorities, while repurchases provide additional capital allocation flexibility.
MKS Maintains Focus on Execution and Long-Term Growth
Management's commentary remained confident regarding AI-related investment, customer demand and manufacturing readiness. Lee emphasized that expanding capacity and securing design wins remain essential to supporting growth.
Supply chain constraints and equipment mix pressures warrant attention as operations scale. Management plans to provide additional details on profitability and longer-term opportunities at its Dec. 14 Investor Day.
What MKSI's Zacks Rank and Style Scores Indicate
MKSI currently carries a Zacks Rank #2 (Buy), indicating favorable near-term performance potential based on earnings estimate revision trends. Its Value, Growth and Momentum Scores of B reflect attractive characteristics across all three investment styles.
The stock's VGM Score of A reinforces its favorable combined positioning. Historically, stocks carrying a Zacks Rank #1 (Strong Buy) or 2 alongside strong Style Scores have demonstrated better relative performance potential. However, MKSI's Zacks Rank could change as analysts revise earnings estimates following the latest results.
You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
MKS Inc. (MKSI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).