

Innodata Inc. INOD combines rapid AI-related growth, expanding hyperscaler relationships and substantial liquidity with a valuation that remains above key benchmarks. The investment question is whether that growth can become durable enough to justify the premium.
The opportunity is meaningful, but so are the risks. Customer concentration, uneven project timing and an unawarded replacement for a recently ended program leave execution as the key test for investors considering the stock.
Innodata’s AI Growth Case Remains Strong
Revenues increased 55% year over year during the first nine months of 2026, supported by continued demand for AI data engineering. Innodata also raised its full-year 2026 revenue-growth outlook to at least 42% from at least 40%.
Innodata Inc Price and Consensus
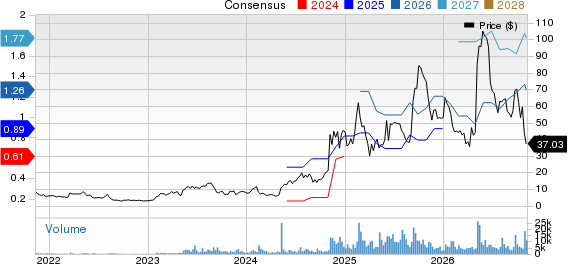
Innodata Inc price-consensus-chart | Innodata Inc Quote
The pipeline has broadened. Five new programs with a large hyperscaler are expected to contribute more than $20 million in 2027, while new customer logos and enterprise relationships add potential growth sources. EPAM Systems, Inc. EPAM is also expanding in advanced AI data and evaluation through its Frontier AI service, underscoring the growing demand for specialized model-development work.
INOD’s Valuation Leaves Less Room for Error
INOD trades at 21.8X forward 12-month earnings, above 19.3X for its Zacks sub-industry, 17.2X for the Zacks sector and 18.2X for the S&P 500. The stock therefore still commands a premium despite recent share-price weakness.
That valuation raises the execution bar. The stock’s Value Score of D also points to weaker value characteristics, making continued revenue growth and successful program conversion important if the current multiple is to hold.
Innodata Must Convert New Wins Into Durable Revenues
The two largest customers generated about 73% of revenues in the first nine months of 2026. That concentration can produce abrupt revenue changes when large programs end or shift.
A historically leading customer ended a program in mid-October, creating an expected $12 million fourth-quarter revenue hit. Management expects replacement programs in the first quarter of 2027, but those opportunities were still in late-stage discussions rather than secured awards. TaskUs, Inc. TASK, which provides AI data labeling, evaluation and robotics-related services, offers another example of competition across the same expanding AI-services market.
INOD’s Cash Strength Supports Reinvestment
Cash and cash equivalents reached $164 million as of Sept. 30, 2026, up from $82.2 million at year-end 2025. Excluding customer prepayments tied to pass-through costs, cash was approximately $153.7 million.
Net cash provided by operating activities totaled $80.5 million in the first nine months of 2026, compared with $33.7 million a year earlier. The company also reported no debt and retained an undrawn $50 million credit facility, giving it flexibility to fund research, delivery infrastructure and new AI capabilities.
INOD’s Signals Argue for Patience
The bottom line is that Innodata has a credible AI growth story, but the valuation and execution risks leave limited room for disappointment. Strong demand, new programs and liquidity support the longer-term case, while concentration and replacement timing keep the near-term setup less certain.
INOD currently carries a Zacks Rank #4 (Sell). It also has a Value Score of D, Growth Score of A, Momentum Score of A and VGM Score of A. The favorable Growth, Momentum and VGM Scores reflect attractive characteristics in those styles, but the Style Scores are designed to complement the Zacks Rank. With the Rank at #4, the combined signals argue for patience rather than treating the stock as an uncomplicated buy.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Innodata Inc (INOD): Free Stock Analysis Report
EPAM Systems, Inc. (EPAM): Free Stock Analysis Report
TaskUs, Inc. (TASK): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).