

Royal Caribbean Cruises Ltd. RCL is pursuing adjusted earnings per share (EPS) in the $20 range in 2027 under its Perfecta program, supported by stronger bookings, capacity expansion and operating efficiencies. In its third-quarter 2026 update, the company reiterated that it remained on track for the objective based on the current forward fuel-price curve.
The earnings objective is supported by improving demand indicators. In its third-quarter update, Royal Caribbean reported mid-teens year-over-year growth in recent booking volumes, while bookings for 2027 sailings rose in the high teens. Booked positions for both 2026 and 2027 were ahead of the prior year at record rates. Stronger close-in demand and onboard revenues, particularly in Europe and the Caribbean, supported third-quarter net yield growth of 0.6% in constant currency.
The 2027 capacity outlook provides another foundation for growth. Royal Caribbean expects capacity to increase 4.5%, supported by new ships and fewer drydock capacity days. Hero of the Seas and the introduction of Celebrity River Cruises will likely expand its vacation offerings. Cost performance also supports the profitability case, with full-year 2026 net cruise costs excluding fuel expected to remain approximately flat in constant currency.
The earnings trajectory remains sensitive to fuel prices and the timing of yield growth. First-quarter 2027 yields face approximately 200 basis points of structural headwinds, including drydock timing, with yield growth expected to be weighted toward the second half. Royal Caribbean indicated that it would exceed its 2027 earnings target by approximately $1 per share at the spot fuel price prevailing when Perfecta was announced, underscoring the effect of higher energy costs.
Royal Caribbean’s upward revision to its 2026 adjusted EPS guidance of $17.85-$17.95, implying approximately 14% year-over-year growth, provides a stronger earnings base heading into 2027. Reaching its $20-range adjusted EPS objective will likely depend on converting booking strength and capacity expansion into profitable revenue growth. Pricing strength and operating efficiency could support that progress, while fuel costs and first-quarter yield headwinds remain key considerations.
RCL’s Price Performance, Valuation & Estimates
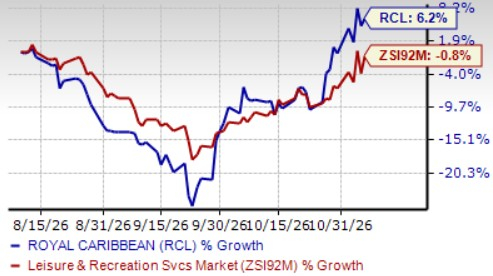
Shares of Royal Caribbean have gained 6.2% in the past three months against the industry’s 0.8% slip. In the same time frame, other industry players like Carnival Corporation Ltd. CCL have gained 6.6%, while Norwegian Cruise Line Holdings Ltd. NCLH has lost 3.4%.
RCL Stock’s Three-Month Price Performance
Image Source: Zacks Investment Research
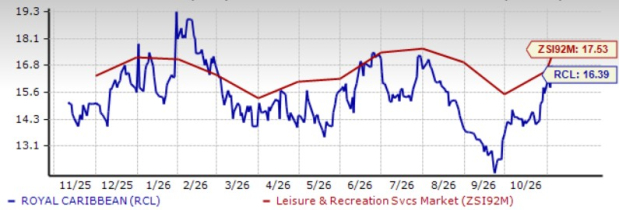
RCL stock is currently trading at a discount. It is currently trading at a forward 12-month price-to-earnings (P/E) multiple of 16.39, below the industry average of 17.53. Then again, other industry players, such as Carnival and Norwegian Cruise, have P/E ratios of 11.68 and 13.93, respectively.
RCL’s P/E Ratio (Forward 12-Month) vs. Industry
Image Source: Zacks Investment Research
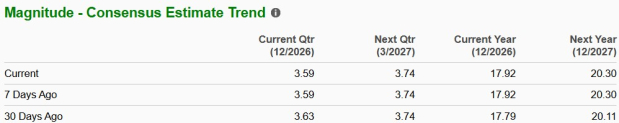
The Zacks Consensus Estimate for Royal Caribbean’s 2027 earnings per share has increased from $20.11 to $20.30 over the past 30 days.
EPS Trend of RCL Stock
Image Source: Zacks Investment Research
The company’s 2027 earnings are likely to increase 13.3% year over year. Conversely, industry players like Carnival are likely to witness growth of 12.7% year over year in fiscal 2027 earnings. NCLH is likely to project a fall of 12.6% year over year in 2027 earnings.
RCL stock currently has a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Royal Caribbean Cruises Ltd. (RCL): Free Stock Analysis Report
Carnival Corporation (CCL): Free Stock Analysis Report
Norwegian Cruise Line Holdings Ltd. (NCLH): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).