

Occidental Petroleum Corporation OXY reported third-quarter 2026 adjusted earnings of $1.91 per share, surging 274.5% year over year from 51 cents and beating the Zacks Consensus Estimate of $1.43 by 33.57%. Higher realized crude oil prices and strong adjusted Midstream and Marketing performance supported results.
Reported earnings were $1.61 per share compared with 65 cents a year earlier.
OXY's shares have gained 2.7% in the two trading sessions after earnings release, driven by positive investor sentiment following its strong third-quarter earnings results.
Total Revenues
Total revenues climbed 20.6% to $6.77 billion from $5.61 billion in the year-ago quarter.
Oil and Gas revenues totaled $6.44 billion, increasing 19.1% from $5.40 billion in the year-ago quarter. Higher commodity realizations supported revenues despite lower production volumes.
Midstream and Marketing revenues declined 1.1% year over year to $262 million from $265 million. Interest, dividends and other income increased to $171 million from $60 million a year earlier. Gains on asset sales and other items remained unchanged at $34 million.
Occidental Petroleum Corporation Price, Consensus and EPS Surprise
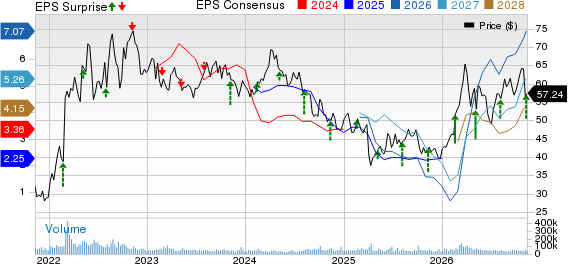
Occidental Petroleum Corporation price-consensus-eps-surprise-chart | Occidental Petroleum Corporation Quote
Occidental's Production Exceeds Guidance Midpoint
Worldwide production averaged 1,427 thousand barrels of oil equivalent per day (Mboe/d), exceeding the midpoint of management's guidance but declined 2.6% year over year from 1,465 Mboe/d. Domestic production averaged 1,203 Mboe/d compared with 1,227 Mboe/d in the prior-year quarter.
Permian Resources production increased to 812 Mboe/d from 800 Mboe/d a year earlier. Rockies and Other Domestic production declined to 281 Mboe/d from 288 Mboe/d. Gulf of America output decreased to 110 Mboe/d from 139 Mboe/d, reflecting a third-party gas pipeline constraint and extended maintenance activities. Management indicated that full production was restored in late October.
International production declined to 224 Mboe/d from 238 Mboe/d a year earlier. Despite these challenges, strong Permian and Rockies performance helped overall production exceed guidance.
OXY Benefits From Higher Commodity Realizations
Occidental's worldwide realized crude oil price increased 32.6% year over year to $85.91 per barrel from $64.78. The average WTI and Brent marker prices were $85.79 and $91.62 per barrel, respectively, compared with $64.93 and $68.14 a year earlier.
Worldwide realized natural gas liquids prices advanced 25.7% to $24.63 per barrel from $19.60. Domestic realized natural gas prices improved to $1.61 per thousand cubic feet from $1.48 in the year-ago quarter.
Sequentially, worldwide realized crude oil prices declined 11.2% from $96.78 per barrel, weighing on Oil and Gas profitability. Higher domestic natural gas realizations partially offset this pressure.
Occidental's Operating Costs Decline Y/Y
Total costs and other deductions decreased 5.5% year over year to $4.51 billion. Oil and gas lease operating expenses increased 1.5% to $1.19 billion, while transportation and gathering expenses declined 6.5% to $445 million.
Depreciation, depletion and amortization expenses decreased 8.4% to $1.78 billion. Interest and debt expense dropped 70.7% to $78 million, reflecting the company's accelerated debt-reduction efforts.
Oil and Gas reported adjusted pre-tax income of $2.67 billion compared with $1.32 billion in the year-ago quarter. Midstream and Marketing adjusted pre-tax income increased to $309 million from $51 million, exceeding the upper end of management's guidance.
OXY's Cash Flow Supports Further Debt Reduction
During the third quarter, operating cash flow from continuing operations totaled $4.13 billion. Excluding working-capital movements, operating cash flow reached $4.10 billion. Capital expenditures, net of noncontrolling interest, were $1.32 billion, resulting in free cash flow before working capital of $2.78 billion.
Occidental reduced principal debt by $1.8 billion during the quarter, reaching its $10 billion milestone. Year-to-date debt repayments totaled $10.4 billion, generating approximately $740 million in annualized interest savings compared with 2025.
The company ended September with $3.88 billion in cash and cash equivalents. Management established a new principal debt target of $6 billion and continues to prioritize balance-sheet strengthening.
Occidental Provides Q4 Outlook
For the fourth quarter of 2026, Occidental expects worldwide production of 1,430-1,470 Mboe/d. Permian production is projected at 820-840 Mboe/d, while Rockies and Other Domestic output is anticipated at 271-277 Mboe/d.
Gulf of America production is expected between 112 Mboe/d and 120 Mboe/d. International production is expected to be 227-233 Mboe/d.
Management expects fourth-quarter Midstream and Marketing pre-tax income of $100-$200 million. Net capital expenditures are projected at approximately $1.3 billion, with adjusted interest expense of nearly $130 million.
The company is targeting more than $4 billion in incremental annual sustainable cash flow by 2030 through operating efficiencies, lower sustaining capital requirements and reduced financing costs.
Zacks Rank of OXY
Occidental currently carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Recent Releases
Murphy Oil Corporation MUR reported third-quarter 2026 adjusted earnings of $1.08 per share, up 163.4% from 41 cents in the year-ago quarter. The figure surpassed the Zacks Consensus Estimate of 91 cents per share by 18.68%. Stronger commodity prices and lower operating costs supported the results.
Total revenues of $855 million increased 16.6% year over year and beat the consensus estimate of $767 million by 11.52%.
TotalEnergies SE TTE reported third-quarter 2026 operating earnings of $4.03 (€3.50) per share, which lagged the Zacks Consensus Estimate of $4.11 by 1.95%. The bottom line improved 127.7% from the year-ago figure of $1.77 (€1.50).
Total revenues were $66.82 billion, up 37.2% year over year, surpassing the Zacks Consensus Estimate of $53.72 billion by 24.39%. Strong refining margins and higher gas prices supported results.
CNX Resources Corporation CNX reported third-quarter 2026 operating earnings of 61 cents per share, missing the Zacks Consensus Estimate of 65 cents by 6.2%. Lower natural gas prices and production volumes weighed on quarterly performance despite improved cost efficiency and continued free cash flow generation.
CNX reported revenues of $373 million, missing the Zacks Consensus Estimate of $400 million by 6.8%. Revenues declined 7.1% from $401 million in the year-ago quarter.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Occidental Petroleum Corporation (OXY): Free Stock Analysis Report
CNX Resources Corporation. (CNX): Free Stock Analysis Report
Murphy Oil Corporation (MUR): Free Stock Analysis Report
TotalEnergies SE Sponsored ADR (TTE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).