

Post Holdings, Inc. POST is likely to witness top- and bottom-line decline when it reports fourth-quarter fiscal 2026 earnings on Nov. 19 after market close. The Zacks Consensus Estimate for revenues is pegged at around $2 billion, indicating a roughly 12% decrease from the year-ago period figure.
The consensus mark for earnings has declined by 3 cents over the past seven days to $1.66 a share, suggesting a 20.6% fall from the year-ago period figure. POST has a trailing four-quarter surprise of 16.2%, on average.
Post Holdings, Inc. Price, Consensus and EPS Surprise
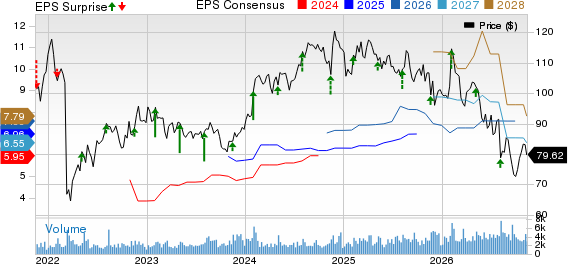
Post Holdings, Inc. price-consensus-eps-surprise-chart | Post Holdings, Inc. Quote
Factors Likely to Influence POST’s Upcoming Results
Post Holdings’ fourth-quarter performance is likely to have been pressured by persistent volume softness across certain product categories. Weak demand for ready-to-eat cereals, distribution losses in value cereals and challenging pet food market conditions are likely to have weighed on Post Consumer Brands’ organic sales. Competitive promotional activity in pet food and ongoing assortment transitions could have further constrained volumes.
Profitability is likely to have faced pressure from the normalization of avian influenza-related pricing benefits in the Foodservice segment. Management anticipated a sequential moderation in Foodservice earnings during the fourth quarter, potentially weighing on overall performance despite improvements in customer service levels and production capabilities.
The absence of prior-year avian influenza-related pricing benefits and contributions from the divested Crystal Farms business is likely to have affected Refrigerated Retail’s year-over-year performance. Elevated fuel and freight expenses, alongside unfavorable egg-pricing dynamics, could have further pressured margins.
Nevertheless, POST’s results are likely to have benefited from improving operational efficiencies and selective market share gains. Management anticipated sequential improvement in Refrigerated Retail, with the rest of the portfolio expected to remain relatively stable. Progress in Nutrish brand initiatives and opportunities in premium private-label pet food may have provided additional support.
Earnings Whispers for POST
Our proven model doesn’t conclusively predict an earnings beat for Post Holdings this time. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is not the case here.
Post Holdings currently carries a Zacks Rank #4 (Sell) and has an Earnings ESP of 0.00%. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Stocks With the Favorable Combination
Here are some companies worth considering, as our model shows that these have the right combination of elements to beat on earnings this reporting cycle.
Dollar General Corporation DG currently has an Earnings ESP of +8.66% and a Zacks Rank of 2. The consensus estimate for quarterly revenues is $11.1 billion, which suggests 4.5% growth from the figure reported in the prior-year quarter. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Dollar General’s upcoming quarter’s EPS is pegged at $1.40, which suggests a 9.4% increase from the year-ago period’s figure. DG delivered a trailing four-quarter earnings surprise of 19.1%, on average.
Ulta Beauty, Inc. ULTA currently has an Earnings ESP of +1.84% and a Zacks Rank #2. The consensus estimate for quarterly revenues is pegged at nearly $3 billion, which indicates 4.5% growth from the figure reported in the prior-year quarter.
The Zacks Consensus Estimate for Ulta Beauty’s upcoming quarter’s EPS is pegged at $5.60, which indicates almost 9% growth from the figure reported in the prior-year quarter. ULTA delivered a trailing four-quarter earnings surprise of 7.6%, on average.
The Kroger Co. KR currently has an Earnings ESP of +7.26% and a Zacks Rank of 3. The Zacks Consensus Estimate for KR’s upcoming quarter’s revenues is pegged at $34.6 billion, suggesting a 2.1% jump from the figure reported in the prior-year quarter.
The consensus estimate for Kroger’s upcoming quarter’s EPS is pegged at $1.16 per share, implying 10.5% growth from the year-ago quarter’s earnings of 36 cents. KR delivered a trailing four-quarter earnings surprise of 2.7%, on average.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Post Holdings, Inc. (POST): Free Stock Analysis Report
Dollar General Corporation (DG): Free Stock Analysis Report
The Kroger Co. (KR): Free Stock Analysis Report
Ulta Beauty Inc. (ULTA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).