We invite you to explore the original implementation of the K²VAE framework — a flexible model capable of linearly approximating complex dynamics in latent space. This article demonstrates how to implement key components in MQL5, including parameterized matrices and how to manage them outside standard neural network layers. This material will be useful for anyone looking for a practical approach to building interpretable time-series models.
The article describes an approach to trade labeling using oscillators for machine learning models. This eliminates look-ahead bias. It has been shown that this type of labeling does not lead to model overfitting, and the strategies continue to perform well over the long term.
We invite you to dive into the exciting world of LightGTS — a lightweight yet powerful framework for time-series forecasting, where adaptive convolution and RoPE encoding are combined with innovative attention mechanisms. In our article, you will find a detailed description of all components — from creating patches to the complex mixture of experts in the decoder — ready for integration into MQL5 projects. Discover how LightGTS takes automated trading to a whole new level!
We invite you to embark on an exciting journey through the world of adaptive analysis of financial time series and learn how to turn complex spectral analysis and flexible convolution into real trading signals. You will see how LightGTS listens to the market rhythm, adapting to its changes through a variable-window stride, and how OpenCL acceleration can turn computation into a fast track to profitable decisions.
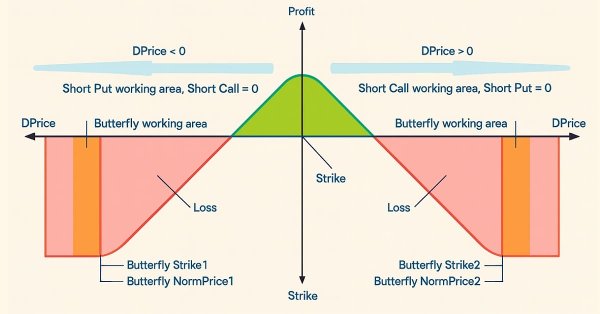
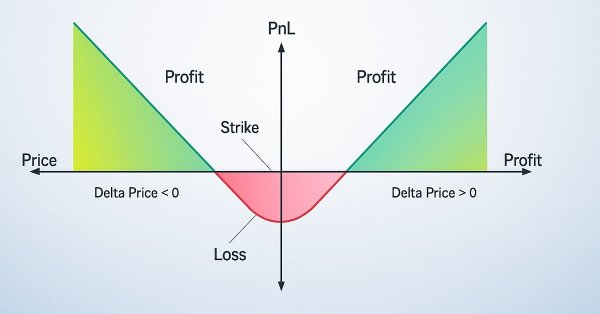
In this article, we will examine how to reduce risk (and whether it is even possible to do so) in option strategies where risk is initially unlimited. This applies to strategies based on writing options, i.e., range-bound strategies. We will also consider ways to lock in profits for option strategies based on purchasing options, i.e., trend-following strategies. As always, we will add new useful features to our Expert Advisor (EA) and improve the existing ones.
We invite you to learn about the innovative technique of adaptive patching — a method for flexibly segmenting time series while taking their internal periodicity into account. We will also look at an efficient encoding technique that preserves important semantic characteristics when working with data at different scales. These methods open up new possibilities for the accurate processing of complex, multiscale data characteristic of financial markets and significantly improve the stability and reliability of forecasts.
The article provides a fascinating look at how SwiGLU embedding reveals hidden market patterns, and how a sparse Mixture of Experts within a Decoder-Only Transformer makes forecasts more accurate at reasonable computational cost. We take an in-depth look at the integration of Time‑MoE into MQL5 and OpenCL, and provide a step-by-step guide to configuring and training the model.
The article bridges automated placement with manual analysis for the Fibonacci family in MQL5. It scans charts, identifies user Fibonacci objects, and normalizes their level arrays, interaction flags, and visuals per object type while preserving coordinates. With manual-priority enforcement, Expert Advisors can evaluate both human and code-generated tools reliably, without duplicates or runtime indexing issues.
We invite you to explore the practical implementation of a sparse mixture of experts block for time series in the OpenCL computing environment. This article provides a step-by-step explanation of how masked multi-window convolution works, as well as how gradient-based training is organized in the presence of multiple information streams.
A hybrid exit engine for MQL5 replaces static TPs with CRT-derived structural levels. The CRT_ProfitConserve class secures a partial at the first level and then trails the remaining position by structural anchors rather than fixed pips. The article walks through the class API, essential methods, and example usage in EAs, providing a clear path to embed CRT-based exits into existing strategies.
We build a tCISD program in MQL5 that pairs Quarterly Theory cycles anchored to New York time with a correlated-symbol SSMT divergence to time reversals. The article shows how to map cycles and quarters, detect the cross-symbol sweep disagreement, and derive the tCISD level whose break confirms the change in delivery. You will get a working entry logic that arms on divergence and executes on a confirmation close or a retest.
We invite you to explore the modern Time-MoE framework, which has been adapted for time series forecasting tasks. In this article, we will implement the key components of the architecture step by step, providing explanations and practical examples along the way. This approach will allow you not only to understand how the model works, but also to apply those principles to real-world trading scenarios.
The article focuses on the practical implementation of the TimeFound model for time series forecasting. The key stages of implementing the framework's main approaches using MQL5 are examined.
Build a level-2 path-signature engine in pure MQL5 to read the lead-lag ordering between two data streams without choosing a lag and without a linear model. The article delivers a reusable library, an indicator that plots the Levy‑area oscillator, and a simple rule‑based Expert Advisor. Code is cross‑checked against closed‑form cases, and the components are ready to plug into your projects.
The article describes the development of a multi-agent machine learning system for algorithmic trading on MetaTrader 5 based on reinforcement learning. The system has a three-tier architecture: memory neurons store experience, agents make independent decisions, and the collective mind combines them through weighted voting. The system is continuously improved through Q-learning, pruning of ineffective neurons, and evolutionary reduction of exploration.
In this article, we build the core of the TimeFound intelligent model step by step, adapting it to real-world time series forecasting tasks. If you are interested in the practical implementation of neural network patching algorithms in MQL5, you have come to the right place.
The article implements a self-sufficient Adaptive SuperTrend EA with internal calculations on a selectable timeframe, avoiding external buffers and indicator files. It includes risk-based lot sizing, ATR stops, stepwise RR trailing, optional anti-repainting confirmation, and session control. Practitioners can reuse the structure for consistent new‑bar signal handling and broker‑compliant order validation.
In this article, we will examine the application of mathematics to grid strategies. We will consider the basic principles of the strategy, as well as its advantages and disadvantages. You will learn how to build a trading grid, set optimal parameters, and manage risks effectively.
This article introduces a modular Fair Value Gap (FVG) detection engine for MQL5 packaged as a reusable include class, it evaluates imbalance zones on closed bars, applies a Simple True Range average filter to eliminate low-volatility noise, and supports wick-touch and close-through mitigation. A companion diagnostic indicator plots active gaps, and an Expert Advisor template demonstrates automated pullback entries with new-bar execution controls.
We build a session-based reversal program in MQL5 using the Bread and Butter Judas Swing model. It derives a higher-timeframe daily bias, defines New York kill zones, maps each session's premium and discount from the live range, and requires a sweep before a market structure shift confirms entry. Readers get a ready approach to arm setups only during active sessions and execute in the bias direction with clear, testable rules.
The Mantis framework transforms complex time series into informative tokens and serves as a reliable foundation for an intelligent trading agent capable of operating in real time.
Kohonen's self-organizing maps transform the chaos of market data into an ordered two-dimensional map, where similar patterns are grouped together. The article demonstrates a complete implementation of a SOM in an MQL5 Expert Advisor with 400 neurons and continuous learning. We break down the Best Matching Unit search algorithm, weight updates using a Gaussian neighborhood function, integration with quantum effects, and the generation of trading signals. The code is open-source, the math is clear, and the results are verifiable.
We implement a Hierarchical Risk Parity allocator in MQL5 as a single class, validate each stage against an independent Python reference, and package it in a rebalancing Expert Advisor. The pipeline covers returns, covariance/correlation, clustering, quasi-diagonalization, and recursive bisection, and contrasts HRP with Markowitz on stressed data. You finish with a verified allocator and an EA ready for basket-level testing.
This part extends the series with a modular, event-driven MQL5 pipeline: swing detection feeds an object placer for trendlines, SR, Fibonacci, channels, and pitchforks; evaluators monitor interactions and generate signals; adaptive logic executes trades with valid stops per instrument. The topology manager synchronizes placement, scanning, and processing. The code is structured into reusable components for easy reuse and scaling.
Mantis is a versatile tool for in-depth time series analysis that can be flexibly scaled to accommodate any financial scenario. Learn how a combination of patching, local convolutions, and cross-attention enables a highly accurate interpretation of market patterns.
Meet Mantis — a lightweight foundation model for time series classification based on a Transformer architecture, featuring contrastive pre-training and hybrid attention that deliver record-breaking accuracy and scalability.
We continue our acquaintance with the Mamba4Cast framework. Today, we will delve into the practical implementation of the proposed approaches. Mamba4Cast was designed not for lengthy warm-up on every new time series, but for immediate deployment. Thanks to the concept of Zero-Shot Forecasting, the model can produce high-quality forecasts on real-world data without additional training or hyperparameter tuning.
The article discusses flat (non-directional) and trend-following (directional) option strategies and their implementation in MQL5. The EA described in the previous article is updated. The display of option levels has been added. Now it is time to examine the strategies used by options traders in practice and put them into action.
Learn to assemble an MT5 Expert Advisor that hosts a chart management dashboard written in MQL5. The guide walks through shared definitions, symbol acquisition and filtering, chart lifecycle functions, and a UI panel with search, scrolling, and state indicators, all driven by events and a timer. The result is a reproducible tool that reduces clicks and accelerates multi-symbol analysis.
This article builds a complete MQL5 Expert Advisor that implements the original Turtle Trading rules from Curtis Faith. It covers both systems: 20/55-day breakouts, the System 1 skip rule, N (Wilder ATR) for volatility-adjusted sizing, a four‑unit pyramid with N/2 adds, a unified 2N stop, and 10/20-day exits. You will get compilable code, implementation details, and a backtesting procedure on EURUSD.
This article presents TrendTemplateEA, an Expert Advisor implementing Mark Minervini's eight-condition trend template for daily forex charts. It evaluates all conditions on every bar and enters only when they are simultaneously satisfied, using RSI above 50 in place of the stock market RS rating. The entry trigger is a 20-bar high breakout on expanding volume, with all rules coded and testable in MQL5.
This article demonstrates a practical approach to researching trading ideas using a range breakout strategy as an example. We will go through the entire process, from formalizing trading rules and building a baseline model to parameter optimization, forward testing, and evaluating the robustness of the results. The main goal of the article is to develop an understanding of how statistics and testing can be used to identify, validate, and evaluate trading hypotheses.
We enhance the manual backtesting EA with real-time lot adjustment, an order module for buy/sell stops and limits, and a Trade Manager to modify TP/SL and close positions individually. The article explains control setup with CButton/CBmpButton/CEdit, logic in OnTick, and workarounds for Strategy Tester input constraints. Readers can reuse these components to speed up testing workflows and implement robust trade management.
We demonstrate a practical customization path for a built-in MetaTrader 5 EA using BullishBearish MeetingLines Stoch. The workflow covers baseline testing in the Strategy Tester, parameter optimization, and code-level changes. Two modifications are implemented: exposing Stochastic thresholds as inputs and adding an optional Moving Average filter to limit counter‑trend signals. The article includes the full modified code for replication.
This article introduces ap.mqh, the ALGLIB port for MQL5, and demonstrates its use in multi‑asset workflows that require robust linear algebra. It covers why built-in indicators fall short, then implements polynomial regression, a rolling correlation matrix indicator, and an adaptive hedge ratio estimator using ridge regression with Cholesky. Practical code shows how to compute spread z‑scores and execute coordinated pairs trades entirely within MetaTrader 5.
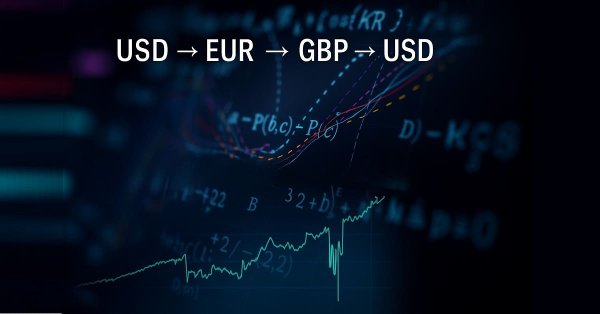
In this article, triangular arbitrage is presented as a problem of finding cycles in a directed graph, where the vertices are currencies and the edges are currency pairs with weight rates. Profitable cycle: product of weights >1. Our Floyd-Warshall and DFS algorithms find optimal currency exchange paths that return to the starting point with a profit.
We describe an MQL5 framework that aligns entries with session rhythms and scheduled clock events. A script identifies the broker's time zone and DST by detecting NFP spikes on EURUSD and matching them to EU/US/AU transition dates, producing EA‑ready settings. Session-to-broker time conversion and 15-minute marks constrain execution. A multi‑timeframe AMA signal aggregates trends for strategy selection and optimization.
This article shows how to build a synthetic custom symbol in MQL5 by averaging OHLC data from multiple instruments into a single derived price series. It covers symbol collection and validation, custom symbol creation and configuration, timestamp alignment, historical reconstruction, and lightweight live updates. The result is a reusable method for creating synthetic instruments suitable for correlation analysis, index-style modeling, indicator development, and strategy testing.
The article presents a complete implementation of TimeGPT, a specialized Transformer-based architecture for forecasting financial time series on the MetaTrader 5 platform. Adaptation of the attention mechanism to financial data, selective tokenization of price changes, hardware-aware optimizations, and advanced learning techniques are discussed. Included are practical testing results showing 87% forecast accuracy over a 24-bar horizon with a training time of 15 minutes on the CPU. We also present a ready-made trading EA with automatic retraining.
This article shows how to build an MQL5 Expert Advisor around the UT Bot Alerts indicator. The EA reads custom indicator signals via iCustom() and CopyBuffer(), evaluates entries only on new bars, using the last closed candle at index 1, and enforces a one-direction-at-a-time model by closing opposite positions before taking new entries. It also adds optional ATR-based stop-losses, reward-to-risk take-profits, dedicated buy/sell execution functions, magic-number tracking, and basic backtesting for repeatable evaluation.